Loading
Scheffel Boyle
  • Home
  • About Us
    • Our Team
    • Our Values
    • Scheffel Boyle News
    • Professional Affiliations
    • Client Testimonials
    • Peer Review
    • Scheffel Boyle Shares
    • BDO Alliance USA
  • Services
    • Tax Planning & Preparation
    • Audit & Assurance
    • Accounting Services
    • Consulting Services
    • Financial Advisory
  • Clients & Industries
    • Construction
    • Financial Institutions
    • Agribusiness
    • Governmental Entities
    • Non-Profit Organizations
    • Privately-Held Businesses
    • Individual Clients
    • Employee Benefit Plans
  • Resources
    • Knowledge Center
    • Coronavirus Resource Center
    • Helpful Links
  • Careers
    • Benefits
    • Available Opportunities
    • College Students
  • Contact Us
    • Locations
      • Alton, IL
      • Belleville, IL
      • Carrollton, IL
      • Columbia, IL
      • Edwardsville, IL
      • Highland, IL
      • Jerseyville, IL
  • Click to open the search input field Click to open the search input field Search
  • Menu Menu
  • Link to Facebook
  • Link to LinkedIn

Scheffel BOO-yle Belleville Trick-or-Treats Downtown

October 31, 2018

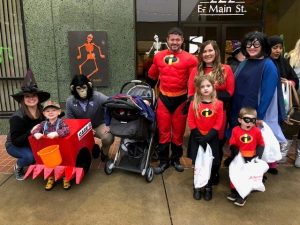
Our Belleville office really got into the Halloween spirit over the weekend! The team participated in the City of Belleville’s Downtown Trick-or-Treat and handed out candy outside the office. We saw some great costumes and had a wonderful night!


https://scheffelboyle.com/wp-content/uploads/2018/10/B1.jpg 480 640 brett@bonniburns.com https://scheffelboyle.com/wp-content/uploads/2022/06/Transparent-Logo-5.png brett@bonniburns.com2018-10-31 14:18:012020-01-28 15:26:27Scheffel BOO-yle Belleville Trick-or-Treats Downtown

Year-End Tax Strategies for Accrual-Basis Businesses

October 31, 2018

The last month or so of the year offers accrual-basis taxpayers an opportunity to make some timely moves that might enable them to save money on their 2018 tax bills. The key to saving tax as an accrual-basis taxpayer is to properly record and recognize expenses that were incurred this year but won’t be paid until 2019. Doing so will enable you to deduct those expenses on your 2018 federal tax return.

Common examples of such expenses include commissions, salaries and wages; payroll taxes; advertising; and interest. Also look into expenses such as utilities, insurance and property taxes. You can also accelerate deductions into 2018 without paying for the expenses in 2018 by charging them on a credit card. (This works for cash-basis taxpayers, too.)

In addition, review all prepaid expense accounts and write off any items that have been used up before the end of the year. If you prepay insurance for a period beginning in 2018, you can expense the entire amount this year rather than spreading it between 2018 and 2019, as long as a proper method election is made. This is treated as a tax expense and thus won’t affect your internal financials.

There are many other strategies to explore. Review your outstanding receivables and write off any receivables you can establish as uncollectible. Pay interest on all shareholder loans to the company. Update your corporate record book to record decisions and be better prepared for an audit. Interested? We can provide further details on these and other year-end tax tips for accrual-basis businesses.

Copyright © 2018

https://scheffelboyle.com/wp-content/uploads/2018/10/taxes.jpeg 1500 1681 brett@bonniburns.com https://scheffelboyle.com/wp-content/uploads/2022/06/Transparent-Logo-5.png brett@bonniburns.com2018-10-31 13:55:262020-01-28 15:26:48Year-End Tax Strategies for Accrual-Basis Businesses

Getting Caught up with the Latest Catch-Up Contributions

October 18, 2018
One could say that there are only two key milestones in retirement planning: the day you begin participating in a retirement savings account and the day you begin drawing money from it. But, of course, there are others as well.

One is the day you turn 50 years old. Why? Because those age 50 or older on December 31 of any given year can start making “catch-up” contributions to their employer-sponsored retirement plans by that date. These are additional contributions to certain retirement accounts beyond the regular annual limits.

Maybe you haven’t yet saved as much for retirement as you’d like to. Or perhaps you’d just like to make the most of tax-advantaged savings opportunities. Whatever the case may be, let’s get caught up with the latest catch-up contribution amounts.

401(k)s and SIMPLEs

Under 2018 401(k) limits, if you’re age 50 or older, after you’ve reached the $18,500 maximum limit for all employees, you can contribute an extra $6,000, for a total of $24,500. If your employer offers a Savings Incentive Match Plan for Employees (SIMPLE) instead, your regular contribution maxes out at $12,500 in 2018. If you’re 50 or older, you’re allowed to contribute an additional $3,000 — or $15,500 in total for the year.

But, check with your employer because, while most 401(k) plans and SIMPLEs offer catch-up contributions, not all do.

Self-Employed Plans

If you’re self-employed, retirement plans such as an individual 401(k) — or solo 401(k) — also allow catch-up contributions. A solo 401(k) is a plan for those with no other employees. You can defer 100% of your self-employment income or compensation, up to the regular yearly deferral limit of $18,500, plus a $6,000 catch-up contribution in 2018. But that’s just the employee salary deferral portion of the contribution.

You can also make an “employer” contribution of up to 20% of self-employment income or 25% of compensation. The total combined employee-employer contribution is limited to $55,000, plus the $6,000 catch-up contribution.

IRAs, Too

Catch-up contributions to non-Roth accounts not only can enlarge your retirement nest egg, but also can reduce your 2018 tax liability. And keep in mind that catch-up contributions are available for IRAs, too, but the deadline for 2018 contributions is April 15, 2019. If you have questions about catch-up contributions or other retirement saving strategies, please contact us.

Copyright © 2018

https://scheffelboyle.com/wp-content/uploads/2018/10/retirement.jpeg 1500 2247 brett@bonniburns.com https://scheffelboyle.com/wp-content/uploads/2022/06/Transparent-Logo-5.png brett@bonniburns.com2018-10-18 13:52:392020-01-28 15:26:40Getting Caught up with the Latest Catch-Up Contributions

Is Now the Time for Some Life Insurance?

October 11, 2018
Many people reach a point in life when buying some life insurance is highly advisable. Once you determine that you need it, the next step is calculating how much you should get and what kind.


Careful Calculations

If the coverage is to replace income and support your family, this starts with tallying the costs that would need to be covered, such as housing and transportation, child care, and education — and for how long. For many families, this will be only until the youngest children are on their own.

Next, identify income available to your family from Social Security, investments, retirement savings and any other sources. Insurance can help bridge any gaps between the expenses to be covered and the income available.

If you’re purchasing life insurance for another reason, the purpose will dictate how much you need:

Funeral costs. An average funeral bill can top $7,000. Gravesite costs typically add thousands more to this number.

Mortgage payoff. You may need coverage equal to the amount of your outstanding mortgage balance.

Estate planning. If the goal is to pay estate taxes, you’ll need to estimate your estate tax liability. If it’s to equalize inheritances, you’ll need to estimate the value of business interests going to each child active in your business and purchase enough coverage to provide equal inheritances to the inactive children.

Term vs. Permanent

The next question is what type of policy to purchase. Life insurance policies generally fall into two broad categories: term or permanent.

Term insurance is for a specific period. If you die during the policy’s term, it pays out to the beneficiaries you’ve named. If you don’t die during the term, it doesn’t pay out. It’s typically much less expensive than permanent life insurance, at least if purchased while you’re relatively young and healthy.

Permanent life insurance policies last until you die, so long as you’ve paid the premiums. Most permanent policies build up a cash value that you may be able to borrow against. Over time, the cash value also may reduce the premiums.

Because the premiums are typically higher for permanent insurance, you need to consider whether the extra cost is worth the benefits. It might not be if, for example, you may not require much life insurance after your children are grown.

But permanent life insurance may make sense if you’re concerned that you could become uninsurable, if you’re providing for special-needs children who will never be self-sufficient, or if the coverage is to pay estate taxes or equalize inheritances.

Some Comfort

No one likes to think about leaving loved ones behind. But you’ll no doubt find some comfort in having a life insurance policy that helps cover your family’s financial needs and plays an important role in your estate plan. Let us help you work out the details.
Copyright © 2018

https://scheffelboyle.com/wp-content/uploads/2018/10/life-insurance.jpg 1500 2250 brett@bonniburns.com https://scheffelboyle.com/wp-content/uploads/2022/06/Transparent-Logo-5.png brett@bonniburns.com2018-10-11 13:46:032018-11-05 09:07:36Is Now the Time for Some Life Insurance?

Taxable vs. Tax-Advantaged: Where to Hold Investments

October 5, 2018
When investing for retirement or other long-term goals, people usually prefer tax-advantaged accounts, such as IRAs, 401(k)s or 403(b)s. Certain assets are well suited to these accounts, but it may make more sense to hold other investments in traditional taxable accounts.

Know the Rules

Some investments, such as fast-growing stocks, can generate substantial capital gains, which may occur when you sell a security for more than you paid for it.

If you’ve owned that position for over a year, you face long-term gains, taxed at a maximum rate of 20%. In contrast, short-term gains, assessed on holding periods of a year or less, are taxed at your ordinary-income tax rate — maxing out at 37%. (Note: These rates don’t account for the possibility of the 3.8% net investment income tax.)

Choose Tax Efficiency

Generally, the more tax efficient an investment, the more benefit you’ll get from owning it in a taxable account. Conversely, investments that lack tax efficiency normally are best suited to tax-advantaged vehicles.

Consider municipal bonds (“munis”), either held individually or through mutual funds. Munis are attractive to tax-sensitive investors because their income is exempt from federal income taxes and sometimes state and local income taxes. Because you don’t get a double benefit when you own an already tax-advantaged security in a tax-advantaged account, holding munis in your 401(k) or IRA would result in a lost opportunity.

Similarly, tax-efficient investments such as passively managed index mutual funds or exchange-traded funds, or long-term stock holdings, are generally appropriate for taxable accounts. These securities are more likely to generate long-term capital gains, which have more favorable tax treatment. Securities that generate more of their total return via capital appreciation or that pay qualified dividends are also better taxable account options.

Take Advantage of Income

What investments work best for tax-advantaged accounts? Taxable investments that tend to produce much of their return in income. This category includes corporate bonds, especially high-yield bonds, as well as real estate investment trusts (REITs), which are required to pass through most of their earnings as shareholder income. Most REIT dividends are nonqualified and therefore taxed at your ordinary-income rate.

Another tax-advantaged-appropriate investment may be an actively managed mutual fund. Funds with significant turnover — meaning their portfolio managers are actively buying and selling securities — have increased potential to generate short-term gains that ultimately get passed through to you. Because short-term gains are taxed at a higher rate than long-term gains, these funds would be less desirable in a taxable account.

Get Specific Advice

The above concepts are only general suggestions. Please contact us for specific advice on what may be best for you.


Sidebar: Doing Due Diligence on Dividends

If you own a lot of income-generating investments, you’ll need to pay attention to the tax rules for dividends, which belong to one of two categories:

  1. Qualified. These dividends are paid by U.S. corporations or qualified foreign corporations. Qualified dividends are, like long-term gains, subject to a maximum tax rate of 20%, though many people are eligible for a 15% rate. (Note: These rates don’t account for the possibility of the 3.8% net investment income tax.)
  2. Nonqualified. These dividends — which include most distributions from real estate investment trusts and master limited partnerships — receive a less favorable tax treatment. Like short-term gains, nonqualified dividends are taxed at your ordinary-income tax rate.

Copyright © 2018

https://scheffelboyle.com/wp-content/uploads/2018/10/investment.jpeg 1500 2296 brett@bonniburns.com https://scheffelboyle.com/wp-content/uploads/2022/06/Transparent-Logo-5.png brett@bonniburns.com2018-10-05 13:33:272018-11-05 09:07:45Taxable vs. Tax-Advantaged: Where to Hold Investments

Pages

  • 2025 Seminar Registration
  • 2025 Seminar Registration Presentation Slides
  • 2026 Summer Sneak Peek
  • About Us
  • Accounting and Office Manager
  • Accounting Clerk
  • Accounting Services
  • Administrative Assistant
  • Administrative Assistant – Columbia Office
  • Administrative Assistant – Edwardsville Office
  • Administrative Support Specialist
  • Administrative Support Specialist
  • AGCI Webinar Presentation
  • Agribusiness
  • Alton, IL
  • Andrea Suhre
  • Andrea Suhre
  • Audit & Assurance
  • Available Opportunities
  • BDO Alliance USA
  • Belleville, IL
  • Bookkeeper
  • Bookkeeper/Payroll Specialist
  • Brian Otten
  • Business Valuations
  • Careers
  • Carrollton, IL
  • Columbia, IL
  • Construction Accounting
  • Construction Newsletter
  • Construction Tax Seminar Presentation
  • Consulting Services
  • Contact Us
  • Coronavirus Resource Center
  • Cory E. Gallivan
  • Crystal Bock
  • Crystal Bock
  • Dale Holtmann
  • Daniel Phipps
  • Data Entry Assistants
  • Dennis E. Ulrich
  • E-News Sign Up
  • Edwardsville, IL
  • Elements
  • Employee Benefit Plans
  • Experienced Accountants
  • Experienced Public Accountant
  • Financial Calculators
  • Financial Institution
  • FOCUS Internship Program
  • Full-Time Interview Sign-Up
  • George Moore
  • Governmental Entities
  • Heather Clugston
  • Helpful Links
  • Highland, IL
  • Home
  • Howard Held
  • Individual Clients
  • Industries
  • Interview Thank You
  • Interview Timeslots
  • Jerseyville, IL
  • Julie Billeter
  • Julie Graham
  • Kathy Fitzgerald
  • Keith Brinkmann
  • Knowledge Center
  • Lisa Bohnenstiehl
  • Locations
  • Mark Korte
  • Marketing Specialist
  • Michael D. Ulrich
  • Michael E. Fitzgerald
  • Michael T. Brokering
  • Non-Profit Organizations
  • Office Accounting Assistant
  • Our Team
  • Outsourced Accountant
  • Part-Time Bookkeeper
  • Payroll Assistant
  • Payroll Supervisor
  • Peer Review
  • Privacy Policy
  • Privately-Held Businesses
  • Professional Affiliations
  • Recruiting Events
  • Recruiting/Human Resources Coordinator
  • Resources
  • Robyn M. Klingler
  • Russell Gregson
  • Sarah Smith
  • Scheffel Boyle News
  • Scheffel Boyle Shares
  • Scott Weber
  • Seasonal Tax Preparer
  • Services
  • SIBA Webinar Presentation
  • Sneak Peek Survey
  • Spring Tax Internship Program 2026
  • STL Ag Club Webinar Prez
  • Summer Audit Internship Program
  • Summer Audit Internship Program 2026
  • Tax Planning & Preparation
  • Tax Talks Information
  • Tax Talks Presentation
  • Testimonials
  • Webinar Presentation May 14
  • Welcome Email
  • Year-End Tax Planning Seminars
  • Accountant – Carrollton
  • Administrative Assistant – Alton Office
  • Administrative Assistant – Belleville Office
  • Administrative Assistant – Columbia Office
  • Seasonal Administrative Assistants
  • Seasonal Data Input
  • Staff Accountant

Categories

  • Blog
  • Construction
  • Coronavirus Resource Center
  • Frontpage
  • Knowledge Center
  • Scheffel News
  • Uncategorized

Archive

  • August 2026
  • May 2026
  • November 2025
  • October 2025
  • July 2025
  • February 2024
  • July 2023
  • May 2023
  • February 2023
  • January 2023
  • November 2022
  • August 2022
  • July 2022
  • June 2022
  • March 2022
  • February 2022
  • January 2022
  • December 2021
  • June 2021
  • May 2021
  • April 2021
  • March 2021
  • February 2021
  • January 2021
  • December 2020
  • November 2020
  • October 2020
  • September 2020
  • August 2020
  • July 2020
  • June 2020
  • May 2020
  • April 2020
  • March 2020
  • February 2020
  • January 2020
  • December 2019
  • November 2019
  • October 2019
  • September 2019
  • August 2019
  • July 2019
  • June 2019
  • May 2019
  • April 2019
  • March 2019
  • February 2019
  • January 2019
  • December 2018
  • November 2018
  • October 2018
  • September 2018
  • August 2018
  • July 2018
  • June 2018
  • May 2018
  • April 2018
  • March 2018
  • February 2018
  • January 2018
  • December 2017
  • November 2017
  • October 2017
  • September 2017
  • August 2017
  • July 2017
  • June 2017
  • May 2017
  • April 2017
  • March 2017
  • February 2017
  • January 2017
  • December 2016
  • October 2016
  • September 2016
  • August 2016
  • July 2016
  • May 2016
  • April 2016
  • March 2016
  • February 2016
  • January 2016
  • December 2015
  • November 2015
  • August 2015
  • July 2015
  • June 2015
  • February 2015
  • January 2015
  • December 2014
  • November 2014
  • September 2014
  • August 2014
  • March 2014
  • February 2014
  • December 2013
  • November 2013
  • October 2013
  • August 2013
  • July 2013
  • June 2013
  • May 2013
  • February 2013
  • January 2013

About Us


Serving St. Louis, the Metro-East and Southwestern Illinois since 1924.

Knowledge Center

  • New Rules Could Increase Taxable Income for GamblersAugust 24, 2026 - 3:20 pm
  • IRS Notice CP53E and the Rise of Refund-Related ScamsMay 18, 2026 - 9:55 am
  • Potential Refund Deadline Extensions Under the Kwong CaseMay 7, 2026 - 11:40 am

Quick Links

  • Services
  • Clients & Industries
  • Our Team
  • Scheffel Boyle News
  • Careers

 Contact Us

Alton, IL: 618.465.4288
Edwardsville, IL: 618.656.1206
Belleville, IL: 618.277.8100
Highland, IL: 618.654.9895
Jerseyville, IL: 618.498.6841
Columbia, IL: 618.281.7605
Carrollton, IL: 217.942.3821

© Copyright 2021 Scheffel Boyle — All rights reserved
  • Site Map
  • Privacy Policy
Scroll to top Scroll to top Scroll to top