Loading
Scheffel Boyle
  • Home
  • About Us
    • Our Team
    • Our Values
    • Scheffel Boyle News
    • Professional Affiliations
    • Client Testimonials
    • Peer Review
    • Scheffel Boyle Shares
    • BDO Alliance USA
  • Services
    • Tax Planning & Preparation
    • Audit & Assurance
    • Accounting Services
    • Consulting Services
    • Financial Advisory
  • Clients & Industries
    • Construction
    • Financial Institutions
    • Agribusiness
    • Governmental Entities
    • Non-Profit Organizations
    • Privately-Held Businesses
    • Individual Clients
    • Employee Benefit Plans
  • Resources
    • Knowledge Center
    • Coronavirus Resource Center
    • Helpful Links
  • Careers
    • Benefits
    • Available Opportunities
    • College Students
  • Contact Us
    • Locations
      • Alton, IL
      • Belleville, IL
      • Carrollton, IL
      • Columbia, IL
      • Edwardsville, IL
      • Highland, IL
      • Jerseyville, IL
  • Click to open the search input field Click to open the search input field Search
  • Menu Menu
  • Link to Facebook
  • Link to LinkedIn

Beware of Tax Traps When Making an Employee a Partner

May 31, 2018
In today’s competitive employment market, offering an employee an equity interest in your business can be a powerful tool for attracting and retaining top talent. If your company is organized as a partnership, however, beware of the tax traps of doing so.

Employees pay half of the Social Security and Medicare taxes on their wages, through withholdings from their paychecks. The employer pays the other half. Partners, on the other hand, are treated as being self-employed — they pay the full amount of “self-employment” taxes through quarterly estimates.

Often, when employees receive partnership interests, the partnership incorrectly continues to treat them as employees for tax purposes, withholding employment taxes from their wages and paying the employer’s share. The problem with this practice is that, because a partner is responsible for the full amount of employment taxes, the partnership’s payment of a portion of those taxes could be treated as a guaranteed payment to the partner.

That payment would then be included in income and trigger additional employment taxes. Any employment taxes not paid by the partnership on a partner’s behalf are the partner’s responsibility.

Treating a partner as an employee can also result in overpayment of employment taxes. Suppose your partnership pays half of a partner’s employment taxes and the partner also has other self-employment activities — for example, interests in other partnerships or sole proprietorships. If those activities generate losses, the losses will offset the partner’s earnings from your partnership, reducing or even eliminating self-employment taxes.

As you can see, there’s much to consider. Please contact us before making this move.

Copyright © 2018

https://scheffelboyle.com/wp-content/uploads/2018/05/to-sign-a-contract-3-1236622.jpg 1066 1599 brett@bonniburns.com https://scheffelboyle.com/wp-content/uploads/2022/06/Transparent-Logo-5.png brett@bonniburns.com2018-05-31 10:25:072018-06-01 13:30:38Beware of Tax Traps When Making an Employee a Partner

Three Common Types of IRS Tax Penalties

May 31, 2018
Around this time of year, many people have filed and forgotten about their 2017 tax returns. But you could get an abrupt reminder in the form of an IRS penalty. Here are three common types and how you might seek relief:

1.     Failure-to-file and failure-to-pay. The IRS will consider any reason that establishes that you were unable to meet your federal tax obligations despite using “all ordinary business care and prudence” to do so. Frequently cited reasons include fire, casualty, natural disaster or other disturbances. The agency may also accept death, serious illness, incapacitation or unavoidable absence of the taxpayer or an immediate family member.

If you don’t have a good reason for filing or paying late, you may be able to apply for a first-time penalty abatement (FTA) waiver. To qualify for relief, you must have: 1) received no penalties (other than estimated tax penalties) for the three tax years preceding the tax year in which you received a penalty, 2) filed all required returns or filed a valid extension of time to file, and 3) paid, or arranged to pay, any tax due. Despite the expression “first-time,” you can receive FTA relief more than once, so long as at least three years have elapsed.

2.     Estimated tax miscalculation. It’s possible, but unlikely, to obtain relief from estimated tax penalties on grounds of casualty, disaster or other unusual circumstances. You’re more likely to get these penalties abated if you can prove that the IRS made an error, such as crediting a payment to the wrong tax period, or that calculating the penalty using a different method (such as the annualized income installment method) would reduce or eliminate the penalty.

3.     Tax-filing inaccuracy. These penalties may be imposed, for example, if the IRS finds that your return was prepared negligently or that there’s a substantial understatement of tax. You can obtain relief from these penalties if you can demonstrate that you properly disclosed your tax position in your return and that you had a reasonable basis for taking that position.

Generally, you have a reasonable basis if your chances of withstanding an IRS challenge are greater than 50%. Reliance on a competent tax advisor greatly improves your odds of obtaining penalty relief. Other possible grounds for relief include computational errors and reliance on an inaccurate W-2, 1099 or other information statement.

Copyright © 2018

https://scheffelboyle.com/wp-content/uploads/2018/05/IRS.jpg 166 250 brett@bonniburns.com https://scheffelboyle.com/wp-content/uploads/2022/06/Transparent-Logo-5.png brett@bonniburns.com2018-05-31 10:24:072018-07-31 10:29:24Three Common Types of IRS Tax Penalties

Deducting Home Equity Interest Under the Tax Cuts and Jobs Act

May 30, 2018
Passage of the Tax Cuts and Jobs Act (TCJA) in December 2017 has led to confusion over some longstanding deductions. In response, the IRS recently issued a statement clarifying that the interest on home equity loans, home equity lines of credit and second mortgages will, in many cases, remain deductible.


How it used to be

Under prior tax law, a taxpayer could deduct “qualified residence interest” on a loan of up to $1 million secured by a qualified residence, plus interest on a home equity loan (other than debt used to acquire a home) up to $100,000. The home equity debt couldn’t exceed the fair market value of the home reduced by the debt used to acquire the home.

For tax purposes, a qualified residence is the taxpayer’s principal residence and a second residence, which can be a house, condominium, cooperative, mobile home, house trailer or boat. The principal residence is where the taxpayer resides most of the time; the second residence is any other residence the taxpayer owns and treats as a second home. Taxpayers aren’t required to use the second home during the year to claim the deduction. If the second home is rented to others, though, the taxpayer also must use it as a home during the year for the greater of 14 days or 10% of the number of days it’s rented.

In the past, interest on qualifying home equity debt was deductible regardless of how the loan proceeds were used. A taxpayer could, for example, use the proceeds to pay for medical bills, tuition, vacations, vehicles and other personal expenses and still claim the itemized interest deduction.

What’s deductible now

The TCJA limits the amount of the mortgage interest deduction for taxpayers who itemize through 2025. Beginning in 2018, for new home purchases, a taxpayer can deduct interest only on acquisition mortgage debt of $750,000.

On February 21, the IRS issued a release (IR 2018-32) explaining that the law suspends the deduction only for interest on home equity loans and lines of credit that aren’t used to buy, build or substantially improve the taxpayer’s home that secures the loan. In other words, the interest isn’t deductible if the loan proceeds are used for certain personal expenses, but it is deductible if the proceeds go toward, for example, a new roof on the home that secures the loan. The IRS further stated that the deduction limits apply to the combined amount of mortgage and home equity acquisition loans — home equity debt is no longer capped at $100,000 for purposes of the deduction.

Further clarifications

As a relatively comprehensive new tax law, the TCJA will likely be subject to a variety of clarifications before it settles in. Please contact us for help better understanding this provision or any other.

Copyright © 2018

https://scheffelboyle.com/wp-content/uploads/2018/05/equity-interest.jpg 166 250 brett@bonniburns.com https://scheffelboyle.com/wp-content/uploads/2022/06/Transparent-Logo-5.png brett@bonniburns.com2018-05-30 10:23:122018-07-31 10:29:29Deducting Home Equity Interest Under the Tax Cuts and Jobs Act

How to be Tax-Smart When it Comes to Mutual Funds

May 29, 2018
Mutual funds are so common these days that many people overlook the tax considerations involved. Here are some tips on how to be tax-smart with these investment vehicles.


Avoid year-end investments

Typically, mutual funds distribute accumulated dividends and capital gains toward the end of the year. It’s generally wise to avoid investing in a fund shortly before such a distribution. Why? Because you’ll end up paying taxes on gains you didn’t share in.

Don’t fall for the common misconception that investing in a fund just before a distribution date is like getting “free money.” True, you’ll receive a year’s worth of income right after you invest, but the value of your shares will immediately drop by the same amount, so you won’t be any better off. Plus, you’ll be liable for taxes on the distribution as if you had owned your shares all year.

You can get a general idea of when a fund anticipates making a distribution by checking its website periodically. It’s also important to make a note of the “record date” — because investors who own shares of the fund on that date participate in the distribution.

Invest in tax-efficient funds

When it comes to tax efficiency, not all funds are created equal. Actively managed funds tend to be less tax efficient — that is, they buy and sell securities more frequently, generating a greater amount of capital gains, much of it short-term gains taxable at ordinary-income rates. To reduce your tax liability, consider investing in tax-efficient funds, such as index funds, which generally have lower turnover rates, and “passively managed” funds (sometimes described as “tax managed” funds), which are designed to minimize taxable distributions.

Another option is exchange-traded funds (ETFs). Unlike mutual funds, which generally redeem shares by selling securities, ETFs are often able to redeem securities “in kind” — that is, to swap them for other securities. This limits an ETF’s recognition of capital gains, making it more tax efficient.

But don’t ignore tax-inefficient funds

Tax-inefficient funds may have a place in your portfolio. In some cases, actively managed funds may offer benefits, such as above-market returns, that outweigh their tax costs.

If you invest in actively managed or other tax-inefficient funds, ideally you should hold them in nontaxable accounts, such as traditional IRAs or 401(k) plan accounts. Because earnings in these accounts are tax-deferred, distributions from funds they hold won’t have any tax consequences until you withdraw them. And if the funds are held in a Roth account, qualifying distributions will escape taxation altogether.

Make no assumptions

It’s important to do your due diligence on mutual funds. Don’t assume that a fund that historically has been tax efficient will stay that way in the future. Feel free to contact us for help.


Sidebar: Reinvested distributions can lead to double taxation

Many investors elect to have their distributions automatically reinvested in their mutual funds. But it’s important to remember that those distributions are taxable regardless of whether they’re reinvested or paid out in cash.

Reinvested distributions increase your cost basis in a fund, so it’s critical to track your basis carefully to avoid double taxation. If you fail to account for these distributions, you could end up paying tax on them twice — once when they’re paid and again when you sell your shares in the fund.
Copyright © 2018

https://scheffelboyle.com/wp-content/uploads/2018/05/mutual-funds.jpg 167 250 brett@bonniburns.com https://scheffelboyle.com/wp-content/uploads/2022/06/Transparent-Logo-5.png brett@bonniburns.com2018-05-29 10:18:102018-07-31 10:29:33How to be Tax-Smart When it Comes to Mutual Funds
Elderly Couple

When an Elderly Parent Might Qualify as Your Dependent

May 28, 2018

It’s not uncommon for adult children to help support their aging parents. If you’re in this position, you might qualify for an adult-dependent exemption to deduct up to $4,050 for each person claimed on your 2017 return.

Basic Qualifications

For you to qualify for the adult-dependent exemption, in most cases your parent must have less gross income for the tax year than the exemption amount. (Exceptions may apply if your parent is permanently and totally disabled.) Social Security is generally excluded, but payments from dividends, interest and retirement plans are included.

In addition, you must have contributed more than 50% of your parent’s financial support. If you shared caregiving duties with one or more siblings and your combined support exceeded 50%, the exemption can be claimed even though no one individually provided more than 50%. However, only one of you can claim the exemption in this situation.

Important Factors

Although Social Security payments can usually be excluded from the adult dependent’s income, they can still affect your ability to qualify. Why? If your parent is using Social Security money to pay for medicine or other expenses, you may find that you aren’t meeting the 50% test.

Also, if your parent lives with you, the amount of support you claim under the 50% test can include the fair market rental value of part of your residence. If the parent lives elsewhere — in his or her own residence or in an assisted-living facility or nursing home — any amount of financial support you contribute to that housing expense counts toward the 50% test.

Easing the Burden

An adult-dependent exemption is just one tax break that you may be able to employ on your 2017 tax return to ease the burden of caring for an elderly parent. Contact us for more information on qualifying for this break or others.

Copyright © 2018

https://scheffelboyle.com/wp-content/uploads/2018/02/Elderly-Couple.jpeg 360 640 jordan@bonniburns.com https://scheffelboyle.com/wp-content/uploads/2022/06/Transparent-Logo-5.png jordan@bonniburns.com2018-05-28 07:55:052018-07-31 10:29:39When an Elderly Parent Might Qualify as Your Dependent

Foreign Accounts Call for Specific Reporting Requirements

May 4, 2018
In an increasingly globalized society, many people choose to open offshore accounts to deposit a portion of their wealth. When doing so, it’s important to follow the IRS’s strict foreign accounts reporting requirements. In a nutshell, if you have a financial interest in or signature authority over any foreign accounts, including bank accounts, brokerage accounts, mutual funds or trusts, you must disclose those accounts to the IRS and you may have additional reporting requirements.

To do so, your tax preparer will check the box on line 7a of Schedule B (“Interest and Ordinary Dividends”) of Form 1040 — regardless of the account value. If the total value of your foreign financial assets exceeds $50,000 ($100,000 for joint filers) at the end of the tax year or exceeds $75,000 ($150,000 for joint filers) at any time during the tax year, you must provide account details on Form 8938 (“Statement of Specified Foreign Financial Assets”) and attach it to your tax return.

Finally, if the aggregate value of your foreign accounts is $10,000 or more during the calendar year, file FinCEN (Financial Crimes Enforcement Network) Form 114 — “Report of Foreign Bank and Financial Accounts (FBAR).” The current deadline for filing the form electronically with FinCEN is April 15, 2018, with an automatic extension to October 15.

Failure to disclose an offshore account could result in substantial IRS penalties, including collecting three to six years’ worth of back taxes, interest, a 20% to 40% accuracy-related penalty and, in some cases, a 75% fraud penalty. For further information, contact us.

Copyright © 2018

https://scheffelboyle.com/wp-content/uploads/2018/05/TBAmay18_4.jpg 378 250 brett@bonniburns.com https://scheffelboyle.com/wp-content/uploads/2022/06/Transparent-Logo-5.png brett@bonniburns.com2018-05-04 10:05:092018-05-04 11:00:36Foreign Accounts Call for Specific Reporting Requirements

Scheffel Boyle Ranks #14 on St. Louis’ Largest Accounting Firms Lists

May 4, 2018

The St. Louis Business Journal recently released its annual Largest Accounting Firms lists and ranked Scheffel Boyle as the 14th largest firm in the entire St. Louis region. The Journal publishes two lists for ranking CPA firms each year: one based on number of CPAs and the other on number of professionals. Scheffel Boyle ranked #14 on both lists this year.

Click here to view St. Louis’ largest accounting firms ranked by CPAs.

Click here to view St. Louis’ largest accounting firms ranked by professionals.

https://scheffelboyle.com/wp-content/uploads/2018/05/st-louis-arch-2-1231636.jpg 1190 892 brett@bonniburns.com https://scheffelboyle.com/wp-content/uploads/2022/06/Transparent-Logo-5.png brett@bonniburns.com2018-05-04 08:51:402018-05-04 08:51:54Scheffel Boyle Ranks #14 on St. Louis’ Largest Accounting Firms Lists

Get an Early Tax “Refund” by Adjusting Your Withholding

May 3, 2018
Each year, millions of taxpayers claim an income tax refund. To be sure, receiving a payment from the IRS for a few thousand dollars can be a pleasant influx of cash. But it means you were essentially giving the government an interest-free loan for close to a year, which isn’t the best use of your money.

Fortunately, there’s a way to begin collecting your 2018 refund now: You can review the amounts you’re having withheld and/or what estimated tax payments you’re making, and adjust them to keep more money in your pocket during the year.

Choosing to adjust

It’s particularly important to check your withholding and/or estimated tax payments if:

·      You received an especially large 2017 refund,

·      You’ve gotten married or divorced or added a dependent,

·      You’ve bought a home,

·      You’ve started or lost a job, or

·      Your investment income has changed significantly.

Even if you haven’t encountered any major life changes during the past year, changes in the tax law may affect withholding levels, making it worthwhile to double-check your withholding or estimated tax payments.

Making a change

You can modify your withholding at any time during the year, or even more than once within a year. To do so, you simply submit a new Form W-4 to your employer. Changes typically will go into effect several weeks after the new Form W-4 is submitted. For estimated tax payments, you can make adjustments each time quarterly payments are due.

While reducing withholdings or estimated tax payments will, indeed, put more money in your pocket now, you also need to be careful that you don’t reduce them too much. If you don’t pay enough tax throughout the year on a timely basis, you could end up owing interest and penalties when you file your return, even if you pay your outstanding tax liability by the April 2019 deadline.

Getting help

One timely reason to consider adjusting your withholding is the passage of the Tax Cuts and Jobs Act late last year. In fact, the IRS had to revise its withholding tables to account for the increase to the standard deduction, suspension of personal exemptions, and changes in tax rates and brackets. If you’d like help determining what your withholding or estimated tax payments should be for the rest of the year, please contact us.

Copyright © 2018

https://scheffelboyle.com/wp-content/uploads/2018/05/calendar.jpg 1200 1600 brett@bonniburns.com https://scheffelboyle.com/wp-content/uploads/2022/06/Transparent-Logo-5.png brett@bonniburns.com2018-05-03 10:02:182018-07-31 10:29:47Get an Early Tax “Refund” by Adjusting Your Withholding

Choosing Between a Calendar Tax Year and a Fiscal Tax Year

May 2, 2018
Many business owners use a calendar year as their company’s tax year. It’s intuitive and aligns with most owners’ personal returns, making it about as simple as anything involving taxes can be. But for some businesses, choosing a fiscal tax year can make more sense.


What’s a fiscal tax year?

A fiscal tax year consists of 12 consecutive months that don’t begin on January 1 or end on December 31 — for example, July 1 through June 30. The year doesn’t necessarily need to end on the last day of a month. It might end on the same day each year, such as the last Friday in March. (This is known as a 52- or 53-week year.)

Flow-through entities (partnerships, S corporations and, typically, limited liability companies) using a fiscal tax year must file their returns by the 15th day of the third month following the close of their fiscal year. So, if their fiscal year ends on March 31, they need to file their returns by June 15. (Fiscal-year C corporations generally must file their returns by the 15th day of the fourth month following the fiscal year close.)

When does it make sense?

A key factor to consider is that, if you adopt a fiscal tax year, you must use the same period in maintaining your books and reporting income and expenses. For many seasonal businesses, a fiscal year can present a more accurate picture of the company’s performance.

For example, a snowplowing business might make the bulk of its revenue between November and March. Splitting the revenue between December and January to adhere to a calendar year end would make obtaining a solid picture of performance over a single season difficult.

In addition, if many businesses within your industry use a fiscal year end and you want to compare your performance to that of your peers, you’ll probably achieve a more accurate comparison if you’re using the same fiscal year.

Before deciding to change your fiscal year, be aware that the IRS requires businesses that don’t keep books and have no annual accounting period, as well as most sole proprietorships, to use a calendar year.

Does it matter?

If your company decides to change its tax year, you’ll need to obtain permission from the IRS. The change also will likely create a one-time “short tax year” — a tax year that’s less than 12 months. In this case, your income tax typically will be based on annualized income and expenses. But you might be able to use a relief procedure under Section 443(b)(2) of the Internal Revenue Code to reduce your tax bill.

Although choosing a tax year may seem like a minor administrative matter, it can have an impact on how and when a company pays taxes. We can help you determine whether a calendar or fiscal year makes more sense for your business. Please contact us for specific questions and consultation.

Copyright © 2018

https://scheffelboyle.com/wp-content/uploads/2018/05/TBAmay18_2.jpg 200 250 brett@bonniburns.com https://scheffelboyle.com/wp-content/uploads/2022/06/Transparent-Logo-5.png brett@bonniburns.com2018-05-02 09:45:012018-07-31 10:29:53Choosing Between a Calendar Tax Year and a Fiscal Tax Year

Bowl for Kids’ Sake was a HUGE Success!

May 2, 2018

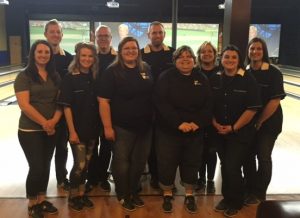
Our amazing employees have, once again, outdone themselves. Our Bowl for Kids’ Sake volunteers raised an outstanding $6,100 to support the programs and overall mission of Big Brothers Big Sisters of Southwestern Illinois.

A big shout-out goes to our bowlers for their tenacious and dedicated attitude toward fundraising for this event. They really do go above and beyond every year for this fundraiser. And to all those who donated to this great, local cause, we appreciate your support!

The Tax-Manian Devils and the Ten-Key Strikers

Sarah Kinkead, Chad Frerichs, Carrie Evans, Michael Brokering, Maggie Stock, Josh Andres, Elizabeth Heil, Sarah Wells (subbing for Sarah Smith), Crystal Bock, and Jenna Andres

https://scheffelboyle.com/wp-content/uploads/2018/05/IMG_6748.jpg 401 552 brett@bonniburns.com https://scheffelboyle.com/wp-content/uploads/2022/06/Transparent-Logo-5.png brett@bonniburns.com2018-05-02 09:01:142018-05-04 08:19:39Bowl for Kids’ Sake was a HUGE Success!
Page 1 of 212

Pages

  • 2025 Seminar Registration
  • 2025 Seminar Registration Presentation Slides
  • 2026 Summer Sneak Peek
  • About Us
  • Accounting and Office Manager
  • Accounting Clerk
  • Accounting Services
  • Administrative Assistant
  • Administrative Assistant – Columbia Office
  • Administrative Assistant – Edwardsville Office
  • Administrative Support Specialist
  • Administrative Support Specialist
  • AGCI Webinar Presentation
  • Agribusiness
  • Alton, IL
  • Andrea Suhre
  • Andrea Suhre
  • Audit & Assurance
  • Available Opportunities
  • BDO Alliance USA
  • Belleville, IL
  • Bookkeeper
  • Bookkeeper/Payroll Specialist
  • Brian Otten
  • Business Valuations
  • Careers
  • Carrollton, IL
  • Columbia, IL
  • Construction Accounting
  • Construction Newsletter
  • Construction Tax Seminar Presentation
  • Consulting Services
  • Contact Us
  • Coronavirus Resource Center
  • Cory E. Gallivan
  • Crystal Bock
  • Crystal Bock
  • Dale Holtmann
  • Daniel Phipps
  • Data Entry Assistants
  • Dennis E. Ulrich
  • E-News Sign Up
  • Edwardsville, IL
  • Elements
  • Employee Benefit Plans
  • Experienced Accountants
  • Experienced Public Accountant
  • Financial Calculators
  • Financial Institution
  • FOCUS Internship Program
  • Full-Time Interview Sign-Up
  • George Moore
  • Governmental Entities
  • Heather Clugston
  • Helpful Links
  • Highland, IL
  • Home
  • Howard Held
  • Individual Clients
  • Industries
  • Interview Thank You
  • Interview Timeslots
  • IT Support Specialist
  • Jerseyville, IL
  • Julie Billeter
  • Julie Graham
  • Kathy Fitzgerald
  • Keith Brinkmann
  • Knowledge Center
  • Lisa Bohnenstiehl
  • Locations
  • Mark Korte
  • Marketing Specialist
  • Michael D. Ulrich
  • Michael E. Fitzgerald
  • Michael T. Brokering
  • Non-Profit Organizations
  • Office Accounting Assistant
  • Our Team
  • Outsourced Accountant
  • Part-Time Bookkeeper
  • Payroll Assistant
  • Payroll Supervisor
  • Peer Review
  • Privacy Policy
  • Privately-Held Businesses
  • Professional Affiliations
  • Recruiting Events
  • Recruiting/Human Resources Coordinator
  • Resources
  • Robyn M. Klingler
  • Russell Gregson
  • Sarah Smith
  • Scheffel Boyle News
  • Scheffel Boyle Shares
  • Scott Weber
  • Seasonal Tax Preparer
  • Services
  • SIBA Webinar Presentation
  • Sneak Peek Survey
  • Spring Tax Internship Program 2026
  • STL Ag Club Webinar Prez
  • Summer Audit Internship Program
  • Summer Audit Internship Program 2026
  • Tax Planning & Preparation
  • Tax Talks Information
  • Tax Talks Presentation
  • Testimonials
  • Webinar Presentation May 14
  • Welcome Email
  • Year-End Tax Planning Seminars
  • Accountant – Carrollton
  • Administrative Assistant – Alton Office
  • Administrative Assistant – Belleville Office
  • Administrative Assistant – Columbia Office
  • Seasonal Administrative Assistants
  • Seasonal Data Input
  • Staff Accountant

Categories

  • Blog
  • Construction
  • Coronavirus Resource Center
  • Frontpage
  • Knowledge Center
  • Scheffel News
  • Uncategorized

Archive

  • August 2026
  • May 2026
  • November 2025
  • October 2025
  • July 2025
  • February 2024
  • July 2023
  • May 2023
  • February 2023
  • January 2023
  • November 2022
  • August 2022
  • July 2022
  • June 2022
  • March 2022
  • February 2022
  • January 2022
  • December 2021
  • June 2021
  • May 2021
  • April 2021
  • March 2021
  • February 2021
  • January 2021
  • December 2020
  • November 2020
  • October 2020
  • September 2020
  • August 2020
  • July 2020
  • June 2020
  • May 2020
  • April 2020
  • March 2020
  • February 2020
  • January 2020
  • December 2019
  • November 2019
  • October 2019
  • September 2019
  • August 2019
  • July 2019
  • June 2019
  • May 2019
  • April 2019
  • March 2019
  • February 2019
  • January 2019
  • December 2018
  • November 2018
  • October 2018
  • September 2018
  • August 2018
  • July 2018
  • June 2018
  • May 2018
  • April 2018
  • March 2018
  • February 2018
  • January 2018
  • December 2017
  • November 2017
  • October 2017
  • September 2017
  • August 2017
  • July 2017
  • June 2017
  • May 2017
  • April 2017
  • March 2017
  • February 2017
  • January 2017
  • December 2016
  • October 2016
  • September 2016
  • August 2016
  • July 2016
  • May 2016
  • April 2016
  • March 2016
  • February 2016
  • January 2016
  • December 2015
  • November 2015
  • August 2015
  • July 2015
  • June 2015
  • February 2015
  • January 2015
  • December 2014
  • November 2014
  • September 2014
  • August 2014
  • March 2014
  • February 2014
  • December 2013
  • November 2013
  • October 2013
  • August 2013
  • July 2013
  • June 2013
  • May 2013
  • February 2013
  • January 2013

About Us


Serving St. Louis, the Metro-East and Southwestern Illinois since 1924.

Knowledge Center

  • New Rules Could Increase Taxable Income for GamblersAugust 24, 2026 - 3:20 pm
  • IRS Notice CP53E and the Rise of Refund-Related ScamsMay 18, 2026 - 9:55 am
  • Potential Refund Deadline Extensions Under the Kwong CaseMay 7, 2026 - 11:40 am

Quick Links

  • Services
  • Clients & Industries
  • Our Team
  • Scheffel Boyle News
  • Careers

 Contact Us

Alton, IL: 618.465.4288
Edwardsville, IL: 618.656.1206
Belleville, IL: 618.277.8100
Highland, IL: 618.654.9895
Jerseyville, IL: 618.498.6841
Columbia, IL: 618.281.7605
Carrollton, IL: 217.942.3821

© Copyright 2021 Scheffel Boyle — All rights reserved
  • Site Map
  • Privacy Policy
Scroll to top Scroll to top Scroll to top