Loading
Scheffel Boyle
  • Home
  • About Us
    • Our Team
    • Our Values
    • Scheffel Boyle News
    • Professional Affiliations
    • Client Testimonials
    • Peer Review
    • Scheffel Boyle Shares
    • BDO Alliance USA
  • Services
    • Tax Planning & Preparation
    • Audit & Assurance
    • Accounting Services
    • Consulting Services
    • Financial Advisory
  • Clients & Industries
    • Construction
    • Financial Institutions
    • Agribusiness
    • Governmental Entities
    • Non-Profit Organizations
    • Privately-Held Businesses
    • Individual Clients
    • Employee Benefit Plans
  • Resources
    • Knowledge Center
    • Coronavirus Resource Center
    • Helpful Links
  • Careers
    • Benefits
    • Available Opportunities
    • College Students
  • Contact Us
    • Locations
      • Alton, IL
      • Belleville, IL
      • Carrollton, IL
      • Columbia, IL
      • Edwardsville, IL
      • Highland, IL
      • Jerseyville, IL
  • Click to open the search input field Click to open the search input field Search
  • Menu Menu
  • Link to Facebook
  • Link to LinkedIn

Mark Your Calendar for Upcoming Tax Deadlines!

June 27, 2019
July 15 — If the monthly deposit rule applies, employers must deposit the tax for payments in June for Social Security, Medicare, withheld income tax and nonpayroll withholding.

July 31 — If you have employees, a federal unemployment tax (FUTA) deposit is due if the FUTA liability through June exceeds $500.

  • The second quarter Form 941 (“Employer’s Quarterly Federal Tax Return”) is also due today. (If your tax liability is less than $2,500, you can pay it in full with a timely filed return.) If you deposited the tax for the quarter in full and on time, you have until August 12 to file the return.

August 15 — If the monthly deposit rule applies, employers must deposit the tax for payments in July for Social Security, Medicare, withheld income tax and nonpayroll withholding.

September 16 — Third quarter estimated tax payments are due for individuals, trusts and calendar-year corporations.

  • If a six-month extension was obtained, partnerships should file their 2018 Form 1065 by this date.
  • If a six-month extension was obtained, calendar-year S corporations should file their 2018 Form 1120S by this date.
  • If the monthly deposit rule applies, employers must deposit the tax for payments in August for Social Security, Medicare, withheld income tax and nonpayroll withholding.

September 30 — Calendar year trusts and estates on extension must file their 2018 Form 1041.

Copyright © 2019

https://scheffelboyle.com/wp-content/uploads/2019/06/pexels-photo-273011.jpeg 1500 2000 brett@bonniburns.com https://scheffelboyle.com/wp-content/uploads/2022/06/Transparent-Logo-5.png brett@bonniburns.com2019-06-27 08:56:172019-07-02 14:31:25Mark Your Calendar for Upcoming Tax Deadlines!

Scheffel Boyle Climbs Higher on the Biz Journal Annual List

June 26, 2019

We are excited to share that we have climbed in the rankings on the St. Louis Business Journal’s annual Largest Accounting Firms lists. The Journal publishes two lists for ranking CPA firms each year: one based on number of CPAs and the other on number of professionals. Coming in at 14th on both lists last year, we are now ranked as the 13th largest by number of CPAs and the 12th largest by number of professionals in the entire St. Louis region.

Thank you to our clients, employees, and community partners for all they’ve done to help us grow and continue serving the St. Louis and Metro regions.

Click here to view St. Louis’ largest accounting firms ranked by CPAs.

Click here to view St. Louis’ largest accounting firms ranked by professionals.

https://scheffelboyle.com/wp-content/uploads/2019/06/Climbing-the-List.png 788 940 brett@bonniburns.com https://scheffelboyle.com/wp-content/uploads/2022/06/Transparent-Logo-5.png brett@bonniburns.com2019-06-26 10:27:162019-07-02 14:33:36Scheffel Boyle Climbs Higher on the Biz Journal Annual List

Could an FLP Help Your Business Succession Plan?

June 25, 2019
One of the biggest concerns for business owners is succession planning — transferring ownership and control of the company to the next generation. Often, the best time taxwise to start transferring ownership is long before the owner is ready to give up control of the business.

A family limited partnership (FLP) can help owners enjoy the tax benefits of gradually transferring ownership yet allow them to retain control of the business.

How it Works

To establish an FLP, you transfer your ownership interests to a partnership in exchange for both general and limited partnership interests. You then transfer limited partnership interests to your children or other beneficiaries.

You retain the general partnership interest, which may be as little as 1% of the assets. But as general partner, you can still run day-to-day operations and make business decisions.

Tax Benefits

As you transfer the FLP interests, their value is removed from your taxable estate. What’s more, the future business income and asset appreciation associated with those interests move to the next generation.

Because your children hold limited partnership interests, they have no control over the FLP, and thus no control over the business. They also can’t sell their interests without your consent or force the FLP’s liquidation.

The lack of control and lack of an outside market for the FLP interests generally mean the interests can be valued at a discount — so greater portions of the business can be transferred before triggering gift tax. For example, if the discount is 25%, in 2019 you could gift an FLP interest equal to as much as $20,000 tax-free because the discounted value wouldn’t exceed the $15,000 annual gift tax exclusion.

There also may be income tax benefits. The FLP’s income will flow through to the partners for income tax purposes. Your children may be in a lower tax bracket, potentially reducing the amount of income tax paid overall by the family.

Some Risks

Perhaps the biggest downside is that the IRS scrutinizes FLPs. If it determines that discounts were excessive or that your FLP had no valid business purpose beyond minimizing taxes, it could assess additional taxes, interest and penalties.

The IRS pays close attention to how FLPs are administered. Lack of attention to partnership formalities, for example, can indicate that an FLP was set up solely as a tax-avoidance strategy.

Not for Everyone

An FLP can be an effective succession and estate planning tool but, as we’ve taken pains to explain, it’s far from risk free. Please contact us for help determining whether an FLP is right for you.

Copyright © 2019

https://scheffelboyle.com/wp-content/uploads/2019/06/pexels-photo-1496186.jpeg 1500 2250 brett@bonniburns.com https://scheffelboyle.com/wp-content/uploads/2022/06/Transparent-Logo-5.png brett@bonniburns.com2019-06-25 16:22:372020-01-28 15:23:51Could an FLP Help Your Business Succession Plan?

Be Ready for Anything With Regular Business Valuations

June 20, 2019
Do you know the current value of your business? Even if you’re not considering selling your company or otherwise transferring its ownership right now, it could happen sooner than you think.

In some cases, an ownership transfer becomes suddenly appealing when a company struggles to the extent that a sale becomes the best avenue for starting over. But more positive circumstances can drive the decision, too. For example, a small to midsize business might do so well that it receives an acquisition offer that’s too good to pass up.

Whether it’s an impending ownership transfer, or just a need to learn more about your company, it’s important to establish reasonable expectations of what a valuation provides.

Answering the Right Questions

Some owners mistakenly believe that the balance sheet tells how much a company is worth. But most businesses possess goodwill and other intangible assets — as well as unreported liabilities — that don’t show up on the financial statements.

In truth, cost-based valuation metrics aren’t often used in real-world transactions. Instead, the most popular methods for valuing private businesses include the discounted cash earnings, guideline company transactions and capitalization of earnings techniques. Calculating value under these methods requires the expertise of an outside valuation professional.

To better understand the valuation process, answer these basic questions:

What’s the purpose? It could be as clear-cut as an impending sale. Or perhaps a divorce is on the horizon, and the owner must determine the value of the business interest that’s includable in the marital estate. In other cases, the valuation may be driven by tax, estate or strategic planning.

What’s the appropriate standard of value? Generally, business valuations estimate “fair market value” — the price at which property would change hands in a hypothetical transaction involving informed buyers and sellers not under duress to buy or sell. But some assignments call for a different standard of value.

For instance, say you’re contemplating selling to a competitor. In this case, you might be best off determining the “strategic value” of your company — that is, the value to a particular investor, including buyer-specific synergies.

What’s the appropriate basis of value? There’s a hierarchy of different types of value based on the degree of control and marketability an interest carries. Investors place premiums on the abilities to 1) control business decisions and 2) sell the interest on the “market” as quickly and inexpensively as possible.

Digging Deeper

Defining the appropriate basis of value in a business valuation isn’t always straightforward. Suppose a business is split equally between two partners. Even though each owner has some control, stalemates could impair decision making.

On the other hand, a 2% owner might possess some elements of control if the remaining shares are divvied up equally between two 49% owners. Definitively establishing the basis of value requires careful consideration of who owns the rest of the business — and how that allocation affects value given applicable state laws and ownership agreements.

Getting it Done Right

Regular valuations can be an important management tool — particularly if you plan to sell or transfer your interest anytime soon. We can explain the valuation process to you further and work with an appraiser to get the job done right.

Copyright © 2019

https://scheffelboyle.com/wp-content/uploads/2019/06/pexels-photo-1509428.jpeg 1500 2297 brett@bonniburns.com https://scheffelboyle.com/wp-content/uploads/2022/06/Transparent-Logo-5.png brett@bonniburns.com2019-06-20 16:10:072020-01-28 15:24:00Be Ready for Anything With Regular Business Valuations

Estate Planning Portability Lives on Under the TCJA

June 14, 2019
When the TCJA was passed, the big estate planning news was that the federal gift and estate tax exclusion doubled from $5 million to an inflation-indexed $10 million. It was further indexed for inflation to $11.18 million for 2018 and now $11.4 million for 2019.

Somewhat lost in the clamor, however, was (and is) the fact that the new law preserves the “portability” provision for married couples. Portability allows your estate to elect to permit your surviving spouse to use any of your available estate tax exclusion that is unused at your death.

A Brief History

At the turn of this century, the exclusion was a mere $675,000 before being hiked to $1 million in 2002. By 2009, the exclusion increased to $3.5 million, while the top estate tax rate was reduced from 55% in 2000 to 35% in 2010, among other changes.

After a one-year estate tax moratorium in 2010, the Tax Relief Act (TRA) of 2010 reinstated the estate tax with a generous $5 million exclusion, indexed for inflation, and a top 35% tax rate. The American Taxpayer Relief Act (ATRA) of 2012 made these changes permanent, aside from increasing the top rate to 40%.

Most important, the TRA authorized portability of the estate tax exclusion, which was then permanently preserved by the ATRA. Under the portability provision, the executor of the estate of the first spouse to die can elect to have the “deceased spousal unused exclusion” (DSUE) transferred to the estate of the surviving spouse.

How the DSUE Works

Let’s say Kevin and Debbie, who have two children, each own $5 million individually and $10 million jointly with rights of survivorship, for a total of $20 million. Under their wills, all assets pass first to the surviving spouse and then to the children.

If Debbie had died in early 2019, the $10 million ($5 million owned individually and $5 million held jointly) in assets would be exempt from estate tax because of the unlimited marital deduction. Thus, her entire $11.4 million exclusion would remain unused. However, if the election is made upon her death, Kevin’s estate can later use the $11.4 million of the DSUE from Debbie, plus the exclusion for the year in which Kevin dies, to shelter the remaining $8.6 million from tax, with plenty to spare for some appreciation in value.

What would have happened without the portability provision? For simplicity, let’s say that Kevin dies later in 2019. Without being able to benefit from the unused portion of Debbie’s exclusion, the $11.4 million exclusion for Kevin in 2019 leaves the $8.6 million subject to estate tax. At the 40% rate, the federal estate tax bill would amount to a whopping $3.44 million.

Although techniques such as a traditional bypass trust may be used to avoid or reduce estate tax liability, this example demonstrates the potential impact of the portability election. It also emphasizes the need for planning.

Other Points of Interest

Be aware that this discussion factors in only federal estate taxes. State estate taxes may also have a significant impact, particularly in some states where the estate tax exemption isn’t tied to the federal exclusion.

Also, keep in mind that, absent further legislation, the exclusion amount is slated to revert to pre-2018 levels after 2025. Portability continues, although, for those whose estates will no longer be fully sheltered, additional planning must be considered.

Furthermore, portability isn’t always the best option. Consider all relevant factors, including nontax reasons that might affect the distribution of assets under a will or living trust. For instance, a person may want to divide assets in other ways if matters are complicated by a divorce, a second marriage, or unusual circumstances.

Details, Details

Every estate plan includes details that need to be checked and rechecked. We can help you do so, including deciding whether portability is right for you.
Copyright © 2019

https://scheffelboyle.com/wp-content/uploads/2019/06/pexels-photo-1449049.jpeg 1500 2144 brett@bonniburns.com https://scheffelboyle.com/wp-content/uploads/2022/06/Transparent-Logo-5.png brett@bonniburns.com2019-06-14 15:01:072020-01-28 15:24:06Estate Planning Portability Lives on Under the TCJA

Scheffel Boyle Employees Raise Over $5,000 for Big Brothers Big Sisters

June 13, 2019

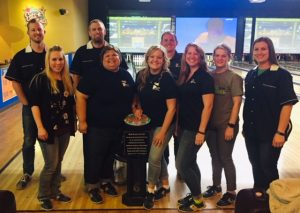
We had a great season this year for our annual Bowl for Kids’ Sake fundraiser, benefiting Big Brothers Big Sisters of Southwestern Illinois. Between our two teams, our employees raised an outstanding $5,100 to support the programs and overall mission of this wonderful, local organization.

Our bowlers go above and beyond for this event and we are so proud of all they accomplish. Thank you to everyone who supported them along the way and helped them reach their $5,000 goal.

The Tax-Manian Devils and the Ten-Key Strikers

Sarah Smith, Chad Frerichs, Elizabeth Heil, Josh Andres, Tyler Jackson, Lisa Bohnenstiehl, Marissa Dycus, and Jenna Andres

(Not pictured: Crystal Bock and Carrie Evans)

https://scheffelboyle.com/wp-content/uploads/2019/06/IMG_1462.jpg 454 640 brett@bonniburns.com https://scheffelboyle.com/wp-content/uploads/2022/06/Transparent-Logo-5.png brett@bonniburns.com2019-06-13 11:43:062019-06-13 11:44:03Scheffel Boyle Employees Raise Over $5,000 for Big Brothers Big Sisters

Pages

  • 2025 Seminar Registration
  • 2025 Seminar Registration Presentation Slides
  • 2026 Summer Sneak Peek
  • About Us
  • Accounting and Office Manager
  • Accounting Clerk
  • Accounting Services
  • Administrative Assistant
  • Administrative Assistant – Columbia Office
  • Administrative Assistant – Edwardsville Office
  • Administrative Support Specialist
  • Administrative Support Specialist
  • AGCI Webinar Presentation
  • Agribusiness
  • Alton, IL
  • Andrea Suhre
  • Andrea Suhre
  • Audit & Assurance
  • Available Opportunities
  • BDO Alliance USA
  • Belleville, IL
  • Bookkeeper
  • Bookkeeper/Payroll Specialist
  • Brian Otten
  • Business Valuations
  • Careers
  • Carrollton, IL
  • Columbia, IL
  • Construction Accounting
  • Construction Newsletter
  • Construction Tax Seminar Presentation
  • Consulting Services
  • Contact Us
  • Coronavirus Resource Center
  • Cory E. Gallivan
  • Crystal Bock
  • Crystal Bock
  • Dale Holtmann
  • Daniel Phipps
  • Data Entry Assistants
  • Dennis E. Ulrich
  • E-News Sign Up
  • Edwardsville, IL
  • Elements
  • Employee Benefit Plans
  • Experienced Accountants
  • Experienced Public Accountant
  • Financial Calculators
  • Financial Institution
  • FOCUS Internship Program
  • Full-Time Interview Sign-Up
  • George Moore
  • Governmental Entities
  • Heather Clugston
  • Helpful Links
  • Highland, IL
  • Home
  • Howard Held
  • Individual Clients
  • Industries
  • Interview Thank You
  • Interview Timeslots
  • Jerseyville, IL
  • Julie Billeter
  • Julie Graham
  • Kathy Fitzgerald
  • Keith Brinkmann
  • Knowledge Center
  • Lisa Bohnenstiehl
  • Locations
  • Mark Korte
  • Marketing Specialist
  • Michael D. Ulrich
  • Michael E. Fitzgerald
  • Michael T. Brokering
  • Non-Profit Organizations
  • Office Accounting Assistant
  • Our Team
  • Outsourced Accountant
  • Part-Time Bookkeeper
  • Payroll Assistant
  • Payroll Supervisor
  • Peer Review
  • Privacy Policy
  • Privately-Held Businesses
  • Professional Affiliations
  • Recruiting Events
  • Recruiting/Human Resources Coordinator
  • Resources
  • Robyn M. Klingler
  • Russell Gregson
  • Sarah Smith
  • Scheffel Boyle News
  • Scheffel Boyle Shares
  • Scott Weber
  • Seasonal Tax Preparer
  • Services
  • SIBA Webinar Presentation
  • Sneak Peek Survey
  • Spring Tax Internship Program 2026
  • STL Ag Club Webinar Prez
  • Summer Audit Internship Program
  • Summer Audit Internship Program 2026
  • Tax Planning & Preparation
  • Tax Talks Information
  • Tax Talks Presentation
  • Testimonials
  • Webinar Presentation May 14
  • Welcome Email
  • Year-End Tax Planning Seminars
  • Accountant – Carrollton
  • Administrative Assistant – Alton Office
  • Administrative Assistant – Belleville Office
  • Administrative Assistant – Columbia Office
  • Seasonal Administrative Assistants
  • Seasonal Data Input
  • Staff Accountant

Categories

  • Blog
  • Construction
  • Coronavirus Resource Center
  • Frontpage
  • Knowledge Center
  • Scheffel News
  • Uncategorized

Archive

  • August 2026
  • May 2026
  • November 2025
  • October 2025
  • July 2025
  • February 2024
  • July 2023
  • May 2023
  • February 2023
  • January 2023
  • November 2022
  • August 2022
  • July 2022
  • June 2022
  • March 2022
  • February 2022
  • January 2022
  • December 2021
  • June 2021
  • May 2021
  • April 2021
  • March 2021
  • February 2021
  • January 2021
  • December 2020
  • November 2020
  • October 2020
  • September 2020
  • August 2020
  • July 2020
  • June 2020
  • May 2020
  • April 2020
  • March 2020
  • February 2020
  • January 2020
  • December 2019
  • November 2019
  • October 2019
  • September 2019
  • August 2019
  • July 2019
  • June 2019
  • May 2019
  • April 2019
  • March 2019
  • February 2019
  • January 2019
  • December 2018
  • November 2018
  • October 2018
  • September 2018
  • August 2018
  • July 2018
  • June 2018
  • May 2018
  • April 2018
  • March 2018
  • February 2018
  • January 2018
  • December 2017
  • November 2017
  • October 2017
  • September 2017
  • August 2017
  • July 2017
  • June 2017
  • May 2017
  • April 2017
  • March 2017
  • February 2017
  • January 2017
  • December 2016
  • October 2016
  • September 2016
  • August 2016
  • July 2016
  • May 2016
  • April 2016
  • March 2016
  • February 2016
  • January 2016
  • December 2015
  • November 2015
  • August 2015
  • July 2015
  • June 2015
  • February 2015
  • January 2015
  • December 2014
  • November 2014
  • September 2014
  • August 2014
  • March 2014
  • February 2014
  • December 2013
  • November 2013
  • October 2013
  • August 2013
  • July 2013
  • June 2013
  • May 2013
  • February 2013
  • January 2013

About Us


Serving St. Louis, the Metro-East and Southwestern Illinois since 1924.

Knowledge Center

  • New Rules Could Increase Taxable Income for GamblersAugust 24, 2026 - 3:20 pm
  • IRS Notice CP53E and the Rise of Refund-Related ScamsMay 18, 2026 - 9:55 am
  • Potential Refund Deadline Extensions Under the Kwong CaseMay 7, 2026 - 11:40 am

Quick Links

  • Services
  • Clients & Industries
  • Our Team
  • Scheffel Boyle News
  • Careers

 Contact Us

Alton, IL: 618.465.4288
Edwardsville, IL: 618.656.1206
Belleville, IL: 618.277.8100
Highland, IL: 618.654.9895
Jerseyville, IL: 618.498.6841
Columbia, IL: 618.281.7605
Carrollton, IL: 217.942.3821

© Copyright 2021 Scheffel Boyle — All rights reserved
  • Site Map
  • Privacy Policy
Scroll to top Scroll to top Scroll to top