Loading
Scheffel Boyle
  • Home
  • About Us
    • Our Team
    • Our Values
    • Scheffel Boyle News
    • Professional Affiliations
    • Client Testimonials
    • Peer Review
    • Scheffel Boyle Shares
    • BDO Alliance USA
  • Services
    • Tax Planning & Preparation
    • Audit & Assurance
    • Accounting Services
    • Consulting Services
    • Financial Advisory
  • Clients & Industries
    • Construction
    • Financial Institutions
    • Agribusiness
    • Governmental Entities
    • Non-Profit Organizations
    • Privately-Held Businesses
    • Individual Clients
    • Employee Benefit Plans
  • Resources
    • Knowledge Center
    • Coronavirus Resource Center
    • Helpful Links
  • Careers
    • Benefits
    • Available Opportunities
    • College Students
  • Contact Us
    • Locations
      • Alton, IL
      • Belleville, IL
      • Carrollton, IL
      • Columbia, IL
      • Edwardsville, IL
      • Highland, IL
      • Jerseyville, IL
  • Click to open the search input field Click to open the search input field Search
  • Menu Menu
  • Link to Facebook
  • Link to LinkedIn

New Rules Could Increase Taxable Income for Gamblers

August 24, 2026

Recent changes to federal tax law may significantly impact how gambling losses are reported on individual income tax returns. For tax years beginning after December 31, 2025, a new limitation on gambling loss deductions could result in taxpayers owing tax on income they never actually received.

The change affects anyone who participates in sports betting, casino gaming, poker tournaments, horse racing, or other wagering activities.  These taxpayers should understand how these new rules may affect their tax liability.

How Gambling Income Was Previously Reported

Under prior tax law, gambling losses were deductible up to the amount of gambling winnings during the same tax year. In other words, taxpayers could not claim a net gambling loss, but they could generally offset all wagering gains with an equal amount of documented losses. Winnings were reported as income, while losses were claimed as an itemized deduction.

For example, if a taxpayer had $20,000 in gambling winnings and $20,000 in documented gambling losses, the losses could fully offset the winnings if the taxpayer itemized, resulting in no taxable gambling income.

What Changes in 2026?

For tax years beginning after December 31, 2025, a taxpayer’s deduction for wagering losses is limited to 90% of total losses incurred. The deduction remains subject to the existing rule that losses cannot exceed gambling winnings.

This seemingly small adjustment may create a significant tax burden for some taxpayers because a portion of their losses will no longer be deductible.

Consider the following example:

  • Gambling winnings: $50,000
  • Gambling losses: $45,000
  • Net economic gain: $5,000

Under the new rules, only 90% of the losses, or $40,500, would be deductible. This results in taxable gambling income of $9,500 rather than the taxpayer’s actual economic gain of $5,000.

In this scenario, the taxpayer pays tax on income that exceeds their true profit from gambling activity. The disallowed portion of the losses effectively increases taxable income and may substantially increase the overall tax rate on gambling profits.

The “Phantom Income” Problem

One of the most concerning aspects of the new law is the potential creation of what tax professionals often refer to as “phantom income.”

Because only 90% of gambling losses are deductible, some taxpayers could owe income tax even when their gambling activity breaks even economically. A taxpayer whose losses equal their winnings may still report taxable gambling income solely because a portion of those losses is no longer deductible.

This result has generated concern among taxpayers and tax professionals, particularly for individuals who engage in high-volume gambling activity throughout the year.

Recordkeeping Will Be More Important Than Ever

Accurate documentation has always been critical for taxpayers claiming gambling losses, but these new rules make proper recordkeeping even more important. Taxpayers should maintain contemporaneous records that clearly document both winnings and losses.

The IRS may challenge records that appear to have been recreated after the fact, especially when diaries contain numerous rounded amounts. Taxpayers should avoid estimates and instead record gambling activity as it occurs. Mobile applications and digital tracking tools may help maintain accurate records throughout the year.

Additional Planning Opportunities

Taxpayers who regularly participate in wagering activities may want to review their estimated tax payments. The new limitation could increase taxable income beyond what is expected based on actual gambling profits, potentially leading to underpayment penalties if quarterly estimates are not adjusted.

Another planning technique that may be beneficial is the “session method” of reporting gambling activity. This approach generally allows gamblers to net wins and losses within a single gaming session rather than reporting every wager independently. Proper application of the session method may help reduce the amount treated as gross gambling winnings before the 90% limitation is applied.

Final Thoughts

The new gambling loss limitation represents a significant shift in the taxation of wagering activity. While the change may appear minor on the surface, it has the potential to increase taxable income and create unexpected tax liabilities for many gamblers, including those who have little or no actual economic profit.

If you regularly participate in sports betting, casino gaming, poker, or other gambling activities, now is a good time to review your recordkeeping practices and discuss planning opportunities with your tax advisor. Understanding these changes before filing season can help you avoid surprises and ensure you remain compliant with the new reporting requirements.


If you have questions about gambling losses, estimated tax payments, or the potential impact of these changes on your return, Scheffel Boyle is here to help. Our experienced tax advisors can provide guidance tailored to your specific situation and help you stay ahead of changing tax laws.
https://scheffelboyle.com/wp-content/uploads/2026/08/Article-Cover.png 788 940 kristen.poelker@scheffelboyle.com https://scheffelboyle.com/wp-content/uploads/2022/06/Transparent-Logo-5.png kristen.poelker@scheffelboyle.com2026-08-24 15:20:192026-08-24 15:20:19New Rules Could Increase Taxable Income for Gamblers

Scheffel Boyle CPAs Ranks #11 in both of STL Business Journal’s Annual Largest Accounting Firms Lists

February 5, 2024

Scheffel Boyle has ranked #11 for number of CPAs and #11 for number of professionals on the St. Louis Business Journal’s annual Largest Accounting Firms lists.

Each year, The Journal publishes two lists for ranking CPA firms: one based on the number of CPAs and the other on the number of professionals (employees required to have continuing education hours).

Thank you to our clients, employees, and community partners for all they have done to help us grow and continue serving the St. Louis and Metro East region.

https://scheffelboyle.com/wp-content/uploads/2023/02/Biz-Journal-List-2022.png 627 1200 Suzi Seaton https://scheffelboyle.com/wp-content/uploads/2022/06/Transparent-Logo-5.png Suzi Seaton2024-02-05 08:52:492024-02-05 08:52:49Scheffel Boyle CPAs Ranks #11 in both of STL Business Journal’s Annual Largest Accounting Firms Lists

Did you receive an Identity Verification Letter?

July 11, 2023

Have you received a letter from the Illinois Department of Revenue (IDOR) asking you to verify your identity? If so, please look at the following FAQs:

1. Why is the IDOR sending me this letter?

They want to protect you and your identity. This is a safety procedure to prevent someone from using your identity to file a false tax return.


2. Why was my return selected for additional review?

When you file a tax return using your Social Security Number (SSN) or Individual Taxpayer Identification Number (ITIN), the IDOR wants to verify your information to ensure you are the individual who filed this return.


3. What should I do if I receive an Identity Verification letter?

Respond to your identity verification letter in MyTax Illinois without having to create a MyTax Illinois account. Please follow the specific instructions in your letter.


4. What should I do if I did not file this return?

  • Go to illinois.gov
  • Scroll down to the section titled: “Identity Verification.”
  • Select the Identity Verification Code
  • Select “No, I did not file this return and need to report identity theft.”
  • Enter your contact information.
  • Click Submit


5. I did not verify my identity by the due date. What should I do?

You must submit two required documents to verify your identity – one from each category listed below, within 60 days of the date of this letter.

Category 1: Submit one document that has your photograph and full name:

  • Illinois driver’s license (current or expired less than one year)
  • Driver’s license from any other state (current)
  • State identification card
  • Passport
  • Military identification
  • Government issued photo identification
  • S. high school, college, or university photo ID
  • Employee photo ID card with recent payroll stub
  • Valid Photo ID of 3rd Party Designee

AND

Category 2: Submit one document that has your full name and complete address used on the tax return filed:

  • Utility bill (gas, electric, cable, cell phone, etc.)
  • Bank statement
  • Payroll stub or W-2
  • Property tax bill
  • Rental agreement (signed by landlord and renter)
  • College or university transcript
  • Insurance policy (vehicle, homeowners, renters, health, life)
  • Credit card statement
  • Death Certificate
  • Birth Certificate


You may submit the documents:

  1. Electronically – Go to IDOR website: MyTax.illinois.gov, scroll down to the section titled “Identity Verification”, select the Identity Verification Documents link, enter your Letter ID, and follow the instructions.

Note: Submitting your information electronically will result in a quicker and more secure process. However, if you do not have a Letter ID, you must submit your documents by mail.

  1. By mail – send a copy of the letter (or Form IL-425 if you do not have the letter) and copies of the required documents to

ILLINOIS DEPARTMENT OF REVENUE
ANTI-FRAUD UNIT
PO BOX 19049
SPRINGFIELD, IL 62794-9049


Warning: Do NOT mail original documents; they accept copies.


6. I do not have access to a computer, or I am having difficulty verifying my identity electronically. What should I do?

Follow the instructions under the question “I did not verify my identity by the due date. What should I do?” for submitting documents to verify your identity by mail.


For more information: please go to the IDOR website: https://tax.illinois.gov/individuals/identity-verification-letters-information.html


If you have any questions regarding verifying your identity, please contact your accountant at Scheffel Boyle or the Illinois Department of Revenue at (800)732-8866.

https://scheffelboyle.com/wp-content/uploads/2023/07/blog-2.png 1080 1080 Suzi Seaton https://scheffelboyle.com/wp-content/uploads/2022/06/Transparent-Logo-5.png Suzi Seaton2023-07-11 13:55:572023-07-11 13:55:57Did you receive an Identity Verification Letter?

NASBA Announces New Amendment to CPA Exam

May 16, 2023

The National Association of State Boards of Accountancy (NASBA) has announced the adoption of a highly anticipated amendment to the Uniform Accountancy Act (UAA) Model Rules affecting the Uniform CPA Exam. 

Since 2004, candidates for the CPA Exam have had 18 months to complete the remaining 3 parts of the Exam upon the passing of the first part. On April 21, 2023, the NASBA Board of Directors voted for candidates to now have 30 months to complete the CPA Exam. This gives candidates another year to complete the CPA Exam requirements.

The UAA Model Rules have no effect on state board rules. While uniformity is encouraged, each state board can choose to adopt this amendment or not. Current candidates for the CPA Exam remain under the existing rules until, if and when, the board to which they applied for makes the change. 

Both Illinois and Missouri State Boards of Accountancy have not yet adopted this amendment.


For more information, please read NASBA’s press release: here


If you have any questions, please give us a call. We’re always here to help!

https://scheffelboyle.com/wp-content/uploads/2023/05/blog-1.png 1080 1080 Suzi Seaton https://scheffelboyle.com/wp-content/uploads/2022/06/Transparent-Logo-5.png Suzi Seaton2023-05-16 10:08:302023-05-16 10:08:30NASBA Announces New Amendment to CPA Exam

Scheffel Boyle CPAs Welcomes 2 New Staff Accountants

February 20, 2023

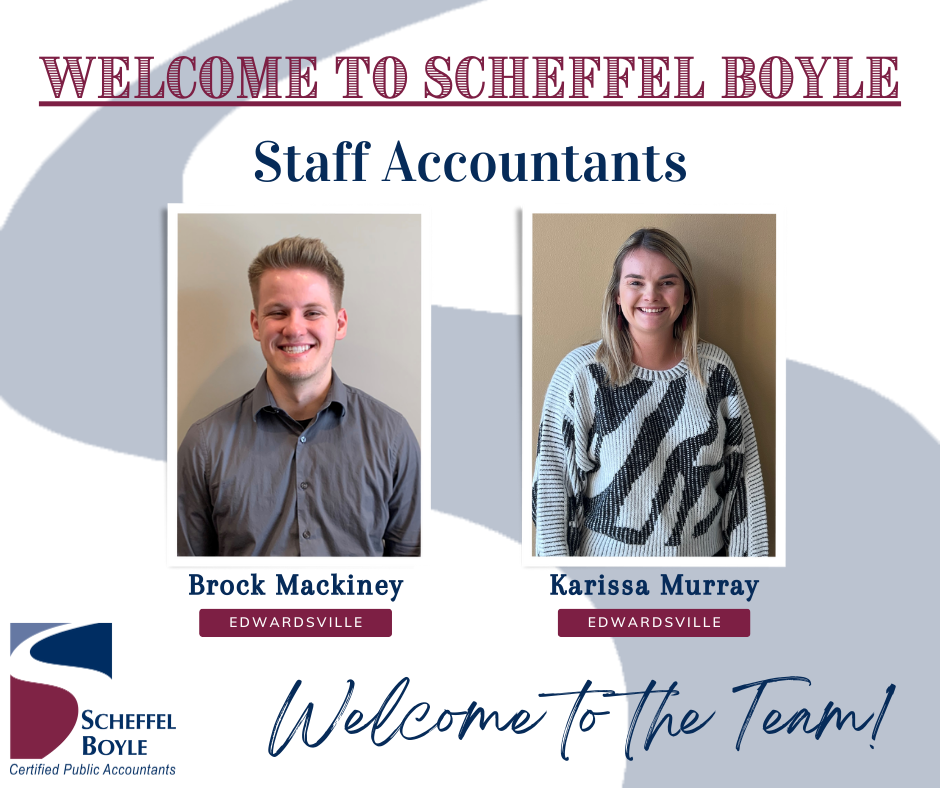
Scheffel Boyle CPAs is pleased to announce the recent addition of two Staff Accountants to their growing team. The local public accounting firm welcomed their newest full-time Staff Accountants to its Edwardsville office, with plans for more growth later this year.

The additions include Southern Illinois University Edwardsville graduate Brock Mackiney and Karissa Murray from Greenville University. They will now continue their careers as the newest Staff Accountants of the 100+ employee public accounting firm.

With seven offices throughout Southern Illinois, Scheffel Boyle is recognized as one of the largest CPA firms in the entire St. Louis region. The firm has career opportunities available to accounting students currently enrolled in school, recent college graduates, and experienced accounting professionals. To learn more about available opportunities and the benefits of joining the Scheffel Boyle team, please visit the Careers section of their website, www.scheffelboyle.com.

https://scheffelboyle.com/wp-content/uploads/2023/02/New-employees-1.png 788 940 Suzi Seaton https://scheffelboyle.com/wp-content/uploads/2022/06/Transparent-Logo-5.png Suzi Seaton2023-02-20 13:02:332023-02-20 13:02:33Scheffel Boyle CPAs Welcomes 2 New Staff Accountants

Scheffel Boyle CPAs Welcomes 23 Interns for 2023

February 20, 2023


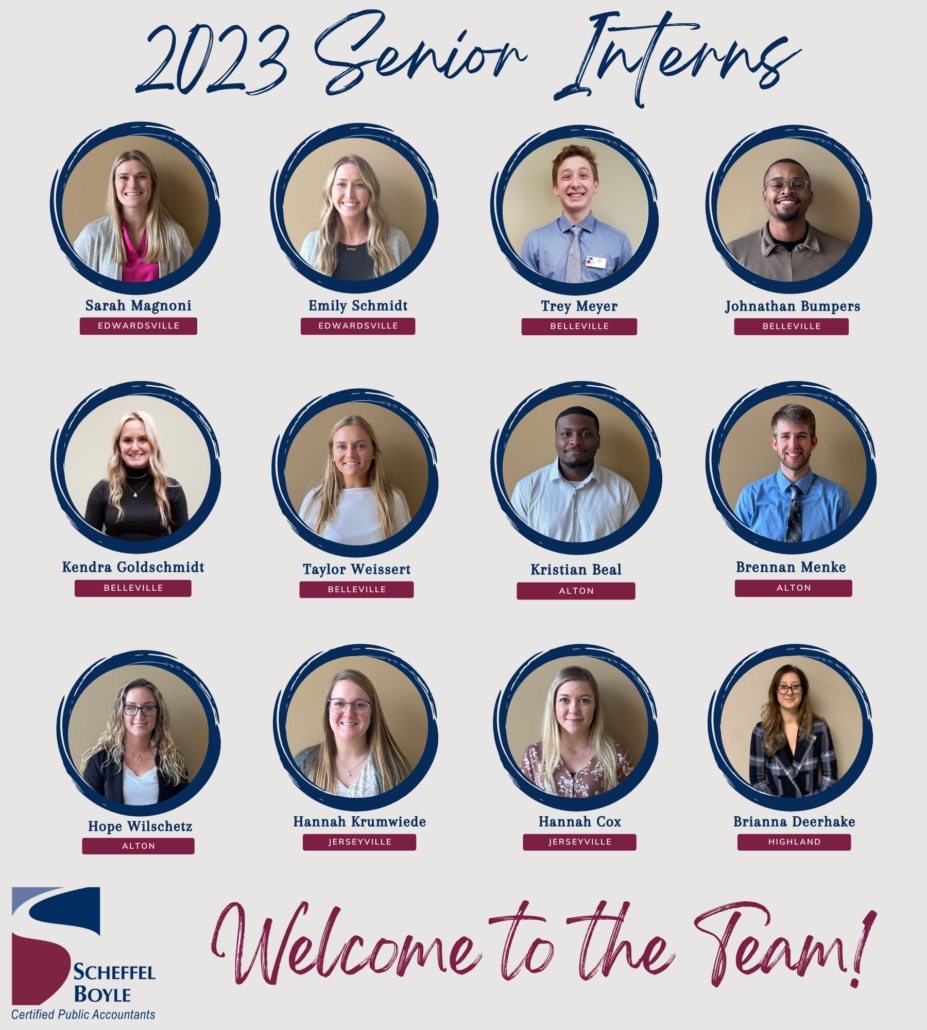
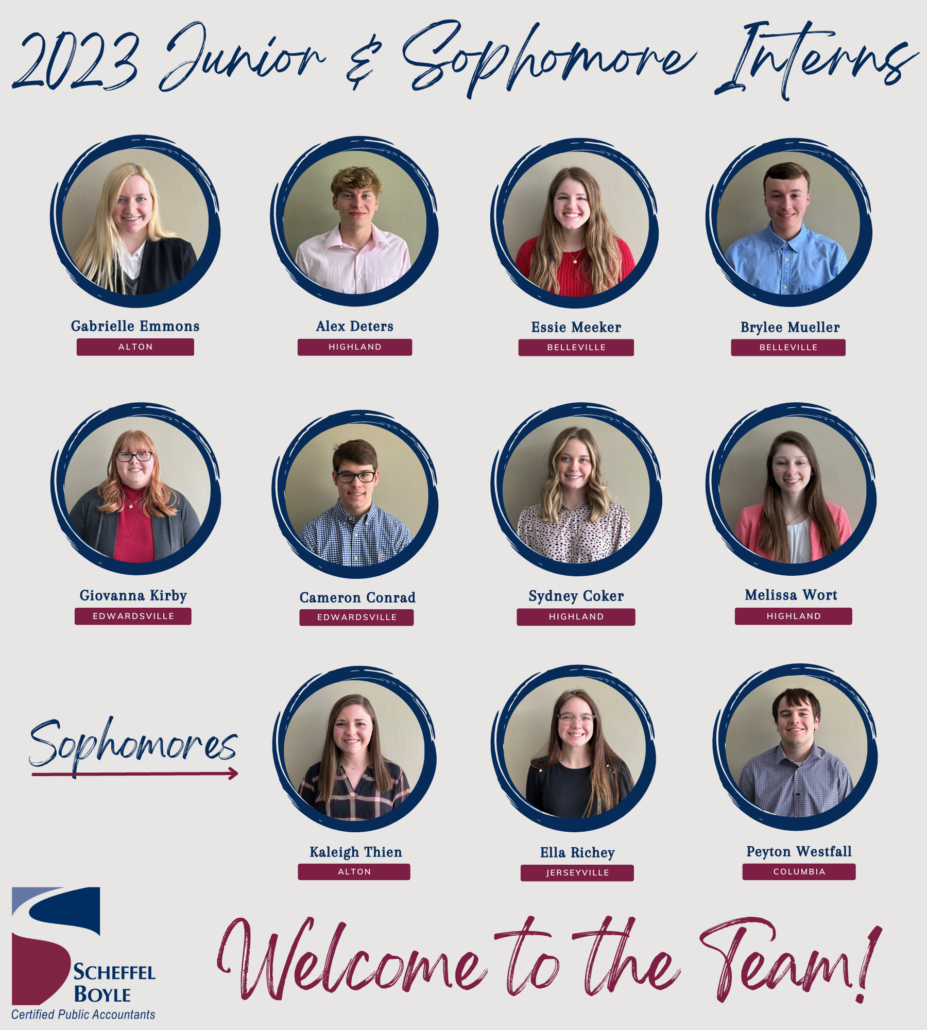
Scheffel Boyle CPAs is pleased to announce the recent addition of 12 Senior Interns, 8 Junior Interns, and 3 Sophomore Interns to their growing team.

The 2023 FOCUS Senior Interns include Southern Illinois University Edwardsville students Trey Meyer, Taylor Weissert, Kristian Beal, Brennan Menke, Hope Wilschetz, Hannah Krumwiede, Emily Schmidt, and Sarah Magnoni; and McKendree University students Johnathan Bumpers and Brianna Deerhake; University of Illinois Springfield student Hannah Cox; and Kendra Goldschmidt from Central Methodist University.

The 2023 FOCUS Junior Interns include Southern Illinois University Edwardsville students Gabrielle Emmons, Brylee Mueller, Giovanna Kirby, Cameron Conrad, Sydney Coker, Melissa Wort, and Alex Deters; and McKendree University student Essie Meeker.

The 2023 FOCUS Sophomore Interns include Southern Illinois University Edwardsville student Peyton Westfall, Lewis & Clark Community College student Kaleigh Thien, and Ella Richey from University of Illinois Springfield.

The FOCUS program places all intern accounting students throughout all seven of the firm’s offices for a Spring Internship. Students who are accepted into the program receive extensive training and real-world experience during the firm’s busiest time – tax season. In addition, each intern is entered into a mentor program in order to walk them through training measures and best practices.

With seven offices throughout Southern Illinois, Scheffel Boyle is recognized as one of the largest CPA firms in the entire St. Louis region. The firm has career opportunities available to accounting students currently enrolled in school, recent college graduates, and experienced accounting professionals. To learn more about available opportunities and the benefits of joining the Scheffel Boyle team, please visit the Careers section of their website, www.scheffelboyle.com.

https://scheffelboyle.com/wp-content/uploads/2023/02/1.png 2000 1800 Suzi Seaton https://scheffelboyle.com/wp-content/uploads/2022/06/Transparent-Logo-5.png Suzi Seaton2023-02-20 12:50:212023-02-20 12:50:21Scheffel Boyle CPAs Welcomes 23 Interns for 2023

Scheffel Boyle CPAs Ranks #12, #13 in STL Business Journal’s Annual Largest Accounting Firms Lists

February 6, 2023

Scheffel Boyle has ranked #12 for number of CPAs and #13 for number of professionals on the St. Louis Business Journal’s annual Largest Accounting Firms lists.

Each year, The Journal publishes two lists for ranking CPA firms: one based on the number of CPAs and the other on the number of professionals (employees required to have continuing education hours).

Thank you to our clients, employees, and community partners for all they have done to help us grow and continue serving the St. Louis and Metro East region.

https://scheffelboyle.com/wp-content/uploads/2023/02/Biz-Journal-List-2022.png 627 1200 Suzi Seaton https://scheffelboyle.com/wp-content/uploads/2022/06/Transparent-Logo-5.png Suzi Seaton2023-02-06 16:18:422023-02-06 16:21:00Scheffel Boyle CPAs Ranks #12, #13 in STL Business Journal’s Annual Largest Accounting Firms Lists

2023 Tax Calendar: Quarter 1

January 20, 2023

January 31 – Employers must file 2022 Forms W-2 (“Wage and Tax Statement”) with the Social Security Administration and provide copies to their employees. 

  • Employers must file (paper or electronic) 2022 Forms 1099-NEC (“Nonemployee Compensation”), reporting nonemployee compensation payments, along with the related Form 1096 (“Annual Summary and Transmittal of U.S. Information Returns”), and provide copies to recipients. 
  • Most employers must file Form 941 (“Employer’s Quarterly Federal Tax Return”) to report Medicare, Social Security and income taxes withheld in the fourth quarter of 2022. If an employer’s tax liability is less than $2,500, he or she can pay it in full with a timely filed return. If an employer deposited the tax for the quarter in full and on time, he or she has until February 10 to file the return. Employers who have an estimated annual employment tax liability of $1,000 or less may be eligible to file Form 944 (“Employer’s Annual Federal Tax Return”). 
  • Employers must file Form 940 (“Employer’s Annual Federal Unemployment (FUTA) Tax Return”) for 2022. If an employer’s undeposited tax is $500 or less, he or she can either pay it with the return or deposit it. If it is more than $500, he or she must deposit it. However, if an employer deposited the tax for the year in full and on time, he or she has until February 10 to file the return. 
  • Employers must file Form 943 (“Employer’s Annual Federal Tax Return for Agricultural Employees”) to report Social Security, Medicare and withheld income taxes for 2022. If an employer’s tax liability is less than $2,500, he or she can pay it in full with a timely filed return. If an employer deposited the tax for the year in full and on time, he or she has until February 10 to file the return. 
  • Employers must file Form 945 (“Annual Return of Withheld Federal Income Tax”) for 2022 to report income tax withheld on all nonpayroll items, including backup withholding and withholding on pensions, annuities, IRAs, etc. If an employer’s tax liability is less than $2,500, he or she can pay it in full with a timely filed return. If an employer deposited the tax for the year in full and on time, he or she has until February 10 to file the return. 

February 28 – Employers must file 2022 Form 1099-MISC (“Miscellaneous Income”) reporting certain payments to certain persons, along with the related Form 1096 (“Annual Summary and Transmittal of U.S. Information Returns”), and provide copies to recipients. 

March 15 – Calendar-year partnerships and S corporations must file or extend 2022 tax returns. If the return is not extended, this is also the last day


If you have any questions, please feel free to ask one of our trusted CPAs! We’re always here to help!

https://scheffelboyle.com/wp-content/uploads/2023/01/tax-2023.png 650 645 Suzi Seaton https://scheffelboyle.com/wp-content/uploads/2022/06/Transparent-Logo-5.png Suzi Seaton2023-01-20 15:31:102023-02-16 11:41:132023 Tax Calendar: Quarter 1

IL Unclaimed Property Rules Update

January 11, 2023

Is your business subject to Illinois Unclaimed Property rules?

Does your business have employees, customers, or suppliers? If so, you may have an obligation to report and remit unclaimed property to the state of Illinois.

What is the purpose of unclaimed property rules and is this unique to Illinois?

The purpose of unclaimed property rules is to ensure protection of the unclaimed property until the rightful owner is located. All 50 states and the District of Columbia have unclaimed property laws.

What is unclaimed property?

Unclaimed property is intangible personal property for which there has been no owner activity related to that property for a certain period of time. Examples of unclaimed property include uncashed payroll checks, customer overpayments, uncashed/voided checks to vendors, and gift cards/certificates with an expiration date.

How long of a period of inactivity before I need to do something?

The period of inactivity is referred to as the dormancy period. The general rule is that after a 3-year dormancy period the unclaimed property must be reported and remitted to the state. Some property types have different dormancy periods.  For example, the dormancy period for payroll is one year.

I don’t have any unclaimed property. I don’t need to file, right?

This was true until the law recently changed for certain businesses. If your business has annual sales of more than $1,000,000 or more than 100 employees, an unclaimed property report is required even if there is no property to remit to Illinois.

If I need to file a report, how do I do that and when is it due?

Reports must be filed electronically with the Illinois Treasurer. The filing deadline for most businesses is May 1st and is based on unclaimed property held as of 12/31 of the previous calendar year. Business must also reach out to the presumed owner of the property at least 60 days prior to filing the report in an attempt to return the property and/or to inform the presumed owner that the property will be remitted to the state.

What are the consequences of failing to file?

Interest and penalties may be imposed on the failure to file, pay or deliver property by the required due date. Interest may be charged at 1% per month on the value of the unreported/unpaid property. A penalty of $200/day up to a maximum of $5,000 may be imposed until the date a report is filed or the unclaimed property is paid or delivered.

How far back can Illinois go in determining if my business has a liability?

The statute of limitations for the State Treasurer to enforce ends 10 years after property is reported.

What do I do if I have never filed, or I am late on some prior year filings?

Illinois offers a Voluntary Disclosure Agreement (VDA) which allows non-compliant business to voluntarily come forward and become current with their filings. In exchange for voluntary compliance, the state agrees to waive any interest and/or penalties that may have otherwise been due. It’s similar to a free pass in exchange for current and future compliance.


If you have any questions regarding unclaimed property, please give us a call. We’re always here to help!

https://scheffelboyle.com/wp-content/uploads/2023/01/Blog-Photos-2.png 788 940 Suzi Seaton https://scheffelboyle.com/wp-content/uploads/2022/06/Transparent-Logo-5.png Suzi Seaton2023-01-11 17:27:192023-02-16 11:40:55IL Unclaimed Property Rules Update

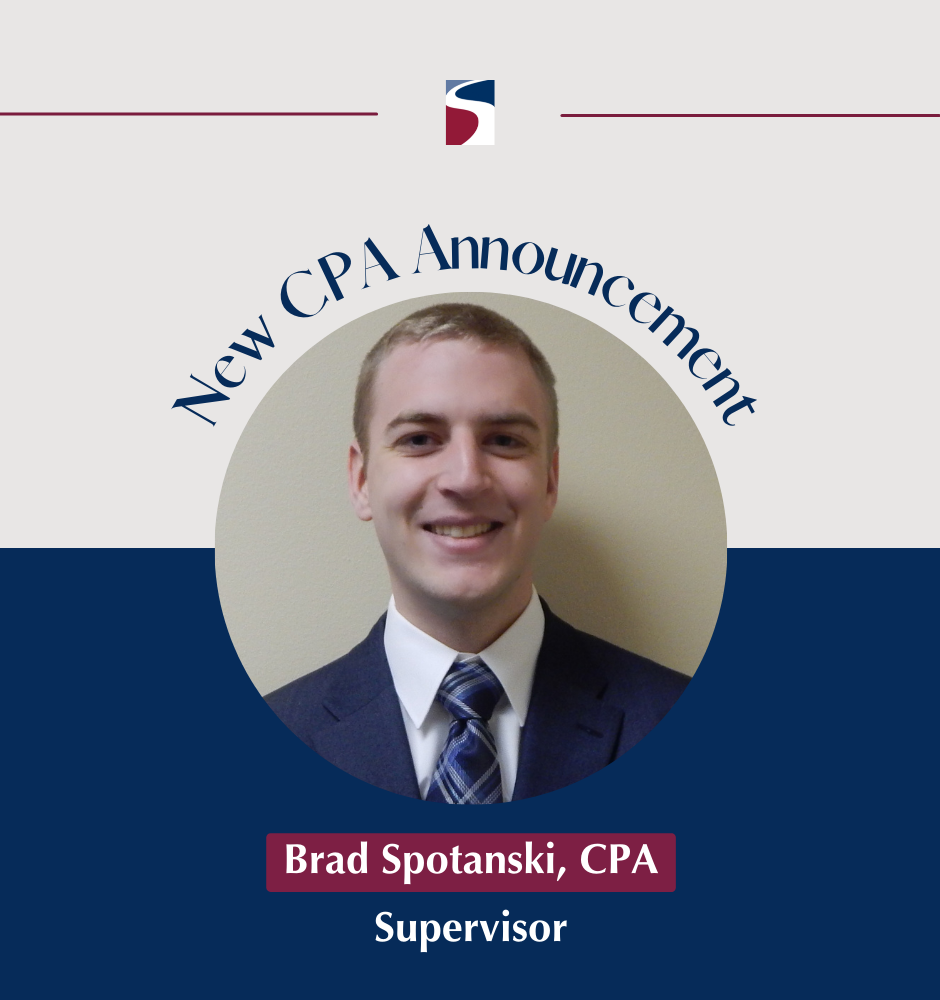
Announcing 1 New CPA at Scheffel Boyle

November 18, 2022

Scheffel Boyle CPAs is pleased to announce an accountant at their Edwardsville office who has officially earned his CPA designation. Brad Spotanski has passed the four parts of the AICPA’s administered CPA exam. He is now among over 40 Certified Public Accountants working throughout Scheffel Boyle’s seven offices.

Brad graduated from McKendree University with his Bachelor of Business Administration in Accounting and Economics/Finance in 2014. He joined the Scheffel Boyle team in 2015 and is currently a Supervisor in the firm’s Edwardsville office.

https://scheffelboyle.com/wp-content/uploads/2022/11/Promotion-Announcement.png 1000 940 Suzi Seaton https://scheffelboyle.com/wp-content/uploads/2022/06/Transparent-Logo-5.png Suzi Seaton2022-11-18 11:14:542022-11-18 11:14:54Announcing 1 New CPA at Scheffel Boyle
Page 1 of 11123›»

Pages

  • 2025 Seminar Registration
  • 2025 Seminar Registration Presentation Slides
  • 2026 Summer Sneak Peek
  • About Us
  • Accounting and Office Manager
  • Accounting Clerk
  • Accounting Services
  • Administrative Assistant
  • Administrative Assistant – Columbia Office
  • Administrative Assistant – Edwardsville Office
  • Administrative Support Specialist
  • Administrative Support Specialist
  • AGCI Webinar Presentation
  • Agribusiness
  • Alton, IL
  • Andrea Suhre
  • Andrea Suhre
  • Audit & Assurance
  • Available Opportunities
  • BDO Alliance USA
  • Belleville, IL
  • Bookkeeper
  • Bookkeeper/Payroll Specialist
  • Brian Otten
  • Business Valuations
  • Careers
  • Carrollton, IL
  • Columbia, IL
  • Construction Accounting
  • Construction Newsletter
  • Construction Tax Seminar Presentation
  • Consulting Services
  • Contact Us
  • Coronavirus Resource Center
  • Cory E. Gallivan
  • Crystal Bock
  • Crystal Bock
  • Dale Holtmann
  • Daniel Phipps
  • Data Entry Assistants
  • Dennis E. Ulrich
  • E-News Sign Up
  • Edwardsville, IL
  • Elements
  • Employee Benefit Plans
  • Experienced Accountants
  • Experienced Public Accountant
  • Financial Calculators
  • Financial Institution
  • FOCUS Internship Program
  • Full-Time Interview Sign-Up
  • George Moore
  • Governmental Entities
  • Heather Clugston
  • Helpful Links
  • Highland, IL
  • Home
  • Howard Held
  • Individual Clients
  • Industries
  • Interview Thank You
  • Interview Timeslots
  • IT Support Specialist
  • Jerseyville, IL
  • Julie Billeter
  • Julie Graham
  • Kathy Fitzgerald
  • Keith Brinkmann
  • Knowledge Center
  • Lisa Bohnenstiehl
  • Locations
  • Mark Korte
  • Marketing Specialist
  • Michael D. Ulrich
  • Michael E. Fitzgerald
  • Michael T. Brokering
  • Non-Profit Organizations
  • Office Accounting Assistant
  • Our Team
  • Outsourced Accountant
  • Part-Time Bookkeeper
  • Payroll Assistant
  • Payroll Supervisor
  • Peer Review
  • Privacy Policy
  • Privately-Held Businesses
  • Professional Affiliations
  • Recruiting Events
  • Recruiting/Human Resources Coordinator
  • Resources
  • Robyn M. Klingler
  • Russell Gregson
  • Sarah Smith
  • Scheffel Boyle News
  • Scheffel Boyle Shares
  • Scott Weber
  • Seasonal Tax Preparer
  • Services
  • SIBA Webinar Presentation
  • Sneak Peek Survey
  • Spring Tax Internship Program 2026
  • STL Ag Club Webinar Prez
  • Summer Audit Internship Program
  • Summer Audit Internship Program 2026
  • Tax Planning & Preparation
  • Tax Talks Information
  • Tax Talks Presentation
  • Testimonials
  • Webinar Presentation May 14
  • Welcome Email
  • Year-End Tax Planning Seminars
  • Accountant – Carrollton
  • Administrative Assistant – Alton Office
  • Administrative Assistant – Belleville Office
  • Administrative Assistant – Columbia Office
  • Seasonal Administrative Assistants
  • Seasonal Data Input
  • Staff Accountant

Categories

  • Blog
  • Construction
  • Coronavirus Resource Center
  • Frontpage
  • Knowledge Center
  • Scheffel News
  • Uncategorized

Archive

  • August 2026
  • May 2026
  • November 2025
  • October 2025
  • July 2025
  • February 2024
  • July 2023
  • May 2023
  • February 2023
  • January 2023
  • November 2022
  • August 2022
  • July 2022
  • June 2022
  • March 2022
  • February 2022
  • January 2022
  • December 2021
  • June 2021
  • May 2021
  • April 2021
  • March 2021
  • February 2021
  • January 2021
  • December 2020
  • November 2020
  • October 2020
  • September 2020
  • August 2020
  • July 2020
  • June 2020
  • May 2020
  • April 2020
  • March 2020
  • February 2020
  • January 2020
  • December 2019
  • November 2019
  • October 2019
  • September 2019
  • August 2019
  • July 2019
  • June 2019
  • May 2019
  • April 2019
  • March 2019
  • February 2019
  • January 2019
  • December 2018
  • November 2018
  • October 2018
  • September 2018
  • August 2018
  • July 2018
  • June 2018
  • May 2018
  • April 2018
  • March 2018
  • February 2018
  • January 2018
  • December 2017
  • November 2017
  • October 2017
  • September 2017
  • August 2017
  • July 2017
  • June 2017
  • May 2017
  • April 2017
  • March 2017
  • February 2017
  • January 2017
  • December 2016
  • October 2016
  • September 2016
  • August 2016
  • July 2016
  • May 2016
  • April 2016
  • March 2016
  • February 2016
  • January 2016
  • December 2015
  • November 2015
  • August 2015
  • July 2015
  • June 2015
  • February 2015
  • January 2015
  • December 2014
  • November 2014
  • September 2014
  • August 2014
  • March 2014
  • February 2014
  • December 2013
  • November 2013
  • October 2013
  • August 2013
  • July 2013
  • June 2013
  • May 2013
  • February 2013
  • January 2013

About Us


Serving St. Louis, the Metro-East and Southwestern Illinois since 1924.

Knowledge Center

  • New Rules Could Increase Taxable Income for GamblersAugust 24, 2026 - 3:20 pm
  • IRS Notice CP53E and the Rise of Refund-Related ScamsMay 18, 2026 - 9:55 am
  • Potential Refund Deadline Extensions Under the Kwong CaseMay 7, 2026 - 11:40 am

Quick Links

  • Services
  • Clients & Industries
  • Our Team
  • Scheffel Boyle News
  • Careers

 Contact Us

Alton, IL: 618.465.4288
Edwardsville, IL: 618.656.1206
Belleville, IL: 618.277.8100
Highland, IL: 618.654.9895
Jerseyville, IL: 618.498.6841
Columbia, IL: 618.281.7605
Carrollton, IL: 217.942.3821

© Copyright 2021 Scheffel Boyle — All rights reserved
  • Site Map
  • Privacy Policy
Scroll to top Scroll to top Scroll to top