Loading
Scheffel Boyle
  • Home
  • About Us
    • Our Team
    • Our Values
    • Scheffel Boyle News
    • Professional Affiliations
    • Client Testimonials
    • Peer Review
    • Scheffel Boyle Shares
    • BDO Alliance USA
  • Services
    • Tax Planning & Preparation
    • Audit & Assurance
    • Accounting Services
    • Consulting Services
    • Financial Advisory
  • Clients & Industries
    • Construction
    • Financial Institutions
    • Agribusiness
    • Governmental Entities
    • Non-Profit Organizations
    • Privately-Held Businesses
    • Individual Clients
    • Employee Benefit Plans
  • Resources
    • Knowledge Center
    • Coronavirus Resource Center
    • Helpful Links
  • Careers
    • Benefits
    • Available Opportunities
    • College Students
  • Contact Us
    • Locations
      • Alton, IL
      • Belleville, IL
      • Carrollton, IL
      • Columbia, IL
      • Edwardsville, IL
      • Highland, IL
      • Jerseyville, IL
  • Click to open the search input field Click to open the search input field Search
  • Menu Menu
  • Link to Facebook
  • Link to LinkedIn

Multistate Resident? Watch Out For Double Taxation

January 30, 2019
Contrary to popular belief, there’s nothing in the U.S. Constitution or federal law that prohibits multiple states from collecting tax on the same income. Although many states provide tax credits to prevent double taxation, those credits are sometimes unavailable. If you maintain residences in more than one state, here are some points to keep in mind.


Domicile vs. Residence

Generally, if you’re “domiciled” in a state, you’re subject to that state’s income tax on your worldwide income. Your domicile isn’t necessarily where you spend most of your time. Rather, it’s the location of your “true, fixed, permanent home” or the place “to which you intend to return whenever absent.” Your domicile doesn’t change — even if you spend little or no time there — until you establish domicile elsewhere.

Residence, on the other hand, is based on the amount of time you spend in a state. You’re a resident if you have a “permanent place of abode” in a state and spend a minimum amount of time there — for example, at least 183 days per year. Many states impose their income taxes on residents’ worldwide income even if they’re domiciled in another state.

Potential Solution

Suppose you live in State A and work in State B. Given the length of your commute, you keep an apartment in State B near your office and return to your home in State A only on weekends. State A taxes you as a domiciliary, while State B taxes you as a resident. Neither state offers a credit for taxes paid to another state, so your income is taxed twice.

One possible solution to such double taxation is to avoid maintaining a permanent place of abode in State B. However, State B may still have the power to tax your income from the job in State B because it’s derived from a source within the state. Yet State B wouldn’t be able to tax your income from other sources, such as investments you made in State A.

Minimize Unnecessary Taxes

This example illustrates just one way double taxation can arise when you divide your time between two or more states. We can research applicable state law and identify ways to minimize exposure to unnecessary taxes.


Sidebar: How to Establish Domicile

Under the law of each state, tax credits are available only with respect to income taxes that are “properly due” to another state. But, when two states each claim you as a domiciliary, neither believes that taxes are properly due to the other. To avoid double taxation in this situation, you’ll need to demonstrate your intent to abandon your domicile in one state and establish it in the other.

There are various ways to do so. For example, you might obtain a driver’s license and register your car in the new state. You could also open bank accounts in the new state and use your new address for important financially related documents (such as insurance policies, tax returns, passports and wills). Other effective measures may include registering to vote in the new jurisdiction, subscribing to local newspapers and seeing local health care providers. Bear in mind, of course, that laws regarding domicile vary from state to state.
Copyright © 2019

https://scheffelboyle.com/wp-content/uploads/2019/01/states.jpg 1500 2250 brett@bonniburns.com https://scheffelboyle.com/wp-content/uploads/2022/06/Transparent-Logo-5.png brett@bonniburns.com2019-01-30 15:47:222020-01-28 15:25:13Multistate Resident? Watch Out For Double Taxation

Fewer Taxpayers to Qualify for Home Office Deduction

January 25, 2019
Working from home has become commonplace for people in many jobs. But just because you have a home office space doesn’t mean you can deduct expenses associated with it. Beginning with the 2018 tax year, fewer taxpayers will qualify for the home office deduction. Here’s why.


Changes Under the TCJA

For employees, home office expenses used to be a miscellaneous itemized deduction. Way back in 2017, this meant one could enjoy a tax benefit only if these expenses plus other miscellaneous itemized expenses (such as unreimbursed work-related travel, certain professional fees and investment expenses) exceeded 2% of adjusted gross income.

Starting in 2018 and continuing through 2025, however, employees can’t deduct any home office expenses. Why? The Tax Cuts and Jobs Act (TCJA) suspends miscellaneous itemized deductions subject to the 2% floor for this period.

Note: If you’re self-employed, you can still deduct eligible home office expenses against your self-employment income during the 2018 through 2025 period.

Other Eligibility Requirements

If you’re self-employed, generally your home office must be your principal place of business, though there are exceptions.

Whether you’re an employee or self-employed, the space must be used regularly (not just occasionally) and exclusively for business purposes. If, for example, your home office is also a guest bedroom or your children do their homework there, you can’t deduct the expenses associated with that space.

Deduction Options

If eligible, you have two options for claiming the home office deduction. First, you can deduct a portion of your mortgage interest, property taxes, insurance, utilities and certain other expenses, as well as the depreciation allocable to the office space. This requires calculating, allocating and substantiating actual expenses.

A second approach is to take the “safe harbor” deduction. Here, only one simple calculation is necessary: $5 multiplied by the number of square feet of the office space. The safe harbor deduction is capped at $1,500 per year, based on a maximum of 300 square feet.

More Rules and Limits

Be aware that we’ve covered only a few of the rules and limits here. If you think you may qualify for the home office deduction on your 2018 return or would like to know if there’s anything additional you need to do to become eligible, contact us.

Copyright © 2019

https://scheffelboyle.com/wp-content/uploads/2019/01/home-office.jpg 1500 1000 brett@bonniburns.com https://scheffelboyle.com/wp-content/uploads/2022/06/Transparent-Logo-5.png brett@bonniburns.com2019-01-25 16:07:382020-01-28 15:25:21Fewer Taxpayers to Qualify for Home Office Deduction

It’s Welcome Week for our Interns!

January 23, 2019

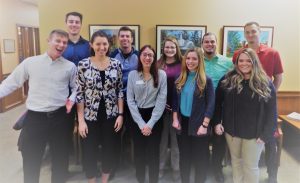
We are so excited to welcome our Interns for Focus 2019! They all survived our training sessions last week, and now we are welcoming them in our offices. We know you all will do great things.

Back Row: Ryan McGuire (Jerseyville), Wayne Sherland (Edwardsville), Sydney Boschert (Alton), Eric Radake (Columbia), and Zach Williams (Belleville)

Front Row: Scott Gannon (Edwardsville), Rachel Alde (Belleville), Courtney Farrell (Edwardsville), Madeline Livvix (Highland), and Molly Turner (Jerseyville)

https://scheffelboyle.com/wp-content/uploads/2019/01/Interns-2019.jpg 2647 4343 brett@bonniburns.com https://scheffelboyle.com/wp-content/uploads/2022/06/Transparent-Logo-5.png brett@bonniburns.com2019-01-23 08:44:202019-01-23 08:46:04It’s Welcome Week for our Interns!

Welcome to the Team!

January 11, 2019

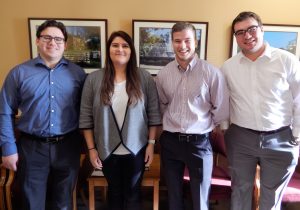
We are excited to introduce our new Staff Accountants!

John Reitano, Jessica Roman, Chad Brown, and Alex Hoffmann
John Reitano received both his Bachelor’s and Master’s Degrees in Accounting from SLU. Jessica Roman is a recent SIUE graduate and is currently in the Master’s program at SIUE. Chad Brown graduated with his Bachelor’s from UMSL and is also pursuing his Master’s. Alex Hoffmann received both his Bachelor’s and Master’s from Truman State University where he also served as the captain of their baseball team. John will be heading to the Belleville office, Jessica to Highland, Chad to Columbia, and Alex to Alton. We are so excited to welcome you all!


https://scheffelboyle.com/wp-content/uploads/2019/01/DSCN1472.jpg 3009 4291 brett@bonniburns.com https://scheffelboyle.com/wp-content/uploads/2022/06/Transparent-Logo-5.png brett@bonniburns.com2019-01-11 12:07:202019-01-11 19:55:52Welcome to the Team!

Seven Ways to Prevent Elder Financial Abuse

January 10, 2019
As tax season ramps up, so do the efforts of scam artists looking to steal people’s financial data and money. Such fraudulent activities often target older adults. Whether you’re in this age bracket or worry about senior parents and other relatives, here are seven ways to prevent elder financial abuse:
  1. Keep both paper and online financial documents in a secure place. Monitor accounts and retain statements.
  2. Exercise caution when making financial decisions. If someone exerts pressure or promises unreasonably high or guaranteed returns, walk away.
  3. Write checks only to legitimate financial institutions, rather than to a person.
  4. Be alert for phony phone calls. The IRS doesn’t collect money this way. Another scam involves someone pretending to be a grandchild who’s in trouble and needs money. Don’t provide confidential information or send money until you can verify the caller’s identity.
  5. Beware of emails requesting personal data — even if they appear to be from a real financial institution. After all, shouldn’t your banker or financial professional already know these things? Ignore contact information provided in the email. Instead, contact the financial institution through a known telephone number.
  6. As much as possible, maintain a social network. Criminals target isolated people because often they’re less aware of scams and lack trusted confidants.
  7. Work only with qualified professionals, including accountants, bankers and attorneys.

Copyright © 2019

https://scheffelboyle.com/wp-content/uploads/2019/01/Hands.jpeg 1500 2250 brett@bonniburns.com https://scheffelboyle.com/wp-content/uploads/2022/06/Transparent-Logo-5.png brett@bonniburns.com2019-01-10 12:52:362020-01-28 15:25:32Seven Ways to Prevent Elder Financial Abuse

Tax Season Hours Begin January 16th

January 9, 2019

To better accommodate our clients, we extend our office hours during tax season. Please note these hours listed below so we can better serve you.

Monday through Thursday

8am to 8pm


Fridays

8am to 6pm


Saturdays

8am to 3pm (through February)

8am to 5pm (thereafter through April 15)

https://scheffelboyle.com/wp-content/uploads/2019/01/Open.jpeg 1500 2250 brett@bonniburns.com https://scheffelboyle.com/wp-content/uploads/2022/06/Transparent-Logo-5.png brett@bonniburns.com2019-01-09 12:17:122019-01-14 16:31:09Tax Season Hours Begin January 16th

How to Trim Fat From Your Inventory

January 6, 2019
Inventory is expensive, so it needs to be as lean as possible. Here are some ways to trim the fat from your inventory without compromising revenue and customer service.


Objective Inventory Counts

Effective inventory management starts with a physical inventory count. Accuracy is essential to knowing your cost of goods sold — and to identifying and remedying discrepancies between your physical count and perpetual inventory records. A CPA can introduce an element of objectivity to the counting process and help minimize errors.

The next step is to compare your inventory costs to those of other companies in your industry. Trade associations often publish benchmarks for:

  • Gross margin ([revenue – cost of sales] / revenue),
  • Net profit margin (net income / revenue), and
  • Days in inventory (annual revenue / average inventory × 365 days).

Your company should strive to meet — or beat — industry standards. For a retailer or wholesaler, inventory is simply purchased from the manufacturer. But the inventory account is more complicated for manufacturers and construction firms. It’s a function of raw materials, labor and overhead costs.

The composition of your company’s cost of goods will guide you on where to cut. In a tight labor market, it’s hard to reduce labor costs. But it may be possible to renegotiate prices with suppliers.

And don’t forget the carrying costs of inventory, such as storage, insurance, obsolescence and pilferage. You can also improve margins by negotiating a net lease for your warehouse, installing antitheft devices or opting for less expensive insurance coverage.

Product Mix

To cut your days-in-inventory ratio, compute product-by-product margins. Stock more products with high margins and high demand — and less of everything else. Whenever possible, return excessive supplies of slow-moving materials or products to your suppliers.

Product mix should be sufficiently broad and in tune with consumer needs. Before cutting back on inventory, you might need to negotiate speedier delivery from suppliers or give suppliers access to your perpetual inventory system. These precautionary measures can help prevent lost sales due to lean inventory.

Reality Check

Often management is so focused on sales, HR issues and product innovation that they lose control over inventory. Contact us for a reality check.

Copyright © 2019

https://scheffelboyle.com/wp-content/uploads/2019/01/stock.jpeg 1500 2250 brett@bonniburns.com https://scheffelboyle.com/wp-content/uploads/2022/06/Transparent-Logo-5.png brett@bonniburns.com2019-01-06 11:49:442020-01-28 15:25:41How to Trim Fat From Your Inventory

Installment Sales: A Viable Option for Transferring Assets

January 3, 2019
Are you considering transferring real estate, a family business or other assets you expect to appreciate dramatically in the future? If so, an installment sale may be a viable option. Its benefits include the ability to freeze asset values for estate tax purposes and remove future appreciation from your taxable estate.


Giving Away vs. Selling

From an estate planning perspective, if you have a taxable estate it’s usually more advantageous to give property to your children than to sell it to them. By gifting the asset you’ll be depleting your estate and thereby reducing potential estate tax liability, whereas in a sale the proceeds generally will be included in your taxable estate.

But an installment sale may be desirable if you’ve already used up your $11.18 million (for 2018) lifetime gift tax exemption or if your cash flow needs preclude you from giving the property away outright. When you sell property at fair market value to your children or other loved ones rather than gifting it, you avoid gift taxes on the transfer and freeze the property’s value for estate tax purposes as of the sale date. All future appreciation benefits the buyer and won’t be included in your taxable estate.

Because the transaction is structured as a sale rather than a gift, your buyer must have the financial resources to buy the property. But by using an installment note, the buyer can make the payments over time. Ideally, the purchased property will generate enough income to fund these payments.

Advantages and Disadvantages

An advantage of an installment sale is that it gives you the flexibility to design a payment schedule that corresponds with the property’s cash flow, as well as with your and your buyer’s financial needs. You can arrange for the payments to increase or decrease over time, or even provide for interest-only payments with an end-of-term balloon payment of the principal.

One disadvantage of an installment sale over strategies that involve gifted property is that you’ll be subject to tax on any capital gains you recognize from the sale. Fortunately, you can spread this tax liability over the term of the installment note. As of this writing, the long-term capital gains rates are 0%, 15% or 20%, depending on the amount of your net long-term capital gains plus your ordinary income.

Also, you’ll have to charge interest on the note and pay ordinary income tax on the interest payments. IRS guidelines provide for a minimum rate of interest that must be paid on the note. On the bright side, any capital gains and ordinary income tax you pay further reduces the size of your taxable estate.

Simple Technique, Big Benefits

An installment sale is an approach worth exploring for business owners, real estate investors and others who have gathered high-value assets. It can help keep a family-owned business in the family or otherwise play an important role in your estate plan.

Bear in mind, however, that this simple technique isn’t right for everyone. We can review your situation and help you determine whether an installment sale is a wise move for you.

Copyright © 2019

https://scheffelboyle.com/wp-content/uploads/2019/01/real-estate.jpeg 1418 2520 brett@bonniburns.com https://scheffelboyle.com/wp-content/uploads/2022/06/Transparent-Logo-5.png brett@bonniburns.com2019-01-03 11:00:522020-01-28 15:25:51Installment Sales: A Viable Option for Transferring Assets

First Quarter 2019 Tax Deadlines

January 2, 2019

January 15

  • Individual taxpayers’ final 2018 estimated tax payment is due.

January 31

  • File 2018 Forms W-2 (“Wage and Tax Statement”) with the Social Security Administration and provide copies to your employees.
  • File 2018 Forms 1099-MISC (“Miscellaneous Income”) reporting nonemployee compensation payments in box 7 with the IRS and provide copies to recipients.
  • Most employers must file Form 941 (“Employer’s Quarterly Federal Tax Return”) to report Medicare, Social Security, and income taxes withheld in the fourth quarter of 2018. If your tax liability is less than $2,500, you can pay it in full with a timely filed return. If you deposited the tax for the quarter in full and on time, you have until February 11 to file the return. Employers who have an estimated annual employment tax liability of $1,000 or less may be eligible to file Form 944 (“Employer’s Annual Federal Tax Return”).
  • File Form 940 (“Employer’s Annual Federal Unemployment [FUTA] Tax Return”) for 2018. If your undeposited tax is $500 or less, you can either pay it with your return or deposit it. If it is more than $500, you must deposit it. However, if you deposited the tax for the year in full and on time, you have until February 11 to file the return.
  • File Form 943 (“Employer’s Annual Federal Tax Return for Agricultural Employees”) to report Social Security, Medicare and withheld income taxes for 2018. If your tax liability is less than $2,500, you can pay it in full with a timely filed return. If you deposited the tax for the year in full and on time, you have until February 11 to file the return.
  • File Form 945 (“Annual Return of Withheld Federal Income Tax”) for 2018 to report income tax withheld on all nonpayroll items, including backup withholding and withholding on pensions, annuities, IRAs, etc. If your tax liability is less than $2,500, you can pay it in full with a timely filed return. If you deposited the tax for the year in full and on time, you have until February 11 to file the return.

February 28

  • File 2018 Forms 1099-MISC with the IRS.

March 15

  • 2018 tax returns must be filed or extended for calendar-year partnerships and S corporations. If the return isn’t extended, this is also the last day for those types of entities to make 2018 contributions to pension and profit-sharing plans.

Copyright © 2019

https://scheffelboyle.com/wp-content/uploads/2019/01/time.jpeg 1500 2250 brett@bonniburns.com https://scheffelboyle.com/wp-content/uploads/2022/06/Transparent-Logo-5.png brett@bonniburns.com2019-01-02 12:56:482020-01-28 15:25:59First Quarter 2019 Tax Deadlines

Laying the Groundwork for Your 2018 Tax Return

January 1, 2019
The Tax Cuts and Jobs Act (TCJA) made many changes to tax breaks for individuals. Let’s look at some specific areas to review as you lay the groundwork for filing your 2018 return.


Personal Exemptions

For 2018 through 2025, the TCJA suspends personal exemptions. This will substantially increase taxable income for large families. However, enhancements to the standard deduction and child credit, combined with lower tax rates, might mitigate this increase.

Standard Deduction

Taxpayers can choose to itemize certain deductions on Schedule A or take the standard deduction based on their filing status instead. Itemizing deductions when the total will be larger than the standard deduction saves tax, but it makes filing more complicated.

The TCJA nearly doubles the standard deduction for 2018 to $12,000 for singles and separate filers, $18,000 for heads of households, and $24,000 for joint filers. (These amounts will be adjusted for inflation for 2019 through 2025.)

For some taxpayers, the increased standard deduction could compensate for the elimination of the exemptions, and perhaps even provide some additional tax savings. But for those with many dependents or who itemize deductions, these changes might result in a higher tax bill — depending in part on the extent to which they can benefit from enhancements to the child credit.

Child Credit

Credits can be more powerful than exemptions and deductions because they reduce taxes dollar-for-dollar, rather than just reducing the amount of income subject to tax. For 2018 through 2025, the TCJA doubles the child credit to $2,000 per child under age 17.

The new law also makes the child credit available to more families than in the past. For 2018 through 2025, the credit doesn’t begin to phase out until adjusted gross income exceeds $400,000 for joint filers or $200,000 for all other filers, compared with the 2017 phaseout thresholds of $110,000 for joint filers, $75,000 for singles and heads of households, and $55,000 for marrieds filing separately. The TCJA also includes, for 2018 through 2025, a $500 tax credit for qualifying dependents other than qualifying children.

Assessing the Impact

Many factors will influence the impact of the TCJA on your tax liability for 2018 and beyond. For help assessing the impact on your situation, contact us.

Copyright © 2019

https://scheffelboyle.com/wp-content/uploads/2019/01/accountant-accounting-adviser-advisor-159804.jpeg 1500 2250 brett@bonniburns.com https://scheffelboyle.com/wp-content/uploads/2022/06/Transparent-Logo-5.png brett@bonniburns.com2019-01-01 12:49:472020-01-28 15:26:04Laying the Groundwork for Your 2018 Tax Return

Pages

  • 2025 Seminar Registration
  • 2025 Seminar Registration Presentation Slides
  • 2026 Summer Sneak Peek
  • About Us
  • Accounting and Office Manager
  • Accounting Clerk
  • Accounting Services
  • Administrative Assistant
  • Administrative Assistant – Columbia Office
  • Administrative Assistant – Edwardsville Office
  • Administrative Support Specialist
  • Administrative Support Specialist
  • AGCI Webinar Presentation
  • Agribusiness
  • Alton, IL
  • Andrea Suhre
  • Andrea Suhre
  • Audit & Assurance
  • Available Opportunities
  • BDO Alliance USA
  • Belleville, IL
  • Bookkeeper
  • Bookkeeper/Payroll Specialist
  • Brian Otten
  • Business Valuations
  • Careers
  • Carrollton, IL
  • Columbia, IL
  • Construction Accounting
  • Construction Newsletter
  • Construction Tax Seminar Presentation
  • Consulting Services
  • Contact Us
  • Coronavirus Resource Center
  • Cory E. Gallivan
  • Crystal Bock
  • Crystal Bock
  • Dale Holtmann
  • Daniel Phipps
  • Data Entry Assistants
  • Dennis E. Ulrich
  • E-News Sign Up
  • Edwardsville, IL
  • Elements
  • Employee Benefit Plans
  • Experienced Accountants
  • Experienced Public Accountant
  • Financial Calculators
  • Financial Institution
  • FOCUS Internship Program
  • Full-Time Interview Sign-Up
  • George Moore
  • Governmental Entities
  • Heather Clugston
  • Helpful Links
  • Highland, IL
  • Home
  • Howard Held
  • Individual Clients
  • Industries
  • Interview Thank You
  • Interview Timeslots
  • IT Support Specialist
  • Jerseyville, IL
  • Julie Billeter
  • Julie Graham
  • Kathy Fitzgerald
  • Keith Brinkmann
  • Knowledge Center
  • Lisa Bohnenstiehl
  • Locations
  • Mark Korte
  • Marketing Specialist
  • Michael D. Ulrich
  • Michael E. Fitzgerald
  • Michael T. Brokering
  • Non-Profit Organizations
  • Office Accounting Assistant
  • Our Team
  • Outsourced Accountant
  • Part-Time Bookkeeper
  • Payroll Assistant
  • Payroll Supervisor
  • Peer Review
  • Privacy Policy
  • Privately-Held Businesses
  • Professional Affiliations
  • Recruiting Events
  • Recruiting/Human Resources Coordinator
  • Resources
  • Robyn M. Klingler
  • Russell Gregson
  • Sarah Smith
  • Scheffel Boyle News
  • Scheffel Boyle Shares
  • Scott Weber
  • Seasonal Tax Preparer
  • Services
  • SIBA Webinar Presentation
  • Sneak Peek Survey
  • Spring Tax Internship Program 2026
  • STL Ag Club Webinar Prez
  • Summer Audit Internship Program
  • Summer Audit Internship Program 2026
  • Tax Planning & Preparation
  • Tax Talks Information
  • Tax Talks Presentation
  • Testimonials
  • Webinar Presentation May 14
  • Welcome Email
  • Year-End Tax Planning Seminars
  • Accountant – Carrollton
  • Administrative Assistant – Alton Office
  • Administrative Assistant – Belleville Office
  • Administrative Assistant – Columbia Office
  • Seasonal Administrative Assistants
  • Seasonal Data Input
  • Staff Accountant

Categories

  • Blog
  • Construction
  • Coronavirus Resource Center
  • Frontpage
  • Knowledge Center
  • Scheffel News
  • Uncategorized

Archive

  • August 2026
  • May 2026
  • November 2025
  • October 2025
  • July 2025
  • February 2024
  • July 2023
  • May 2023
  • February 2023
  • January 2023
  • November 2022
  • August 2022
  • July 2022
  • June 2022
  • March 2022
  • February 2022
  • January 2022
  • December 2021
  • June 2021
  • May 2021
  • April 2021
  • March 2021
  • February 2021
  • January 2021
  • December 2020
  • November 2020
  • October 2020
  • September 2020
  • August 2020
  • July 2020
  • June 2020
  • May 2020
  • April 2020
  • March 2020
  • February 2020
  • January 2020
  • December 2019
  • November 2019
  • October 2019
  • September 2019
  • August 2019
  • July 2019
  • June 2019
  • May 2019
  • April 2019
  • March 2019
  • February 2019
  • January 2019
  • December 2018
  • November 2018
  • October 2018
  • September 2018
  • August 2018
  • July 2018
  • June 2018
  • May 2018
  • April 2018
  • March 2018
  • February 2018
  • January 2018
  • December 2017
  • November 2017
  • October 2017
  • September 2017
  • August 2017
  • July 2017
  • June 2017
  • May 2017
  • April 2017
  • March 2017
  • February 2017
  • January 2017
  • December 2016
  • October 2016
  • September 2016
  • August 2016
  • July 2016
  • May 2016
  • April 2016
  • March 2016
  • February 2016
  • January 2016
  • December 2015
  • November 2015
  • August 2015
  • July 2015
  • June 2015
  • February 2015
  • January 2015
  • December 2014
  • November 2014
  • September 2014
  • August 2014
  • March 2014
  • February 2014
  • December 2013
  • November 2013
  • October 2013
  • August 2013
  • July 2013
  • June 2013
  • May 2013
  • February 2013
  • January 2013

About Us


Serving St. Louis, the Metro-East and Southwestern Illinois since 1924.

Knowledge Center

  • New Rules Could Increase Taxable Income for GamblersAugust 24, 2026 - 3:20 pm
  • IRS Notice CP53E and the Rise of Refund-Related ScamsMay 18, 2026 - 9:55 am
  • Potential Refund Deadline Extensions Under the Kwong CaseMay 7, 2026 - 11:40 am

Quick Links

  • Services
  • Clients & Industries
  • Our Team
  • Scheffel Boyle News
  • Careers

 Contact Us

Alton, IL: 618.465.4288
Edwardsville, IL: 618.656.1206
Belleville, IL: 618.277.8100
Highland, IL: 618.654.9895
Jerseyville, IL: 618.498.6841
Columbia, IL: 618.281.7605
Carrollton, IL: 217.942.3821

© Copyright 2021 Scheffel Boyle — All rights reserved
  • Site Map
  • Privacy Policy
Scroll to top Scroll to top Scroll to top