Loading
Scheffel Boyle
  • Home
  • About Us
    • Our Team
    • Our Values
    • Scheffel Boyle News
    • Professional Affiliations
    • Client Testimonials
    • Peer Review
    • Scheffel Boyle Shares
    • BDO Alliance USA
  • Services
    • Tax Planning & Preparation
    • Audit & Assurance
    • Accounting Services
    • Consulting Services
    • Financial Advisory
  • Clients & Industries
    • Construction
    • Financial Institutions
    • Agribusiness
    • Governmental Entities
    • Non-Profit Organizations
    • Privately-Held Businesses
    • Individual Clients
    • Employee Benefit Plans
  • Resources
    • Knowledge Center
    • Coronavirus Resource Center
    • Helpful Links
  • Careers
    • Benefits
    • Available Opportunities
    • College Students
  • Contact Us
    • Locations
      • Alton, IL
      • Belleville, IL
      • Carrollton, IL
      • Columbia, IL
      • Edwardsville, IL
      • Highland, IL
      • Jerseyville, IL
  • Click to open the search input field Click to open the search input field Search
  • Menu Menu
  • Link to Facebook
  • Link to LinkedIn

IRS Waives Estimated Penalty for Farmers and Fisherman, Extends to 4/15 Deadline

February 28, 2019

The IRS announced today that it will waive penalties for farmers and fishermen who do not meet the usual March 1st filing deadline. This essentially extends that federal deadline to April 15th for those qualifying taxpayers who in either tax year 2017 or 2018 received at least two-thirds of his or her total gross income from farming or fishing.

The IRS released a statement claiming the agency “is providing this relief because, due to certain rule changes, many farmers and fisherman may have difficulty accurately determining their tax liability by the March 1 deadline that usually applies to them.”

Further details can be found in Notice 2019-17 on IRS.gov. For questions concerning this news, please contact your local Scheffel Boyle office.

https://scheffelboyle.com/wp-content/uploads/2019/02/hay-field.jpg 1039 1600 brett@bonniburns.com https://scheffelboyle.com/wp-content/uploads/2022/06/Transparent-Logo-5.png brett@bonniburns.com2019-02-28 14:52:452020-01-28 15:24:39IRS Waives Estimated Penalty for Farmers and Fisherman, Extends to 4/15 Deadline

Introducing Jessie Beckemeyer!

February 25, 2019

We are excited to introduce a new member of our fantastic team, Jessie Beckemeyer. Jessie joins us as our Human Resources Coordinator and will be based out of the Edwardsville office.

Jessie received her undergraduate degree from Southern Illinois University Edwardsville in 2010 and went on to earn her Master of Science in Human Resource Management from Lindenwood University in 2018.

In addition to her position here at Scheffel Boyle, she also serves as the Vice President of Volunteer Coordination for the Mascoutah School District and is one of the only female pack leaders in our local area for Cub Scouts of America. She is originally from O’Fallon, Illinois and currently lives in Belleville with her husband and three young sons.

Welcome to the team, Jessie!


https://scheffelboyle.com/wp-content/uploads/2019/02/Beckemeyer-Jessica_top.jpg 1403 1159 brett@bonniburns.com https://scheffelboyle.com/wp-content/uploads/2022/06/Transparent-Logo-5.png brett@bonniburns.com2019-02-25 17:25:342020-01-28 15:25:00Introducing Jessie Beckemeyer!

There May Be Unclaimed Property With Your Name On It

February 25, 2019
It may sound too good to be true, but there may be valuable unclaimed property out there with your name on it. The term generally refers to financial assets being held for owners who haven’t been found. Just a few examples include uncashed dividend and payroll checks; unclaimed tax refunds; and insurance payments, refunds or policies with cash value.

If you’re interested in looking, there are search databases maintained by the state or states where you live and work, as well as states where you (or a deceased relative) previously lived and worked. Unclaimed property is sent to the state of the owner’s last known address.

Most states participate in MissingMoney.com, a free, national unclaimed property database. For states that don’t participate, you can find links to every state’s unclaimed property database on unclaimed.org, the website of the National Association of Unclaimed Property Administrators. You can also use this site to find links to relevant federal programs.

If you discover unclaimed property in your name, follow the instructions on the website where you found it. Typically, you’ll need to provide proof of ownership or, in the case of a deceased owner, a death certificate and proof that you’re entitled to the assets (such as a will).

Finally, be wary of companies that offer to locate and obtain property for a fee. Some of these offers are scams. But even if they’re legitimate, in most cases you can find and claim assets yourself for free or by paying a nominal handling fee.

Copyright © 2019

https://scheffelboyle.com/wp-content/uploads/2019/02/computer.jpeg 1500 2250 brett@bonniburns.com https://scheffelboyle.com/wp-content/uploads/2022/06/Transparent-Logo-5.png brett@bonniburns.com2019-02-25 11:57:402019-03-08 10:08:24There May Be Unclaimed Property With Your Name On It

Did You Repair Your Business Property or Improve It?

February 20, 2019
Repairs to tangible property, such as buildings, machinery, equipment or vehicles, can provide businesses a valuable current tax deduction — as long as the so-called repairs weren’t actually “improvements.”

The costs of incidental repairs and maintenance can be immediately expensed and deducted on the current year’s income tax return. But costs incurred to improve tangible property must be capitalized and recovered through depreciation.

Betterment, Restoration, or Adaptation

Generally, a cost must be depreciated if it results in an improvement to a building structure, or any of its building systems (for example, the plumbing or electrical system), or to other tangible property. An improvement occurs if there was a betterment, restoration or adaptation of the unit of property.

Under the “betterment test,” you generally must depreciate amounts paid for work that is reasonably expected to materially increase the productivity, efficiency, strength, quality or output of a unit of property or that is a material addition to a unit of property.

Under the “restoration test,” you generally must depreciate amounts paid to replace a part (or combination of parts) that is a major component or a significant portion of the physical structure of a unit of property.

Under the “adaptation test,” you generally must depreciate amounts paid to adapt a unit of property to a new or different use — one that isn’t consistent with your ordinary use of the unit of property at the time you originally placed it in service.

Safe Harbors

A couple of IRS safe harbors can help distinguish between repairs and improvements:

  1. Routine maintenance safe harbor. Recurring activities dedicated to keeping property in efficient operating condition can be expensed. These are activities that your business reasonably expects to perform more than once during the property’s “class life,” as defined by the IRS. Amounts incurred for activities outside the safe harbor don’t necessarily have to be depreciated, though. These amounts are subject to analysis under the general rules for improvements.
  2. Small business safe harbor. For buildings that initially cost $1 million or less, qualified small businesses may elect to deduct the lesser of $10,000 or 2% of the unadjusted basis of the property for repairs, maintenance, improvements and similar activities each year. A qualified small business is generally one with gross receipts of $10 million or less.

More to Learn

To learn more about these safe harbors and other ways to maximize your tangible property deductions, contact us.

Copyright © 2019

https://scheffelboyle.com/wp-content/uploads/2019/02/repair.jpeg 1500 2248 brett@bonniburns.com https://scheffelboyle.com/wp-content/uploads/2022/06/Transparent-Logo-5.png brett@bonniburns.com2019-02-20 11:47:282019-03-08 10:08:29Did You Repair Your Business Property or Improve It?

Deducting Charitable Gifts Depends on a Variety of Factors

February 16, 2019
Whether you’re planning to claim charitable deductions on your 2018 return or make donations for 2019, be sure you know how much you’re allowed to deduct. Your deduction depends on more than just the actual amount you donate.


What You Give

Among the biggest factors affecting your deduction is what you give. For example:

Cash or ordinary-income property. You may deduct the amount of gifts made by check, credit card or payroll deduction. For stocks and bonds held one year or less, inventory, and property subject to depreciation recapture, you generally may deduct only the lesser of fair market value or your tax basis.

Long-term capital gains property. You may deduct the current fair market value of appreciated stocks and bonds held for more than one year.

Tangible personal property. Your deduction depends on the situation. If the property isn’t related to the charity’s tax-exempt function (such as a painting donated for a charity auction), your deduction is limited to your basis. But if the property is related to the charity’s tax-exempt function (such as a painting donated to a museum for its collection), you can deduct the fair market value.

Vehicle. Unless the vehicle is being used by the charity, you generally may deduct only the amount the charity receives when it sells the vehicle.

Use of property or provision of services. Examples include use of a vacation home and a loan of artwork. Generally, you receive no deduction because it isn’t considered a completed gift. When providing services, you may deduct only your out-of-pocket expenses, not the fair market value of your services. You can deduct 14 cents per charitable mile driven.

Other Factors

First, you’ll benefit from the charitable deduction only if you itemize deductions rather than claim the standard deduction. Also, your annual charitable deductions may be reduced if they exceed certain income-based limits.

In addition, your deduction generally must be reduced by the value of any benefit received from the charity. Finally, various substantiation requirements apply, and the charity must be eligible to receive tax-deductible contributions.

Planning Ahead

For 2018 through 2025, the Tax Cuts and Jobs Act nearly doubles the standard deduction ― plus, it limits or eliminates some common itemized deductions. As a result, you may no longer have enough itemized deductions to exceed the standard deduction, in which case your charitable donations won’t save you tax.

You might be able to preserve your charitable deduction by “bunching” donations into alternating years, so that you’ll exceed the standard deduction and can claim a charitable deduction (and other itemized deductions) every other year.

The Years Ahead

Your charitable giving strategy may need to change in light of tax law reform or other factors. Let us know if you have questions about how much you can deduct on your 2018 return or what’s best to do in the years ahead.
Copyright © 2019

https://scheffelboyle.com/wp-content/uploads/2019/02/giving-hands.jpg 1500 2248 brett@bonniburns.com https://scheffelboyle.com/wp-content/uploads/2022/06/Transparent-Logo-5.png brett@bonniburns.com2019-02-16 11:33:302019-03-08 10:08:35Deducting Charitable Gifts Depends on a Variety of Factors

Weigh the Tax Impact of Income vs. Growth When Investing

February 12, 2019
As the 2018 tax-filing season heats up, investors have much to consider. Whether you structured your portfolio to emphasize income over growth — or vice versa, or perhaps a balance of the two — will have a substantial impact on your tax liability. Let’s take a look at a couple of the most significant “big picture” issues that affect income vs. growth.


Differing Dividends

One benefit of dividends is that they may qualify for preferential long-term capital gains tax rates. For the 2018 tax year, the top rate is 20% for high-income taxpayers (income of $425,800 or more). For those with incomes between $38,601 and $425,800, the rate is 15%. Individuals with incomes of $38,600 and below pay 0% on long-term capital gains.

Keep in mind, however, that only “qualified dividends” are eligible for these rates. Nonqualified dividends are taxed as ordinary income at rates as high as 37% for 2018. Qualified dividends must meet two requirements. First, the dividends must be paid by a U.S. corporation or a qualified foreign corporation. Second, the stock must be held for at least 61 days during the 121-day period that starts 60 days before the ex-dividend date and ends 60 days after that date.

A qualified foreign corporation is one that’s organized in a U.S. possession or in a country that has a current tax treaty with the United States, or whose stock is readily tradable on an established U.S. market. The ex-dividend date is the cutoff date for declared dividends. Investors who purchase stock on or after that date won’t receive a dividend payment.

Timing is Everything

One disadvantage of dividend-paying stocks (or mutual funds that invest in dividend-paying stocks) is that they accelerate taxes. Regardless of how long you hold the stock, you’ll owe taxes on dividends as they’re paid, which erodes your returns over time.

When you invest in growth stocks (or mutual funds that invest in growth stocks), you generally have greater control over the timing of the tax bite. These companies tend to reinvest their profits in the companies rather than pay them out as dividends, so taxes on the appreciation in value are deferred until you sell the stock.

Keeping an Eye Out

Regardless of your investment approach, you need to understand the tax implications of various investments so you can make informed decisions. You should also keep an eye on Congress. As of this writing, further tax law reform beyond the Tax Cuts and Jobs Act of 2017 isn’t on the horizon — but it’s being discussed. Contact our firm for the latest news and to discuss your tax and investment strategies.


Sidebar: What are your investment objectives?

When re-evaluating your investment portfolio, it’s important to consider whether your objectives have changed. There are many factors to consider, both tax and nontax. Some investors seek dividends because they need the current income or they believe that companies with a history of paying healthy dividends are better managed. Others prefer to defer taxes by investing in growth stocks. And, of course, there’s something to be said for a balanced portfolio that includes both income and growth investments. When preparing to file your 2018 taxes, take a moment to identify your objectives and determine if you met them or fell short.

Copyright © 2019

https://scheffelboyle.com/wp-content/uploads/2019/02/Investments.jpeg 1380 2520 brett@bonniburns.com https://scheffelboyle.com/wp-content/uploads/2022/06/Transparent-Logo-5.png brett@bonniburns.com2019-02-12 09:53:432019-03-08 10:08:41Weigh the Tax Impact of Income vs. Growth When Investing

We Have a New CPA!

February 6, 2019

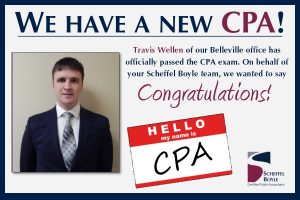
Congratulations to Belleville Semi-Senior Accountant Travis Wellen for officially passing the CPA Exam! We are so proud of you and cannot wait to see all you accomplish from here.

https://scheffelboyle.com/wp-content/uploads/2018/07/CPA-License.jpg 441 596 brett@bonniburns.com https://scheffelboyle.com/wp-content/uploads/2022/06/Transparent-Logo-5.png brett@bonniburns.com2019-02-06 10:33:382019-02-06 10:34:18We Have a New CPA!

Throwing Snowballs at Your Mountain of Debt

February 3, 2019
Many people start the year intending to get out of debt, yet end the year owing just as much, if not more. One approach that might yield success is called “throwing snowballs.”

Under this method, you organize your debts from the lowest balance to the highest balance and begin paying off the debt on top of the list. The idea is to throw as many “snowballs” as you can gather or earn at that first creditor until the debt is gone.

While you hurl these snowballs, pay the minimum amount to your other creditors. Avoid trying to send an extra $20 or so a month to each one. If you want to contribute extra money, throw it at your primary target.

Once the first debt is paid off, you should have even more money to send to the next one. Over time you can start heaving bigger and bigger snowballs at the remaining targets because, as you pay off each debt, you’ll have more money to pay toward remaining debts.

The objective is to start an avalanche of payoffs until your debts disappear. Under this method, the best predictor of success isn’t the number of dollars you pay off but rather the number of accounts that you close.

Please note: There’s some debate on the practicality of throwing snowballs. Opponents argue that you should first pay off debts with the highest interest rates. We can help you choose a debt-reduction strategy that’s right for you.

Copyright © 2019

https://scheffelboyle.com/wp-content/uploads/2019/01/credit-card.jpeg 1500 2250 brett@bonniburns.com https://scheffelboyle.com/wp-content/uploads/2022/06/Transparent-Logo-5.png brett@bonniburns.com2019-02-03 16:10:172019-03-08 10:08:47Throwing Snowballs at Your Mountain of Debt

You’ve Got Time: Small Businesses Can Still Set Up a 2018 SEP Plan

February 1, 2019
Are you a high-income small-business owner who doesn’t currently have a tax-advantaged retirement plan set up for yourself? A Simplified Employee Pension (SEP) plan may be just what you need, and now may be a great time to establish one.

A SEP plan has high contribution limits and is simple to set up. Best of all, there’s still time to establish one for 2018 and make contributions to it that you can deduct on your 2018 income tax return.

2019 Deadlines for 2018

A SEP plan can be set up as late as the due date (including extensions) of your income tax return for the tax year for which the plan is to first apply. That means you can establish a plan for 2018 in 2019 if you do it before your 2018 return filing deadline. You have until the same deadline to make 2018 contributions and still claim a potentially hefty deduction on your 2018 return.

Generally, other types of retirement plans would have to have been established by December 31, 2018, for 2018 contributions to be made (though many of these plans do allow 2018 contributions to be made in 2019).

High Contribution Limits

Contributions to SEP plans are discretionary. You can decide how much to contribute each year. But be aware that, if your business has employees other than you, 1) contributions must be made for all eligible employees using the same percentage of compensation as for you, and 2) employee accounts are immediately 100% vested. The contributions go into SEP-IRAs established for each eligible employee.

For 2018, the maximum contribution that can be made to a SEP-IRA is 25% of compensation (or 20% of self-employed income net of the self-employment tax deduction) of up to $275,000, subject to a contribution cap of $55,000. (The 2019 limits are $280,000 and $56,000, respectively.)

Simple to Set Up

A SEP plan is established by completing and signing the very simple Form 5305-SEP (“Simplified Employee Pension — Individual Retirement Accounts Contribution Agreement”). Form 5305-SEP isn’t filed with the IRS, but it should be maintained as part of the business’s permanent tax records. A copy of the form must be given to each employee covered by the plan, along with a disclosure statement.

Because of their simplicity and the great flexibility you have in making contributions, SEP plans are good “starter” retirement plans for small businesses. They’re also well suited for cash-flow dependent businesses such as construction companies, restaurants and seasonal businesses that may not always have dollars at the ready to contribute.

Less Onerous

Additional rules and limits do apply to these plans, but they’re generally much less onerous than those for other retirement plans. Contact us to learn more about SEP plans and how they might reduce your tax bill for 2018 and beyond.

Copyright © 2019

https://scheffelboyle.com/wp-content/uploads/2019/01/savings.jpeg 1500 2250 brett@bonniburns.com https://scheffelboyle.com/wp-content/uploads/2022/06/Transparent-Logo-5.png brett@bonniburns.com2019-02-01 16:00:242020-01-28 15:25:08You’ve Got Time: Small Businesses Can Still Set Up a 2018 SEP Plan

Pages

  • 2025 Seminar Registration
  • 2025 Seminar Registration Presentation Slides
  • 2026 Summer Sneak Peek
  • About Us
  • Accounting and Office Manager
  • Accounting Clerk
  • Accounting Services
  • Administrative Assistant
  • Administrative Assistant – Columbia Office
  • Administrative Assistant – Edwardsville Office
  • Administrative Support Specialist
  • Administrative Support Specialist
  • AGCI Webinar Presentation
  • Agribusiness
  • Alton, IL
  • Andrea Suhre
  • Andrea Suhre
  • Audit & Assurance
  • Available Opportunities
  • BDO Alliance USA
  • Belleville, IL
  • Bookkeeper
  • Bookkeeper/Payroll Specialist
  • Brian Otten
  • Business Valuations
  • Careers
  • Carrollton, IL
  • Columbia, IL
  • Construction Accounting
  • Construction Newsletter
  • Construction Tax Seminar Presentation
  • Consulting Services
  • Contact Us
  • Coronavirus Resource Center
  • Cory E. Gallivan
  • Crystal Bock
  • Crystal Bock
  • Dale Holtmann
  • Daniel Phipps
  • Data Entry Assistants
  • Dennis E. Ulrich
  • E-News Sign Up
  • Edwardsville, IL
  • Elements
  • Employee Benefit Plans
  • Experienced Accountants
  • Experienced Public Accountant
  • Financial Calculators
  • Financial Institution
  • FOCUS Internship Program
  • Full-Time Interview Sign-Up
  • George Moore
  • Governmental Entities
  • Heather Clugston
  • Helpful Links
  • Highland, IL
  • Home
  • Howard Held
  • Individual Clients
  • Industries
  • Interview Thank You
  • Interview Timeslots
  • IT Support Specialist
  • Jerseyville, IL
  • Julie Billeter
  • Julie Graham
  • Kathy Fitzgerald
  • Keith Brinkmann
  • Knowledge Center
  • Lisa Bohnenstiehl
  • Locations
  • Mark Korte
  • Marketing Specialist
  • Michael D. Ulrich
  • Michael E. Fitzgerald
  • Michael T. Brokering
  • Non-Profit Organizations
  • Office Accounting Assistant
  • Our Team
  • Outsourced Accountant
  • Part-Time Bookkeeper
  • Payroll Assistant
  • Payroll Supervisor
  • Peer Review
  • Privacy Policy
  • Privately-Held Businesses
  • Professional Affiliations
  • Recruiting Events
  • Recruiting/Human Resources Coordinator
  • Resources
  • Robyn M. Klingler
  • Russell Gregson
  • Sarah Smith
  • Scheffel Boyle News
  • Scheffel Boyle Shares
  • Scott Weber
  • Seasonal Tax Preparer
  • Services
  • SIBA Webinar Presentation
  • Sneak Peek Survey
  • Spring Tax Internship Program 2026
  • STL Ag Club Webinar Prez
  • Summer Audit Internship Program
  • Summer Audit Internship Program 2026
  • Tax Planning & Preparation
  • Tax Talks Information
  • Tax Talks Presentation
  • Testimonials
  • Webinar Presentation May 14
  • Welcome Email
  • Year-End Tax Planning Seminars
  • Accountant – Carrollton
  • Administrative Assistant – Alton Office
  • Administrative Assistant – Belleville Office
  • Administrative Assistant – Columbia Office
  • Seasonal Administrative Assistants
  • Seasonal Data Input
  • Staff Accountant

Categories

  • Blog
  • Construction
  • Coronavirus Resource Center
  • Frontpage
  • Knowledge Center
  • Scheffel News
  • Uncategorized

Archive

  • August 2026
  • May 2026
  • November 2025
  • October 2025
  • July 2025
  • February 2024
  • July 2023
  • May 2023
  • February 2023
  • January 2023
  • November 2022
  • August 2022
  • July 2022
  • June 2022
  • March 2022
  • February 2022
  • January 2022
  • December 2021
  • June 2021
  • May 2021
  • April 2021
  • March 2021
  • February 2021
  • January 2021
  • December 2020
  • November 2020
  • October 2020
  • September 2020
  • August 2020
  • July 2020
  • June 2020
  • May 2020
  • April 2020
  • March 2020
  • February 2020
  • January 2020
  • December 2019
  • November 2019
  • October 2019
  • September 2019
  • August 2019
  • July 2019
  • June 2019
  • May 2019
  • April 2019
  • March 2019
  • February 2019
  • January 2019
  • December 2018
  • November 2018
  • October 2018
  • September 2018
  • August 2018
  • July 2018
  • June 2018
  • May 2018
  • April 2018
  • March 2018
  • February 2018
  • January 2018
  • December 2017
  • November 2017
  • October 2017
  • September 2017
  • August 2017
  • July 2017
  • June 2017
  • May 2017
  • April 2017
  • March 2017
  • February 2017
  • January 2017
  • December 2016
  • October 2016
  • September 2016
  • August 2016
  • July 2016
  • May 2016
  • April 2016
  • March 2016
  • February 2016
  • January 2016
  • December 2015
  • November 2015
  • August 2015
  • July 2015
  • June 2015
  • February 2015
  • January 2015
  • December 2014
  • November 2014
  • September 2014
  • August 2014
  • March 2014
  • February 2014
  • December 2013
  • November 2013
  • October 2013
  • August 2013
  • July 2013
  • June 2013
  • May 2013
  • February 2013
  • January 2013

About Us


Serving St. Louis, the Metro-East and Southwestern Illinois since 1924.

Knowledge Center

  • New Rules Could Increase Taxable Income for GamblersAugust 24, 2026 - 3:20 pm
  • IRS Notice CP53E and the Rise of Refund-Related ScamsMay 18, 2026 - 9:55 am
  • Potential Refund Deadline Extensions Under the Kwong CaseMay 7, 2026 - 11:40 am

Quick Links

  • Services
  • Clients & Industries
  • Our Team
  • Scheffel Boyle News
  • Careers

 Contact Us

Alton, IL: 618.465.4288
Edwardsville, IL: 618.656.1206
Belleville, IL: 618.277.8100
Highland, IL: 618.654.9895
Jerseyville, IL: 618.498.6841
Columbia, IL: 618.281.7605
Carrollton, IL: 217.942.3821

© Copyright 2021 Scheffel Boyle — All rights reserved
  • Site Map
  • Privacy Policy
Scroll to top Scroll to top Scroll to top