Loading
Scheffel Boyle
  • Home
  • About Us
    • Our Team
    • Our Values
    • Scheffel Boyle News
    • Professional Affiliations
    • Client Testimonials
    • Peer Review
    • Scheffel Boyle Shares
    • BDO Alliance USA
  • Services
    • Tax Planning & Preparation
    • Audit & Assurance
    • Accounting Services
    • Consulting Services
    • Financial Advisory
  • Clients & Industries
    • Construction
    • Financial Institutions
    • Agribusiness
    • Governmental Entities
    • Non-Profit Organizations
    • Privately-Held Businesses
    • Individual Clients
    • Employee Benefit Plans
  • Resources
    • Knowledge Center
    • Coronavirus Resource Center
    • Helpful Links
  • Careers
    • Benefits
    • Available Opportunities
    • College Students
  • Contact Us
    • Locations
      • Alton, IL
      • Belleville, IL
      • Carrollton, IL
      • Columbia, IL
      • Edwardsville, IL
      • Highland, IL
      • Jerseyville, IL
  • Click to open the search input field Click to open the search input field Search
  • Menu Menu
  • Link to Facebook
  • Link to LinkedIn

Announcing 2021 Promotions

January 7, 2022

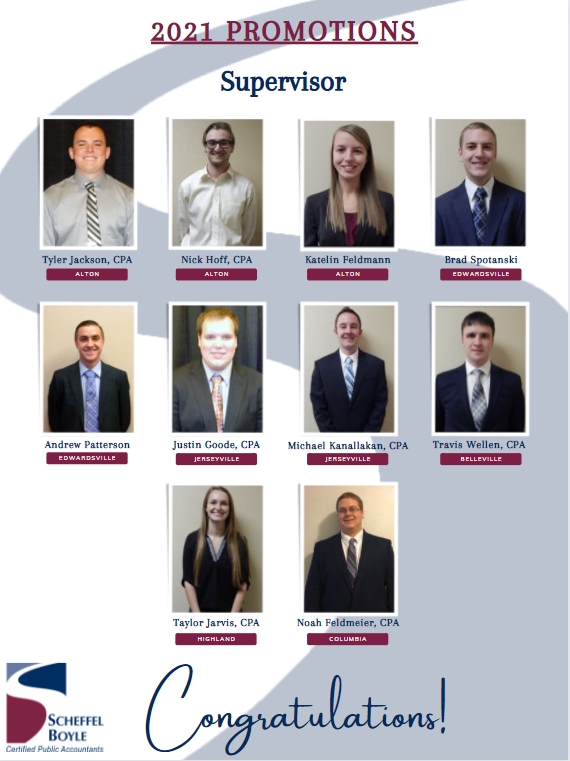
We are pleased to announce the recent promotion of 27 professionals throughout our 7 offices! On behalf of our firm, we would like to wish all those who were promoted the best of luck in their new roles.

Supervisor: Tyler Jackson, Nick Hoff, Katelin Feldmann, Brad Spotanski, Andrew Patterson, Justin Goode, Michael Kanallakan, Travis Wellen, Taylor Jarvis & Noah Feldmeier

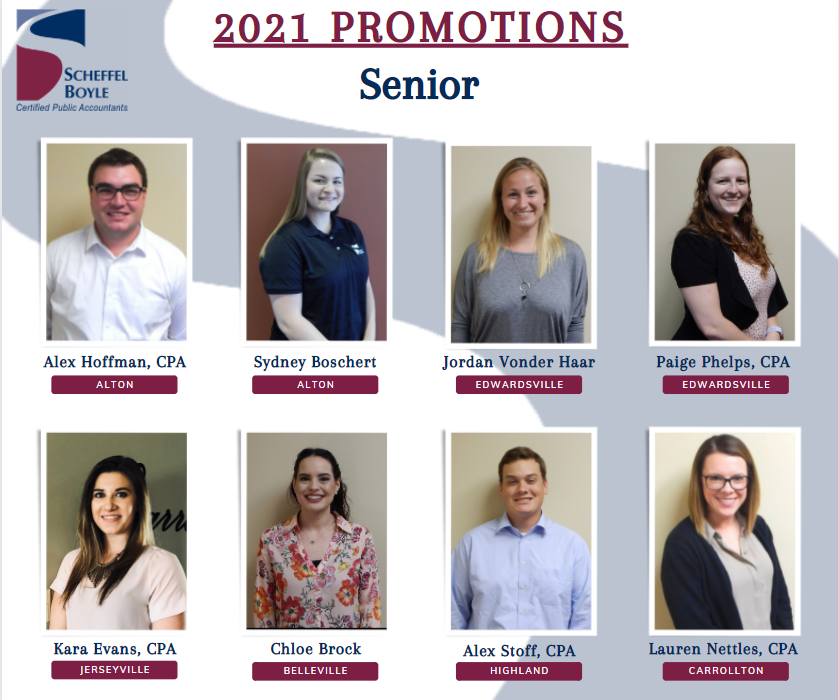
Senior: Alex Hoffman, Sydney Boschert, Jordan Vonder Haar, Paige Phelps, Kara Evans, Chloe Brock, Alex Stoff & Lauren Nettles

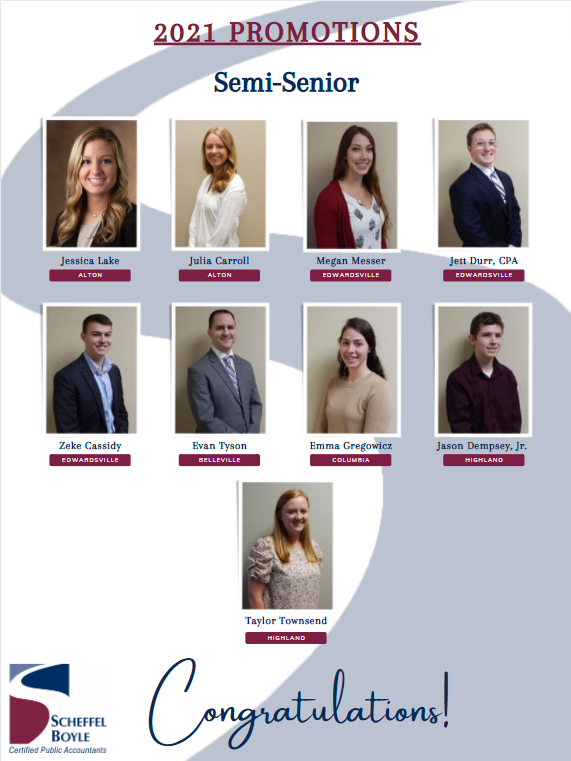
Semi-Senior: Jessica Lake, Julia Carroll, Megan Messer, Jett Durr, Zeke Cassidy, Evan Tyson, Emma Gregowicz, Jason Dempsey Jr. & Taylor Townsend

https://scheffelboyle.com/wp-content/uploads/2022/01/2021-Supervisors.png 761 570 Suzi Seaton https://scheffelboyle.com/wp-content/uploads/2022/06/Transparent-Logo-5.png Suzi Seaton2022-01-07 09:58:472022-01-07 10:38:21Announcing 2021 Promotions

Announcing 3 New Principals

January 7, 2022

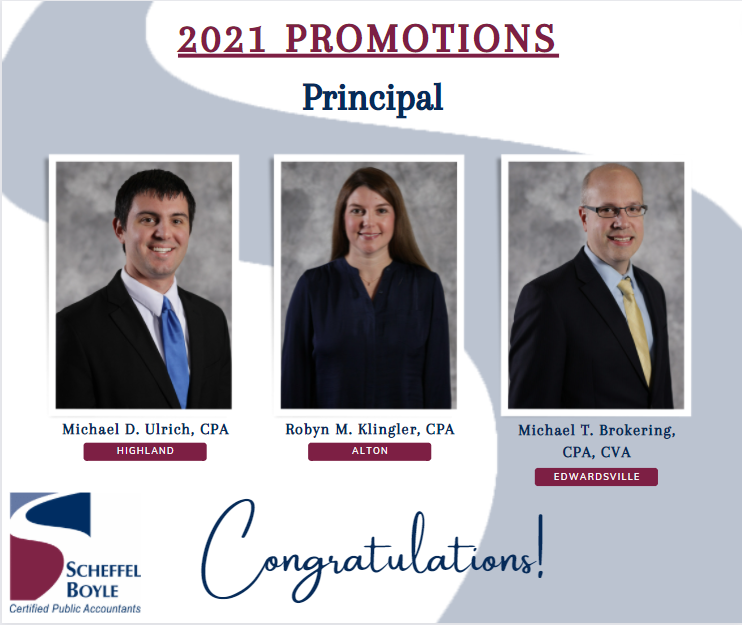
Congratulations to our 3 recently promoted principals!

HIGHLAND – Scheffel Boyle CPAs is pleased to announce the promotion of Michael D. Ulrich, CPA to Principal. Michael joined the company in 2010. He is a senior leader on the Agribusiness Team, and also specializes in accounting and tax services for construction and privately held businesses.

Michael graduated with both his B.S. and M.S.A. from Southern Illinois University Edwardsville and earned his CPA designation in 2010. He is active in the St. Louis Agribusiness Club, Equipment Dealers Association, SIBA, and AGC, as well as in his local community of Highland, Illinois.


ALTON – Scheffel Boyle CPAs is pleased to announce the promotion of Robyn M. Klingler, CPA to Principal. Robyn joined the firm’s Alton office in 2003. She is a valuable member of our A&A Quality Control Team and specializes in audit and assurance practices, particularly for governmental clients, school districts, and for-profit entities. Robyn is also responsible for providing in-house training and continuing education for our team.

Robyn graduated with her B.S. from the University of Illinois and earned her CPA designation in 1998. She is a recipient of the Carrollton High School Alumnus Award and a well-respected member of her local community of Carrollton, Illinois.


EDWARDSVILLE – Scheffel Boyle CPAs is pleased to announce the promotion of Michael T. Brokering, CPA, CVA to Principal. Michael joined the firm’s Edwardsville office in October 2012. He is a senior leader on the Business Valuation Team, and also specializes in accounting and tax services for employee benefit plans, governmental and nonprofit agencies, and a variety of privately held businesses.

Michael graduated with his B.S. from Southern Illinois University Edwardsville and earned his CPA designation in 1999 and his Certified Valuation Analyst (CVA) designation in 2007. He is active in the Edwardsville/Glen Carbon Chamber of Commerce and various other local organizations.

https://scheffelboyle.com/wp-content/uploads/2022/01/2021-Principals.png 625 742 Suzi Seaton https://scheffelboyle.com/wp-content/uploads/2022/06/Transparent-Logo-5.png Suzi Seaton2022-01-07 09:41:142022-01-07 16:35:32Announcing 3 New Principals

Two Important IRS Letters to be Sent this Month

January 6, 2022

If you were eligible for the third stimulus check or the advanced child tax credit payments in 2021, you need to be on the lookout for two letters from the IRS. They will be arriving by the end of January 2022.


2021 Economic Impact Payment (Third Stimulus Check)

People who received the third stimulus check will receive Letter 6475 from the IRS.

This will help them determine what the taxpayer received and if they qualify for the Recovery Rebate Credit on their 2021 tax returns.

“Letter 6475 only applies to the third round of Economic Impact Payments that was issued starting in March 2021 and continued through December 2021,” the IRS said on its website.


Advance Child Tax Credit Payment

Families who received advance child tax credit payments in 2021 will receive Letter 6419 from the IRS.

This letter will tell eligible families how much of the credit they have received so far and the number of qualifying children that was used to calculate that amount. From this, the taxpayer will be able to determine out how much of a tax credit to claim on their tax returns this year.

Monthly payments that were sent to millions of families with eligible children from July to December only accounted for half of the credit. Now, those who got the money need to show what they received to make sure they get any remaining credit on their 2021 tax return if applicable.

If taxpayers don’t receive the letter, they can also go to the IRS CTC Update Portal to see how much they’ve received.

As of right now, the monthly advance child tax credit payments are not set to continue in 2022.

If you receive these letters, please hold on to them and provide them to your tax preparer with your other 2021 tax documents.


If you have any questions, please feel free to contact your trusted Scheffel Boyle team member. We are always here to help!

https://scheffelboyle.com/wp-content/uploads/2022/01/Capture.png 624 742 Suzi Seaton https://scheffelboyle.com/wp-content/uploads/2022/06/Transparent-Logo-5.png Suzi Seaton2022-01-06 11:44:112022-01-06 11:44:11Two Important IRS Letters to be Sent this Month

Tax Deadline Extension & IL Pass-Through Entity Tax to Avoid SALT Limit

December 29, 2021

Tax Deadline Extension

On December 20, 2021, the IRS announced an extension of the tax deadline to May 16, 2022, for taxpayers in certain counties. This includes the filing of individual and business tax returns along with their estimated tax payments. This relief is being granted to taxpayers affected by the devastating storms that took place on December 10 in many parts of Illinois. This relief is currently available for the following counties: Bond, Cass, Coles, Effingham, Fayette, Jersey, Macoupin, Madison, Menard, Montgomery, Morgan, Moultrie, Pike, and Shelby. The original filing deadline for 2021 individual tax returns was April 18, 2022. The original due date for business tax returns was March 15, 2022, and April 18, 2022. The due date is now May 16, 2022, for both individual and business returns to be filed by taxpayers with an IRS address of record in the above counties. This also means taxpayers in the affected counties will have until May 16, 2022, to make 2021 IRA contributions. The quarterly income tax payments originally due on January 18, 2022, and April 18, 2022, are now also due on May 16, 2022. Also, farmers who choose to forgo making estimated tax payments and normally file their returns by March 1, 2022, will now have until May 16, 2022, to file their 2021 tax return and pay any tax due.

The IRS automatically provides this filing and penalty relief to anyone with an IRS address of record located in the counties listed above. There is no need to contact anyone to get this relief.


Illinois Pass-Through Entity Tax to Avoid SALT Limit

In 2017, the Tax Cuts and Job Act limited state and local income taxes paid by individuals, whether from pass-through entity income or other income to a SALT (State and Local Tax) cap of $10,000. Several states, including Illinois, enacted a pass-through tax to be paid at the entity level and credited at the individual level as a workaround to the federal SALT limit. The IRS recently released guidance approving these state workarounds.

An election is made by the partnership or S corporation for the Illinois pass-through entity (PTE) tax and estimated payments are required. An election may be made each year and is irrevocable for the year made. If you decide to elect the PTE tax, the partnership or S corporation is not required to withhold income tax on the partners that do not reside in the state of the partnership or S corporation. This allows a partner or shareholder to deduct Illinois tax on the business income in full on the federal return. This will benefit taxpayers who itemize and are subject to the $10,000 SALT limit and those who do not itemize.

Until further guidance is issued, we are recommending that the IL pass-through entity tax be paid on or before 12/31/21 in order to claim a deduction on the partner’s or shareholder’s tax return.  This payment may be made using a payment voucher or through MyTax Illinois.

Shareholders of the S corporation and partners of the Partnership are allowed a refundable credit for the PTE tax paid by the pass-through entity. Those partners and shareholders must add their distributive share of the PTE tax back to their Illinois income. The tax liability at the partner level will then equal the PTE tax paid at the entity level.


Our team will continue to monitor the status of these and any other tax laws that change. Please contact your trusted Scheffel Boyle team member with questions. We are always here to help!
https://scheffelboyle.com/wp-content/uploads/2021/12/tax-deadline-1.jpg 667 1000 Suzi Seaton https://scheffelboyle.com/wp-content/uploads/2022/06/Transparent-Logo-5.png Suzi Seaton2021-12-29 13:24:182022-01-07 09:47:37Tax Deadline Extension & IL Pass-Through Entity Tax to Avoid SALT Limit

Biden Administration’s Tax Blueprint

June 18, 2021

TREASURY’S GREEN BOOK PROVIDES DETAILS ON ADMINISTRATION’S TAX BLUEPRINT


The Treasury Department on May 28 released its general explanation of tax proposals included in the Biden administration’s fiscal year 2022 budget submission to Congress. Commonly known as the “Green Book,” the 114-page document provides more details regarding the administration’s tax proposals that had been previewed in the American Jobs Plan and the American Families Plan.

The Green Book lays out the administration’s priorities in paying for proposed spending plans. We want to emphasize that this is not tax law. These are simply proposals for how the administration would like to pay for certain items.

A look at some of the administration’s tax proposals follows.

Individual Income Tax Rate
The top marginal individual income tax rate would increase from 37% to 39.6%. For taxable year 2022, the rate would apply to taxable income over $509,300 for married individuals filing jointly ($254,650 for married individuals filing separately), $481,000 for head of household filers, and $452,700 for single filers.  The proposed increase would be effective for taxable years beginning after December 31, 2021.

Capital Gain and Qualified Dividend Income

Long-term capital gains and qualified dividend income of taxpayers with adjusted gross income of more than $1 million would be taxed at ordinary income tax rates to the extent that the taxpayer’s income exceeds $1 million ($500,000 for married individuals filing separately). If the proposal for raising the ordinary income tax rate to 39.6 % becomes law, then the maximum tax rate of capital gains would be 43.4% (39.6% plus net investment income tax rate of 3.8%). The proposed effective date would be for gains required to be recognized after the date of announcement, which is understood to be April 28, 2021, the date of President Biden’s first address to a joint session of Congress during which he introduced the American Families Plan.

Transfers of Appreciated Property

Taxpayers transferring appreciated property during certain events would realize a capital gain based on the property’s fair market value at the time of the transfer. The proposal generally would be effective January 1, 2022. Recognition events include:

  • Gifts
  • Death
  • Transfers of in-kind property to trusts (other than wholly revocable trusts)
  • Distributions of in-kind property from a trust (other than to the grantor owner of a revocable trust or to a spouse of the grantor, as long as the distribution is not in discharge of an obligation of the deemed grantor owner)
  • Terminations of revocable grantor trusts – at death or during life
  • Transfers of in-kind property to partnerships or other non-corporate entities
  • Distributions of in-kind property from partnerships or other non-corporate entities
  • Holdings of trusts, partnerships or other non-corporate entities, when the property has not had a recognition event within the prior 90 years, measured as of January 1, 1940. The first recognition event under this 90-year rule would occur December 31, 2030.

The “deemed” gain would be taxable income to the donor or to the decedent. The amount of gain would be measured by the amount that the fair market value of the appreciated property exceeds the basis on the date of the gift or upon the date of death, whichever is applicable. The use of capital losses and carry-forwards from transfers at death would be permitted on the decedent’s final income tax return.

The proposal allows for some exclusions. Transfers by a decedent to a U.S. spouse would not be a taxable event, and the surviving spouse would receive the decedent’s carryover basis. The surviving spouse would recognize the gain upon disposition or death. Transfers to charity would not generate a taxable capital gain. Transfers to a split interest trust, such as a charitable remainder trust, would generate a gain with an exclusion allowed for the charity’s share of the gain. Transfers of tangible personal property, such as household furnishings and personal effects (excluding collectibles), are excluded. The exclusion for small business stock would still apply.

The proposal would allow a $1 million per person exclusion from recognition of gain on properties transferred by gift or held at death. Any unused exemption by a deceased spouse will port to the surviving spouse making the exclusion effectively $2 million per couple. Generally, the cost basis to the transferee will be the fair market value of the property transferred. A donee receiving property that qualified for the $1 million exclusion of the donor will have a carryover basis.

Payment of the tax on the appreciation of certain family owned and operated businesses would not be due until the business was sold or ceases to be family owned and operated. The capital gains tax on appreciated property transferred at death will be eligible for a 15-year fixed rate payment plan. However, publicly traded financial assets will not be eligible for the payment plan. Furthermore, family businesses electing the deferral will not be eligible for the payment plan. Transfers to S corporations and C corporations do not appear to generate gain, assuming those transfers qualify for the deferral provisions of Section 351.

Gain from Like-Kind Exchanges

Gains in excess of $500,000 ($1 million for married individuals filing jointly) from like-kind exchanges of real estate would be taxed in the year the property is transferred. Deferral of gain only up to $500,000 for each taxpayer ($1 million for married individuals filing jointly), each year, from like-kind exchanges of real estate would be allowed. The proposed effective date would be for exchanges completed in taxable years beginning after December 31, 2021.

Prospects of Tax Legislation

Although the White House, House of Representatives and Senate are each in Democratic hands, the path to enacting tax legislation remains unclear.

Some of these proposed changes are time sensitive and would require action in 2021.  This means taxpayers will need to begin planning to be positioned to act quickly if/when these proposals become law.

Our team will continue to monitor the status of these and any other tax laws that change. Please contact your trusted Scheffel Boyle team member with questions. We are always here to help!
https://scheffelboyle.com/wp-content/uploads/2021/04/Blog-Social-Security-Benefits.png 1056 1548 brett@bonniburns.com https://scheffelboyle.com/wp-content/uploads/2022/06/Transparent-Logo-5.png brett@bonniburns.com2021-06-18 15:35:152021-06-18 15:35:15Biden Administration’s Tax Blueprint

Appreciating the Helpful Balance of Bonds

May 3, 2021

Stock market swings may bring fortune or fear, so investors shouldn’t forget about the helpful balance of bonds. Perhaps the most “user friendly” is a U.S. government savings bond. Buying one means you’re essentially lending the federal government money at a certain interest rate in exchange for a future return. U.S. savings bonds don’t offer as high a yield as other investment instruments, but they’re highly stable. Interest on U.S. government bonds is taxable on federal income tax returns, but it’s often exempt on state and local returns.

Another government investment option is a Treasury bill. These are short-term government securities with maturities ranging from a few days to 52 weeks. For a more long-term option, look into Treasury notes. These government securities are generally issued with maturities of two, three, five, seven and 10 years and pay interest every six months.

If you’re looking to preserve capital while generating some tax-free income, consider a tax-exempt state or municipal bond. Here you lend money to a more localized government entity in exchange for regular payments. Keep in mind that interest may be taxable on state and local returns.

There are corporate bonds as well. These generally offer a higher yield than their federal or municipal counterparts, but there’s greater risk in terms of price fluctuation because of market interest rate changes and even default by the issuer. Plus, you’ll need to anticipate the tax implications. Interest from corporate bonds is subject to federal and state income tax. Plus, as with other types of bonds, you could incur capital gains if you sell the bond at a profit before it matures.

https://scheffelboyle.com/wp-content/uploads/2021/04/Blog-Appreciating-the-helpful-balance-of-bonds.png 704 1032 brett@bonniburns.com https://scheffelboyle.com/wp-content/uploads/2022/06/Transparent-Logo-5.png brett@bonniburns.com2021-05-03 14:56:192021-05-03 14:56:19Appreciating the Helpful Balance of Bonds

3 Things to Know After Filing Your Tax Return

May 3, 2021

3 things to know after filing your tax return

Most people feel a sense of relief after filing their tax returns. But even if you’ve successfully filed your 2020 return with the IRS, there may still be some issues to bear in mind. Here are three important things to know:

  1. You can check on your refund. The IRS has an online tool that can tell you the status of your refund. Go to irs.gov and click on “Get Your Refund Status.” You’ll need your Social Security number, filing status and the exact refund amount.
  2. You can file an amended return if you forgot to report something. In general, you can file an amended tax return and claim a refund within three years after the date you filed your original return or within two years of the date you paid the tax, whichever is later. So, if you filed your 2020 tax return on April 15, 2021, you would typically have until April 15, 2024, to file an amended return.However, there are a few opportunities when you have longer to file an amended return. For example, the statute of limitations for bad debts is longer than the usual three-year time limit for most items on your tax return. In general, you can amend your tax return to claim a bad debt for seven years from the due date of the tax return for the year that the debt became worthless.
  1. You can throw out some tax records. You should keep tax records related to your return for as long as the IRS can audit your return or assess additional taxes. The statute of limitations is generally three years after you file your return.That means you can probably dispose of most tax-related records for the 2017 tax year and earlier years. (If you filed an extension for your 2017 return, hold on to your records until at least three years from when you filed the extended return.) However, the statute of limitations extends to six years for taxpayers who understate their gross income by more than 25%.You’ll need to hang on to certain tax-related records longer. For example, keep actual tax returns indefinitely so you can prove to the IRS that you filed legitimately. (There’s no statute of limitations for an audit if you didn’t file a return or you filed a fraudulent one.)

    Keep records associated with retirement accounts until you’ve depleted the account and reported the last withdrawal on your tax return, plus three (or six) years. And retain records related to real estate or investments for as long as you own the asset, plus at least three years after you sell it and report the sale on your tax return. (You can keep these records for six years if you want to be extra safe.)

Always available

Contact us if you have further questions about your refund, filing an amended return or record retention. We’re here all year!

https://scheffelboyle.com/wp-content/uploads/2021/04/Blog-3-things-to-know-after-filing-your-tax-return.png 704 1032 brett@bonniburns.com https://scheffelboyle.com/wp-content/uploads/2022/06/Transparent-Logo-5.png brett@bonniburns.com2021-05-03 14:56:172021-05-03 14:56:173 Things to Know After Filing Your Tax Return

The Tax Treatment of Start-up Expenses

May 3, 2021

With the economy expected to improve in the months or quarters ahead, many business owners and entrepreneurs may decide to launch new enterprises. If you’re among them, be aware that the way you handle some of your initial expenses can make a large difference in your tax bill.

General rules

Start-up costs include those incurred or paid while creating an active trade or business — or investigating the creation or acquisition of one. Under the Internal Revenue Code, taxpayers can deduct up to $5,000 of business start-up and $5,000 of organizational costs in the year the business begins.

As you know, $5,000 doesn’t get you very far today! And the $5,000 deduction is reduced dollar-for-dollar by the amount by which your total start-up or organizational costs exceed $50,000. Any remaining costs must be amortized over 180 months on a straight-line basis.

In addition, no deductions or amortization deductions are allowed until the year when “active conduct” of your new business begins. Generally, that means the year when the business has all the pieces in place to begin earning revenue. To determine whether a taxpayer meets this test, the IRS and courts generally ask questions such as: Did the taxpayer undertake the activity intending to earn a profit? Was the taxpayer regularly and actively involved? Did the activity actually begin?

Applicable expenses

In general, start-up expenses include all amounts you spend to investigate creating or acquiring a business, launching the enterprise, or engaging in a for-profit activity while anticipating the activity will become an active business.

To be eligible for the election, an expense also must be one that would be deductible if it were incurred after a business began. One example is money you spend analyzing potential markets for a new product or service.

To qualify as an “organization expense,” the expenditure must be related to creating a corporation or partnership. Some examples of organization expenses are legal and accounting fees for services related to organizing a new business and filing fees paid to the state of incorporation.

Thinking ahead

If you have start-up expenses that you’d like to deduct this year, you need to decide whether to take the elections described above. Recordkeeping is critical. Contact us about your start-up plans. We can help with the tax and other aspects of your new business.

https://scheffelboyle.com/wp-content/uploads/2021/04/Blog-The-Tax-Treatment-of-Start-Up-Expenses.png 704 1032 brett@bonniburns.com https://scheffelboyle.com/wp-content/uploads/2022/06/Transparent-Logo-5.png brett@bonniburns.com2021-05-03 14:56:152021-05-03 14:56:15The Tax Treatment of Start-up Expenses

Bolster Wealth Management with Trusts

May 3, 2021

Trusts can be a useful tool for affluent individuals and families when it comes to wealth management, protection and growth. But there are a wide variety to choose from, so it’s important to clearly understand the benefits and limits of a trust before choosing any one type.

What’s a trust?

A trust is a legal document that dictates how an individual’s assets will be managed for another person’s (or other people’s) benefit(s). There are usually three parties to a trust: the grantor who creates the trust, the beneficiary (or beneficiaries) who’ll benefit from the trust and the trustee(s) who’ll manage the assets according to the trust’s terms and in the beneficiary’s best interests.

All trusts fall into one of two broad categories: living trusts and testamentary trusts. Living trusts are set up during an individual’s lifetime to transfer property to the trust. Testamentary trusts are established as part of an individual’s will and take effect after he or she dies.

Living trusts can be further categorized as revocable and irrevocable. With a revocable trust, the grantor retains control of the trust’s assets and can revoke or change its terms at any time. With an irrevocable trust, the grantor no longer owns the assets and, thus, can’t make changes to the trust without the beneficiary’s consent.

How can one protect you?

Individuals looking to manage their wealth in a patient and prudent manner can achieve various financial and estate planning goals from a trust, depending on its type. For example, many affluent individuals, professionals and business owners use a Delaware statutory trust to protect their assets from a loss resulting from a legal judgment, such as malpractice or personal injury liability. A Delaware trust also can be used instead of a prenuptial agreement by a spouse to preserve his or her assets in case of a divorce.

When establishing a Delaware trust, you transfer the assets you want to protect to an irrevocable trust — these assets can include cash, business ownership interests, real estate, and securities like stocks and bonds. These assets generally will be protected from future creditors. Although you must give up some control of the assets when you place them in the trust, you can retain some powers, such as the right to direct the investment of trust assets and to receive income and principal distributions from the trust.

A trust with a funny name

If one of your professional advisors suggests creating a trust that’s “intentionally defective,” you might consider hanging up the phone. However, despite its funny name, an intentionally defective grantor trust is a completely valid way to minimize gift and estate taxes when transferring certain assets, such as an ownership interest in a closely held business, to the next generation.

The key is that contributions of ownership interest to the trust must be considered gifts. This removes the assets and their future appreciation from your taxable estate. The trust’s income is taxable to you, not your heirs. As a result, trust assets can grow unencumbered by income taxes, which increases the amount of wealth your heirs may receive upon your passing.

Who can help?

There are many other trust types to consider. The rules for establishing and maintaining any trust can be complex, so please contact our firm for guidance.

https://scheffelboyle.com/wp-content/uploads/2021/04/Blog-Bolster-Wealth-Management-with-Trusts-1.png 704 1032 brett@bonniburns.com https://scheffelboyle.com/wp-content/uploads/2022/06/Transparent-Logo-5.png brett@bonniburns.com2021-05-03 14:53:492021-05-03 14:53:49Bolster Wealth Management with Trusts

U.S. Small Business Administration Awarding Funding Through the Restaurant Revitalization Funding Program

April 28, 2021

On March 11, 2021, the American Rescue Plan Act (ARPA) was announced as public law (P.L. 117-2) Section 5003, which appropriated $28.6 billion for the U.S. Small Business Administration (SBA) to award as funding to restaurants, bars, and other similar places of business that serve food or drink. Recipients are not required to repay the funding as long as funds are used for eligible uses no later than March 11, 2023.

Who is Eligible?

Eligible entities are businesses not permanently closed and include businesses where the public or patrons assemble for the primary purpose of being served food or drinks. Some examples include restaurants, food stands, food trucks, food carts, caterers, bars, saloons, lounges, taverns, and snack/nonalcoholic beverage bars. Bakeries, brewpubs, tasting rooms, taprooms, breweries, microbreweries, wineries, and distilleries must show documentation with their application that on-site sales to the public comprised at least 33% of gross receipts in 2019. Restaurants and bars also need to meet this 33% test, but do not appear to have a requirement to submit documentation with their application.

Per the SBA Program Guide (as of April 20, 2021), “Those entities without additional documentation requirements, such as restaurants and bars, are presumed to have on-site sales to the public comprising at least 33% of gross receipts in 2019. All applicants must attest in the application to the following: “The Applicant is eligible to receive funding under the rules in effect at the time this application is submitted.””

Where to Apply

The SBA is providing three ways of applying for the funding:

  1. Through an SBA recognized Point of Sale Restaurant Partners
  2. Directly through SBA Form 3172
  3. By calling SBA directly at (844) 279-8898

Currently the SBA has set registration for the application portal to begin on Friday, April 30, 2021, at 9:00 a.m. ET and application will open on Monday, May 3, 2021, at noon ET.

When to Apply

The SBA will start accepting applications from eligible participants after the pilot program has ended. The application process will be open to all who are eligible to receive funding, but for the first 21 days they will only process and fund those in the priority groups. The priority group is defined as those who are at least 51 percent owned and controlled by individuals who are women, veterans, and/or socially and economically disadvantaged individuals. After the initial 21-day period, the SBA will begin to process applications for all eligible participants.

The funding is on a first come, first serve basis, and the SBA has stressed the importance of applying as soon as possible as demand may exceed available funding. 

Funding Amounts

The funding amounts for eligible participants are as follows:

  • Calculation 1: For applicants in operation prior to or on January 1, 2019.
    • 2019 gross receipts minus 2020 gross receipts minus PPP loan Amounts
  • Calculation 2: For Applicants that began operations partially through 2019.
    • (Average 2019 Monthly gross receipts x 12) Minus 2020 gross receipts minus PPP Loan Amounts
  • Calculation 3: For Applicants that began operations on or between January 1, 2020 and March 10, 2021 and applicants not yet opened but will have eligible expenses incurred.
    • Amount Spent on eligible expenses between February 15, 2020 and March 11, 2021 minus 2020 Gross receipts minus 2021 gross receipts (through March 11, 2021) minus PPP loan amounts

Gross receipts for the purpose of this program does not include:

  • Amounts received from Paycheck Protection Program (PPP) Loans (First draw or Second draw)
  • Amounts received from Economic Injury Disaster Loans or Grants
  • State and Local grants (via CARES Act or otherwise)
  • SBA Section 1112 payments

Allowable Use of Funds

Funds may be used for specific expenses including business payroll costs, payments on any business mortgage obligation, business rent payments, business debt services, business utility payments, business maintenance expenses, construction of outdoor seating, business supplies, business food and beverage expenses, covered supplier costs, and business operating expenses.

Documentation Required

For all applicants, a completed SBA Form 3172, verification of tax information IRS Form 4506-T and gross receipts documentation which includes but not limited to tax returns, bank statements, etc.

In Summary

The SBA is awarding funding for those eligible applicants that have been affected by the COVID-19 pandemic. Participants will be required to report, no later than December 31, 2021, via the application portal, how much of the grant has been spent on each category of eligible use of funds. Click on the links below access the SBA RRF Program Guide and RRF Sample Application:

  • SBA RRF Program Guide
  • Restaurant Revitalization Funding Sample Application

It is indicated in the American Rescue Plan that amounts received from SBA in the form of a Restaurant Revitalization Funding grant shall not be included in the gross income of the entity that receives such funds. In addition, no deduction shall be denied, no tax attribute shall be reduced, and no basis increase shall be denied by reason of the exclusion from gross income provided above.

How We Can Help

Our team is available to assist you during the process of filing for the SBA Restaurant Revitalization Funding. We will update you with any changes to the program or application when released by the SBA. Please contact your trusted Scheffel Boyle team member with questions. We are always here to help!
https://scheffelboyle.com/wp-content/uploads/2021/04/Blog-SBA-Restaurant-Revitalization-Funding-Program.png 1056 1548 brett@bonniburns.com https://scheffelboyle.com/wp-content/uploads/2022/06/Transparent-Logo-5.png brett@bonniburns.com2021-04-28 15:55:052021-04-29 08:50:52U.S. Small Business Administration Awarding Funding Through the Restaurant Revitalization Funding Program
Page 4 of 32«‹23456›»

Pages

  • 2025 Seminar Registration
  • 2025 Seminar Registration Presentation Slides
  • 2026 Summer Sneak Peek
  • About Us
  • Accounting and Office Manager
  • Accounting Clerk
  • Accounting Services
  • Administrative Assistant
  • Administrative Assistant – Columbia Office
  • Administrative Assistant – Edwardsville Office
  • Administrative Support Specialist
  • Administrative Support Specialist
  • AGCI Webinar Presentation
  • Agribusiness
  • Alton, IL
  • Andrea Suhre
  • Andrea Suhre
  • Audit & Assurance
  • Available Opportunities
  • BDO Alliance USA
  • Belleville, IL
  • Bookkeeper
  • Bookkeeper/Payroll Specialist
  • Brian Otten
  • Business Valuations
  • Careers
  • Carrollton, IL
  • Columbia, IL
  • Construction Accounting
  • Construction Newsletter
  • Construction Tax Seminar Presentation
  • Consulting Services
  • Contact Us
  • Coronavirus Resource Center
  • Cory E. Gallivan
  • Crystal Bock
  • Crystal Bock
  • Dale Holtmann
  • Daniel Phipps
  • Data Entry Assistants
  • Dennis E. Ulrich
  • E-News Sign Up
  • Edwardsville, IL
  • Elements
  • Employee Benefit Plans
  • Experienced Accountants
  • Experienced Public Accountant
  • Financial Calculators
  • Financial Institution
  • FOCUS Internship Program
  • Full-Time Interview Sign-Up
  • George Moore
  • Governmental Entities
  • Heather Clugston
  • Helpful Links
  • Highland, IL
  • Home
  • Howard Held
  • Individual Clients
  • Industries
  • Interview Thank You
  • Interview Timeslots
  • Jerseyville, IL
  • Julie Billeter
  • Julie Graham
  • Kathy Fitzgerald
  • Keith Brinkmann
  • Knowledge Center
  • Lisa Bohnenstiehl
  • Locations
  • Mark Korte
  • Marketing Specialist
  • Michael D. Ulrich
  • Michael E. Fitzgerald
  • Michael T. Brokering
  • Non-Profit Organizations
  • Office Accounting Assistant
  • Our Team
  • Outsourced Accountant
  • Part-Time Bookkeeper
  • Payroll Assistant
  • Payroll Supervisor
  • Peer Review
  • Privacy Policy
  • Privately-Held Businesses
  • Professional Affiliations
  • Recruiting Events
  • Recruiting/Human Resources Coordinator
  • Resources
  • Robyn M. Klingler
  • Russell Gregson
  • Sarah Smith
  • Scheffel Boyle News
  • Scheffel Boyle Shares
  • Scott Weber
  • Seasonal Tax Preparer
  • Services
  • SIBA Webinar Presentation
  • Sneak Peek Survey
  • Spring Tax Internship Program 2026
  • STL Ag Club Webinar Prez
  • Summer Audit Internship Program
  • Summer Audit Internship Program 2026
  • Tax Planning & Preparation
  • Tax Talks Information
  • Tax Talks Presentation
  • Testimonials
  • Webinar Presentation May 14
  • Welcome Email
  • Year-End Tax Planning Seminars
  • Accountant – Carrollton
  • Administrative Assistant – Alton Office
  • Administrative Assistant – Belleville Office
  • Administrative Assistant – Columbia Office
  • Seasonal Administrative Assistants
  • Seasonal Data Input
  • Staff Accountant

Categories

  • Blog
  • Construction
  • Coronavirus Resource Center
  • Frontpage
  • Knowledge Center
  • Scheffel News
  • Uncategorized

Archive

  • August 2026
  • May 2026
  • November 2025
  • October 2025
  • July 2025
  • February 2024
  • July 2023
  • May 2023
  • February 2023
  • January 2023
  • November 2022
  • August 2022
  • July 2022
  • June 2022
  • March 2022
  • February 2022
  • January 2022
  • December 2021
  • June 2021
  • May 2021
  • April 2021
  • March 2021
  • February 2021
  • January 2021
  • December 2020
  • November 2020
  • October 2020
  • September 2020
  • August 2020
  • July 2020
  • June 2020
  • May 2020
  • April 2020
  • March 2020
  • February 2020
  • January 2020
  • December 2019
  • November 2019
  • October 2019
  • September 2019
  • August 2019
  • July 2019
  • June 2019
  • May 2019
  • April 2019
  • March 2019
  • February 2019
  • January 2019
  • December 2018
  • November 2018
  • October 2018
  • September 2018
  • August 2018
  • July 2018
  • June 2018
  • May 2018
  • April 2018
  • March 2018
  • February 2018
  • January 2018
  • December 2017
  • November 2017
  • October 2017
  • September 2017
  • August 2017
  • July 2017
  • June 2017
  • May 2017
  • April 2017
  • March 2017
  • February 2017
  • January 2017
  • December 2016
  • October 2016
  • September 2016
  • August 2016
  • July 2016
  • May 2016
  • April 2016
  • March 2016
  • February 2016
  • January 2016
  • December 2015
  • November 2015
  • August 2015
  • July 2015
  • June 2015
  • February 2015
  • January 2015
  • December 2014
  • November 2014
  • September 2014
  • August 2014
  • March 2014
  • February 2014
  • December 2013
  • November 2013
  • October 2013
  • August 2013
  • July 2013
  • June 2013
  • May 2013
  • February 2013
  • January 2013

About Us


Serving St. Louis, the Metro-East and Southwestern Illinois since 1924.

Knowledge Center

  • New Rules Could Increase Taxable Income for GamblersAugust 24, 2026 - 3:20 pm
  • IRS Notice CP53E and the Rise of Refund-Related ScamsMay 18, 2026 - 9:55 am
  • Potential Refund Deadline Extensions Under the Kwong CaseMay 7, 2026 - 11:40 am

Quick Links

  • Services
  • Clients & Industries
  • Our Team
  • Scheffel Boyle News
  • Careers

 Contact Us

Alton, IL: 618.465.4288
Edwardsville, IL: 618.656.1206
Belleville, IL: 618.277.8100
Highland, IL: 618.654.9895
Jerseyville, IL: 618.498.6841
Columbia, IL: 618.281.7605
Carrollton, IL: 217.942.3821

© Copyright 2021 Scheffel Boyle — All rights reserved
  • Site Map
  • Privacy Policy
Scroll to top Scroll to top Scroll to top