Loading
Scheffel Boyle
  • Home
  • About Us
    • Our Team
    • Our Values
    • Scheffel Boyle News
    • Professional Affiliations
    • Client Testimonials
    • Peer Review
    • Scheffel Boyle Shares
    • BDO Alliance USA
  • Services
    • Tax Planning & Preparation
    • Audit & Assurance
    • Accounting Services
    • Consulting Services
    • Financial Advisory
  • Clients & Industries
    • Construction
    • Financial Institutions
    • Agribusiness
    • Governmental Entities
    • Non-Profit Organizations
    • Privately-Held Businesses
    • Individual Clients
    • Employee Benefit Plans
  • Resources
    • Knowledge Center
    • Coronavirus Resource Center
    • Helpful Links
  • Careers
    • Benefits
    • Available Opportunities
    • College Students
  • Contact Us
    • Locations
      • Alton, IL
      • Belleville, IL
      • Carrollton, IL
      • Columbia, IL
      • Edwardsville, IL
      • Highland, IL
      • Jerseyville, IL
  • Click to open the search input field Click to open the search input field Search
  • Menu Menu
  • Link to Facebook
  • Link to LinkedIn

Tax Calendar

January 23, 2018

January 16 — Individual taxpayers’ final 2017 estimated tax payment is due.

January 31 — File 2017 Forms W-2 (“Wage and Tax Statement”) with the Social Security Administration and provide copies to your employees.

  • File 2017 Forms 1099-MISC (“Miscellaneous Income”) reporting nonemployee compensation payments in box 7 with the IRS and provide copies to recipients.
  • Most employers must file Form 941 (“Employer’s Quarterly Federal Tax Return”) to report Medicare, Social Security, and income taxes withheld in the fourth quarter of 2017. If your tax liability is less than $2,500, you can pay it in full with a timely filed return. If you deposited the tax for the quarter in full and on time, you have until February 12 to file the return. Employers who have an estimated annual employment tax liability of $1,000 or less may be eligible to file Form 944 (“Employer’s Annual Federal Tax Return”).
  • File Form 940 (“Employer’s Annual Federal Unemployment [FUTA] Tax Return”) for 2017. If your undeposited tax is $500 or less, you can either pay it with your return or deposit it. If it is more than $500, you must deposit it. However, if you deposited the tax for the year in full and on time, you have until February 12 to file the return.
  • File Form 943 (“Employer’s Annual Federal Tax Return for Agricultural Employees”) to report Social Security, Medicare, and withheld income taxes for 2017. If your tax liability is less than $2,500, you can pay it in full with a timely filed return. If you deposited the tax for the year in full and on time, you have until February 12 to file the return.
  • File Form 945 (“Annual Return of Withheld Federal Income Tax”) for 2017 to report income tax withheld on all nonpayroll items, including backup withholding and withholding on pensions, annuities, IRAs, etc. If your tax liability is less than $2,500, you can pay it in full with a timely filed return. If you deposited the tax for the year in full and on time, you have until February 12 to file the return.

February 28 — File 2017 Forms 1099-MISC with the IRS.

March 15 — 2017 tax returns must be filed or extended for calendar-year partnerships and S corporations. If the return is not extended, this is also the last day to make 2017 contributions to pension and profit-sharing plans.

© 2018

https://scheffelboyle.com/wp-content/uploads/2018/06/pexels-photo-1020323.jpeg 449 640 jordan@bonniburns.com https://scheffelboyle.com/wp-content/uploads/2022/06/Transparent-Logo-5.png jordan@bonniburns.com2018-01-23 18:25:202018-07-31 10:34:10Tax Calendar

Four Financial Planning Tips for Second Marriages

January 22, 2018

Every year, a substantial percentage of weddings aren’t first-time nuptials but second (or subsequent) marriages. Here are four tips to help such partners better manage the situation:

  1. Take inventory. Identify the assets and liabilities each person brings to the union. If one spouse has significant debt, how will the couple manage it? Or if one spouse holds significant savings or investments, both partners should decide whether ownership changes should occur.
  2. Complete any paperwork. For instance, if a former spouse remains listed as the beneficiary of a retirement account, he or she may ultimately receive the asset — even if the account owner intended it to go to a new spouse. (Note: In community property states, a former spouse may still be entitled to a portion of the account.) Therefore, beneficiary change documents may need to be executed.
  3. Consider executing new wills. This is particularly true if one spouse would like children from a previous marriage to receive, for example, a pre-existing business or personal property. If these wishes aren’t spelled out, the assets may not pass down as intended.
  4. Seek professional advice. Laws regarding divorce and remarriage vary by state. Consult an attorney and contact our firm to discuss tax and financial ramifications.

© 2018

https://scheffelboyle.com/wp-content/uploads/2018/06/pexels-photo.jpg 337 640 jordan@bonniburns.com https://scheffelboyle.com/wp-content/uploads/2022/06/Transparent-Logo-5.png jordan@bonniburns.com2018-01-22 18:23:462018-07-31 10:34:06Four Financial Planning Tips for Second Marriages

Still Important: The Tax Impact of Business Travel

January 21, 2018

With conference calls and Web meetings increasingly prevalent, business travel isn’t what it used to be. But if your company is still sending employees out on the road, it remains important to understand the tax ramifications.

Fringe benefits

Generally, for federal tax purposes, a company may deduct all ordinary and necessary expenses paid or incurred during the tax year in carrying on any trade or business. This includes travel expenses that aren’t deemed lavish or extravagant.

For employees, travel expenses are typically considered a “working condition fringe benefit” and, therefore, not included in gross income. Working condition fringe benefits are any property or service provided to an employee to the extent that, if he or she paid for the property or service, it would be tax-deductible.

Accountable plan

Under the Internal Revenue Code, an advance or reimbursement for travel expenses made to an employee under an “accountable plan” is deductible by the employer and not subject to FICA and income tax withholding. In general, an advance or reimbursement is treated as made under an accountable plan if an employee:

  • Receives the advance or reimbursement for a deductible business expense paid or incurred while performing services for his or her employer,
  • Accounts for the expense to his employer within a reasonable period of time and in an adequate manner, and
  • Returns any excess reimbursement or allowance within a reasonable period of time.

By contrast, an advance or reimbursement made under a “nonaccountable plan” isn’t considered a working condition fringe benefit — it’s treated as compensation. Thus, the amount is fully taxable to the employee, and subject to FICA and income tax withholding by the employer.

Travel status

Although business transportation — going from one place to another without an overnight stay — is deductible, attaining “business travel status” fully opens the door to substantial tax benefits. Under business travel status, the entire cost of lodging and incidental expenses, and 50% of meal expenses, is generally deductible by the employer that pays the bill. What’s more, those amounts don’t equate to any taxable income for employees who, as mentioned, are reimbursed under an accountable plan.

So how does a business trip qualify for business travel status? It must involve overnight travel; an employee traveling away from his or her tax home; and a temporary trip undertaken solely, or primarily, for ordinary and necessary business reasons.

Bear in mind that “overnight” travel doesn’t necessarily mean an employee must be away from dusk till dawn. Any trip that’s long enough to require sleep or rest to enable the taxpayer to continue working is considered “overnight.”

Furthermore, there’s an exception under which local, “nonlavish” lodging expenses incurred while not away from home overnight on business may be deductible if all facts and circumstances so indicate. One factor specified in the regs is whether the employee incurs the expense because of a bona fide employment condition or requirement.

Crucial details

Even if your company has pumped the brakes on business trips, knowing the tax rules can save you valuable dollars on those “must go” travel engagements. We can help you with the crucial details — and particularly in setting up an accountable plan if you don’t already have one.

© 2018

https://scheffelboyle.com/wp-content/uploads/2018/01/pexels-photo-297755.jpeg 417 640 jordan@bonniburns.com https://scheffelboyle.com/wp-content/uploads/2022/06/Transparent-Logo-5.png jordan@bonniburns.com2018-01-21 18:19:392018-07-31 10:34:03Still Important: The Tax Impact of Business Travel

Owner-Employees Need to Stay Up to Speed on Employment Taxes

January 20, 2018

Keeping up with the complexity of the Internal Revenue Code is challenging for an individual and even more so for a business owner. But, if you’re someone who handles both roles — an owner-employee — the difficulty level is particularly high. Nonetheless, it’s important to stay up to speed on your specific obligations. As you’re no doubt aware, much depends on the structure of your company.

Partnerships and LLCs

Generally, all trade or business income that flows through to you for income tax purposes is subject to self-employment taxes — even if the income isn’t actually distributed to you. But such income may not be subject to self-employment taxes if you’re a limited partner or member of a limited liability company whose ownership is equivalent to a limited partnership interest. Whether the additional 0.9% Medicare tax on earned income or the 3.8% net investment income tax (NIIT) applies also is complex to determine.

S corporations

Under an S corporation, only income you receive as salary is subject to employment taxes and, if applicable, the 0.9% Medicare tax. To reduce these taxes, you may want to keep your salary relatively — but not unreasonably — low and increase your distributions of company income (which generally isn’t taxed at the corporate level or subject to the 0.9% Medicare tax or 3.8% NIIT).

C corporations

For C corporations, only income you receive as salary is subject to employment taxes. If applicable, the 0.9% Medicare tax may be due as well. Nevertheless, you may prefer to take more income as salary (which is deductible at the corporate level) as opposed to dividends (which aren’t deductible at the corporate level, are taxed at the shareholder level and could be subject to the 3.8% NIIT) if the overall tax paid by both the corporation and you would be less. Warning: The IRS is cracking down on misclassification of corporate payments to shareholder-employees, so tread carefully.

Latest info

As this article went to press, tax law reform efforts were underway that may affect some of this article’s content. Please contact our firm for the latest information.

© 2018

https://scheffelboyle.com/wp-content/uploads/2018/01/IRS.jpg 166 250 jordan@bonniburns.com https://scheffelboyle.com/wp-content/uploads/2022/06/Transparent-Logo-5.png jordan@bonniburns.com2018-01-20 13:05:432019-09-20 08:13:17Owner-Employees Need to Stay Up to Speed on Employment Taxes

Tax News December 2017

December 1, 2017

EDUCATE EMPLOYEES ON REQUIRED MINIMUM DISTRIBUTION RULES

The deadline for taking 2017 required minimum distributions (RMDs) is rapidly approaching: December 31, 2017. If you own a business and offer a 401(k) plan, it’s a good time to think about how you can make sure your older employees are aware of the RMD obligations, including how the rules differ for IRAs vs. 401(k) plans.

IRAs vs. 401(k)s

To avoid a huge penalty, individuals must take RMDs from their IRAs (other than Roth IRAs) on reaching age 70½. However, the first payment can be delayed until April 1 of the year following the year in which the individual turns 70½. (Beware: Different RMD rules apply to inherited IRAs.)

Distributions from 401(k)s are different; current employees don’t have to take 401(k) RMDs. Although the regulations don’t state how many hours employees need to work to postpone 401(k) RMDs, they must be doing legitimate work and receiving W-2 wages.

There’s an important exception, however: Owner-employees (if they own at least 5% of the company) must begin taking RMDs from the 401(k) beginning at 70½, regardless of work status.

If someone has multiple IRAs, it doesn’t matter which one he or she takes RMDs from so long as the total amount reflects their aggregate IRA assets. In contrast, RMDs based on 401(k) plan assets must be taken specifically from the 401(k) plan account.

Calculating RMDs

RMD amounts change each year as the retiree ages, based on the applicable IRS life expectancy table.

For example, at age 72, the “distribution period” is 25.6, meaning that the IRS life expectancy table assumes that the account holder will live about another 25½ years. Thus, someone age 72 must withdraw 1/25.6 of his or her IRA or 401(k) account. Percentage-wise, that is 3.91%.

If someone lives to age 90, the distribution period would be 11.4, resulting in an 8.77% RMD. Although the percentage amount increases over time, the IRS rules don’t force retirees to zero out their accounts. Still, if an account holder lives long enough, he or she isn’t likely to have a lot of funds remaining in the account at death.

Informed and happy

Remember, informed employees are happy employees — which can lead to more engaged, productive employees. We’d be happy to assist you in providing the most current, accurate information.

Sidebar: Other facts about RMDs

Here are some additional facts about required minimum distributions (RMDs) that you can share with employees:

Beneficiary spouses. Account holders who have a beneficiary spouse at least 10 years younger are subject to a different RMD life expectancy table that allows them to take out smaller amounts to preserve retirement assets for the younger spouse.

Tax penalty. The tax penalty for withdrawing less than the RMD amount is 50% of the portion that should have been withdrawn but wasn’t.

Form of distribution. RMDs can be taken in cash or in stock shares whose value is the same as the RMD amount. Although taking stock shares can be administratively burdensome, doing so can allow account holders to defer incurring brokerage commissions on securities they don’t want to sell. Their tax basis in the stock (for future capital gains liability calculation purposes) will reset to the value of the securities when they’re distributed.

DAPTS OFFER A HOMEGROWN APPROACH TO ASSET PROTECTION

Your assets face many potential threats to their value, such as market volatility and inflation. Another threat, especially if you’re at high risk for lawsuits, is creditors. The most effective way to protect assets from such a threat may be to transfer them to children or other family members, either outright or in trust, with no strings attached. So long as the transfer isn’t fraudulent — that is, intended to delay or defraud knowncreditors — creditors won’t be able to touch the assets.

If you wish to retain some control over your wealth, however, consider an asset protection trust. For affluent families with significant liability concerns, foreign asset protection trusts probably offer the greatest protection. But if you prefer to avoid the complexity and expense of these arrangements, look into a domestic asset protection trust (DAPT).

How does it work?

A DAPT is an irrevocable, spendthrift trust established in one of the 16 states that currently authorize this trust type (Alaska, Colorado, Delaware, Hawaii, Mississippi, Missouri, Nevada, New Hampshire, Ohio, Oklahoma, Rhode Island, South Dakota, Tennessee, Utah, Virginia and Wyoming). Unlike trusts in other jurisdictions, a DAPT offers creditor protection even if you’re a discretionary beneficiary of the trust.

You don’t necessarily have to live in one of the previously listed states. But, to set up a trust in a state where you don’t reside, you’ll typically need to move some or all of the trust assets there and engage a bank or trust company in the state to administer the trust.

DAPT protection varies from state to state, so it’s important to shop around. For example, different jurisdictions have different statute of limitations periods, which determine how long you’ll have to wait until full asset protection kicks in. (During the limitations period, creditors can challenge transfers to the trust.) Also, most of the DAPT laws contain exceptions for certain types of creditors, such as divorcing spouses, child support creditors and pre-existing tort creditors.

Usually, DAPTs are incomplete gift trusts, which give you some flexibility to change beneficiaries or otherwise control asset disposition. But it’s also possible to structure a DAPT as a completed gift trust, thereby removing the assets (and any future appreciation of those assets) from your taxable estate.

What’s the primary risk?

A DAPT’s main disadvantage is the uncertainty over whether it will withstand a court challenge. Although they’ve been around since 1997, DAPTs haven’t been widely tested in court.

Most experts agree that, if you live in one of the states with a DAPT statute, a properly designed and funded DAPT will likely be effective. But some uncertainty surrounds trusts established by nonresidents.

Is it the right move?

There are other ways to protect your assets from creditors, such as through insurance or use of various business entity structures. We can help you decide whether a DAPT is the right move.


5 COMMON MISTAKES WHEN APPLYING FOR FINANCIAL AID

Given the astronomical cost of college, even well-off parents should consider applying for financial aid. A single misstep, however, can harm your child’s eligibility. Here are five common mistakes to avoid:

  1. Presuming you don’t qualify.It’s difficult to predict whether you’ll qualify for aid, so apply even if you think your net worth is too high. Keep in mind that, generally, the value of your principal residence or any qualified retirement assets isn’t included in your net worth for financial aid purposes.
  2. Filing the wrong forms.Most colleges and universities, and many states, require you to submit the Free Application for Federal Student Aid (FAFSA) for need-based aid. Some schools also require it for merit-based aid. In addition, a number of institutions require the CSS/Financial Aid PROFILE®, and specific types of aid may have their own paperwork requirements.
  3. Missing deadlines.Filing deadlines vary by state and institution, so note the requirements for each school to which your child applies. Some schools provide financial aid to eligible students on a first-come, first-served basis until funding runs out, so the earlier you apply, the better. This may require you to complete your income tax return early.
  4. Picking favorites. The FAFSA allows you to designate up to 10 schools with which your application will be shared. Some families list these schools in order of preference, but there’s a risk that schools may use this information against you. Schools at the top of the list may conclude that they can offer less aid because your child is eager to attend. To avoid this result, consider listing schools in alphabetical order.
  5. Mistaking who’s responsible. If you’re divorced or separated, the FAFSA should be completed by the parent with whom your child lived for the majority of the 12-month period ending on the date the application is filed. This is true regardless of which parent claims the child as a dependent on his or her tax return.

The rule provides a significant planning opportunity if one spouse is substantially wealthier than the other. For example, if the child lives with the less affluent spouse for 183 days and with the other spouse for 182 days, the less affluent spouse would file the FAFSA, improving eligibility for financial aid.

These are just a few examples of financial aid pitfalls. Let us help you navigate the process and explore other ways to finance college.


ENSURING YOUR YEAR-END DONATIONS ARE TAX DEDUCTIBLE

Many people make donations at the end of the year. To be deductible on your 2017 return, a charitable donation must be made by December 31, 2017. According to the IRS, a donation generally is “made” at the time of its “unconditional delivery.” But what does this mean?

Is it the date you write a check or charge an online gift to your credit card? Or is it the date the charity actually receives the funds? In practice, the delivery date depends in part on what you donate and how you donate it. Here are a few common examples:

Checks. The date you mail it.

Credit cards. The date you make the charge.

Pay-by-phone accounts. The date the financial institution pays the amount.

Stock certificates. The date you mail the properly endorsed stock certificate to the charity.

To be deductible, a donation must be made to a “qualified charity” — one that’s eligible to receive tax-deductible contributions. The IRS’s online search tool, “Exempt Organizations (EO) Select Check,” can help you more easily find out whether an organization is eligible to receive tax-deductible charitable contributions. You can access it at https://www.irs.gov/charities-non-profits/exempt-organizations-select-check. Information about organizations eligible to receive deductible contributions is updated monthly.

Many additional rules apply to the charitable donation deduction, so please contact us if you have questions about the deductibility of a gift you’ve made or are considering making. But act soon — you don’t have much time left to make donations that will reduce your 2017 tax bill.


Important Information: The information contained in this newsletter was not intended or written to be used and cannot be used for the purpose of (1) avoiding tax-related penalties prescribed by the Internal Revenue Code or (2) promoting or marketing any tax-related matter addressed herein.

The Tax and Business Alert is designed to provide accurate information regarding the subject matter covered. However, before completing any significant transactions based on the information contained herein, please contact us for advice on how the information applies in your specific situation. Tax and Business Alert is a trademark used herein under license. © Copyright 2017.
https://scheffelboyle.com/wp-content/uploads/2017/12/business-money-pink-coins.jpg 418 640 jordan@bonniburns.com https://scheffelboyle.com/wp-content/uploads/2022/06/Transparent-Logo-5.png jordan@bonniburns.com2017-12-01 18:33:352018-07-31 10:34:47Tax News December 2017

Tax News – November 2017

November 6, 2017

HANDLE WITH CARE: MUTUAL FUNDS AND TAXES

Many people overlook taxes when planning their mutual fund investments. But you’ve got to handle these valuable assets with care. Here are some tips to consider.

Avoid year-end investments

Typically, mutual funds distribute accumulated dividends and capital gains toward the end of the year. But don’t fall for the common misconception that investing in a fund just before a distribution date is like getting “free money.”

True, you’ll receive a year’s worth of income right after you invest. But the value of your shares will immediately drop by the same amount, so you won’t be any better off. Plus, you’ll be liable for taxes on the distribution as if you had owned your shares all year.

You can get a general idea of when a particular fund anticipates making a distribution by checking its website periodically. Also make a note of the “record date” — investors who own fund shares on that date will participate in the distribution.

Invest in tax-efficient funds

Actively managed funds tend to be less tax efficient. They buy and sell securities more frequently, generating a greater amount of capital gain, much of it short-term gain taxable at ordinary income rates rather than the lower, long-term capital gains rates.

Consider investing in tax-efficient funds instead. For example, index funds generally have lower turnover rates. And “passively managed” funds (sometimes described as “tax managed” funds) are designed to minimize taxable distributions.

Another option is exchange-traded funds (ETFs). Unlike mutual funds, which generally redeem shares by selling securities, ETFs are often able to redeem securities “in kind” — that is, to swap them for other securities. This limits an ETF’s recognition of capital gains, making it more tax efficient.

This isn’t to say that tax-inefficient funds don’t have a place in your portfolio. In some cases, actively managed funds may offer benefits, such as above-market returns, that outweigh their tax costs.

Watch out for reinvested distributions

Many investors elect to have their distributions automatically reinvested in their funds. Be aware that those distributions are taxable regardless of whether they’re reinvested or paid out in cash.

Reinvested distributions increase your tax basis in a fund, so track your basis carefully. If you fail to account for these distributions, you’ll end up paying tax on them twice — once when they’re paid and again when you sell your shares in the fund.

Fortunately, under current rules, mutual fund companies are required to track your basis for you. But you still may need to track your basis in funds you owned before 2012 when this requirement took effect, or if you purchased units in the fund outside of the current broker holding your units.

Do your due

Tax considerations should never be the primary driver of your investment decisions. Yet it’s important to do your due diligence on the potential tax consequences of funds you’re considering — particularly for your taxable accounts.

Sidebar: Directing tax-inefficient funds into nontaxable accounts

If you invest in actively managed or other tax-inefficient funds, ideally you should put these holdings in nontaxable accounts, such as a traditional IRA or 401(k). Because earnings in these accounts are tax-deferred, distributions from funds they hold won’t have any tax consequences until you withdraw them. And if the funds are held in a Roth account, those distributions will escape taxation altogether.


BAD DEBTS AREN’T ALWAYS BAD NEWS

The IRS defines a business bad debt as “a loss from the worthlessness of a debt that was either created or acquired in a trade or business or closely related to your trade or business when it became partly to totally worthless.” Although no business owner goes out of his or her way to acquire a bad debt, they’re not always bad news.

The silver lining

Indeed, there’s a potential silver lining to bad debts. In certain situations, you can deduct uncollected debts from your business income, which may reduce your tax liability.

One requirement for a deduction generally is that the amount of the bad debt was previously included in your income. This effectively means that only businesses that use accrual-basis accounting can deduct bad debts.

Cash-basis businesses generally can’t deduct bad debts because they haven’t previously reported the debt as income. So they can’t claim a bad debt deduction simply because someone failed to pay a bill. But they may be able to claim a bad debt deduction if they’ve made a business-related loan that became uncollectible.

What may be deductible

The IRS lists the following examples of potentially deductible bad debts:

  • Credit sales to customers,
  • Loans to clients and suppliers, and
  • Business loan guarantees.

Bankruptcy is a common reason a business might determine that a debt is uncollectible and should be written off. For example, suppose a customer files for bankruptcy and states that the liquidation value of its assets is less than the amount owed to its primary lien holder. Once this customer informs you that your receivable won’t be paid, you can generally write off the amount as a bad debt.

There’s no standard test or formula for determining whether a debt is a bad debt; it depends on the specific facts and circumstances. To qualify for the deduction, you simply must show that you’ve taken reasonable steps to collect the debt and there’s little likelihood it will be paid. If you have outstanding debts that you don’t think will be paid and could be deductible on your 2017 tax return, be sure, if you haven’t already, to take steps to try to collect the debt.

Wholly vs. partially worthless debt

The IRC doesn’t define “worthlessness.” Courts, however, have defined wholly worthless debts as those lacking both current and potential value. The U.S. Tax Court says that partial worthlessness is evidenced by “some event or some change in the financial condition of the debtor . . . which adversely affects the debtor’s ability to make repayment.”

In general, you may recover a portion of a partially worthless debt in the future. You never recover any part of a wholly worthless debt.

Important topic

The right tax strategy for your company’s bad debts is an important topic to consider every year end. Our firm can help you ensure you’re taking all the bad debt deductions you’re entitled to.


PONDERING THE PURCHASE OF A LIFE INSURANCE POLICY

What, if any, role life insurance should play in your financial plan depends on a variety of factors. These include whether you’re single or married, if you have minor children or other dependents, and your net worth and estate planning goals. There’s also the tax impact to consider. Let’s look a little more closely at some of the issues behind whether you should buy a policy.

Looking at your situation

Life insurance is appealing because relatively small payments now can produce a proportionately much larger payout at death. But the fact that the return on the investment generally isn’t realized until death can also be a downside, depending on your financial situation and goals.

If you have others depending on you financially, your No. 1 priority is likely ensuring that they will continue to be provided for after you’re gone. Life insurance can be a useful tool for achieving this goal.

If you’re single and have no dependents, life insurance may be less important or even unnecessary. Perhaps you’ll want just enough coverage so that your mortgage can be paid off and your home can pass unencumbered to the designated heir(s) — or just enough to pay your funeral expenses.

Assessing your finances

Some people of high net worth may not need life insurance for any of the aforementioned purposes. Nonetheless, it might serve other purposes in their estate plans. For example, a policy can provide liquidity to pay estate taxes without having to sell assets that you want to keep in the family. Or it can be used to equalize inheritances for children who aren’t involved in a family business so that family business interests can go only to those active in the business.

While proceeds are generally income-tax-free to the beneficiary, they’ll be included in your taxable estate as long as you’re the owner. If your estate might exceed your estate tax applicable exemption amount ($5.49 million for 2017), some or all of the life insurance proceeds could be subject to estate taxes. To avoid this result, consider having someone else own the policy. This can create other tax complications, however, so it’s important to consult your tax advisor.

Figuring out your needs

For many people, life insurance is critical to creating financial security for their family or achieving other financial goals. Please contact our firm for specific insight into this important matter.

ARE FREQUENT FLYER MILES EVER TAXABLE?

If you recently redeemed frequent flyer miles to treat the family to a fun summer vacation or to take your spouse on a romantic getaway, you might assume that there are no tax implications involved. And you’re probably right — but there is a chance your miles could be taxable.

Generally, miles awarded by airlines for flying with them are considered nontaxable rebates, as are miles awarded for using a credit or debit card. The IRS even addressed the issue in Announcement 2002-18, where it said:

Consistent with prior practice, the IRS will not assert that any taxpayer has understated his federal tax liability by reason of the receipt or personal use of frequent flyer miles or other in-kind promotional benefits attributable to the taxpayer’s business or official travel.

There are, however, some types of miles awards the IRS might view as taxable. Examples include miles awarded as a prize in a sweepstakes and miles awarded as a promotion.

For instance, in the 2014 case of Shankar v. Commissioner, the U.S. Tax Court sided with the IRS in finding that airline miles awarded in conjunction with opening a bank account were indeed taxable. Part of the evidence of taxability was the fact that the bank had issued Forms 1099 MISC to customers who’d redeemed rewards points to buy airline tickets.

The value of the miles for tax purposes generally is their estimated retail value. If you’re concerned you’ve received miles awards that could be taxable, please contact us.


Important Information: The information contained in this newsletter was not intended or written to be used and cannot be used for the purpose of (1) avoiding tax-related penalties prescribed by the Internal Revenue Code or (2) promoting or marketing any tax-related matter addressed herein.

The Tax and Business Alert is designed to provide accurate information regarding the subject matter covered. However, before completing any significant transactions based on the information contained herein, please contact us for advice on how the information applies in your specific situation. Tax and Business Alert is a trademark used herein under license. © Copyright 2017.
https://scheffelboyle.com/wp-content/uploads/2018/06/pexels-photo-938958.jpeg 959 640 jordan@bonniburns.com https://scheffelboyle.com/wp-content/uploads/2022/06/Transparent-Logo-5.png jordan@bonniburns.com2017-11-06 18:37:542018-07-31 10:34:52Tax News – November 2017

House Tax Bill Released

November 1, 2017

HOUSE TAX BILL RELEASED

On November 2, 2017, the House of Representatives released a draft tax reform bill titled the “Tax Cuts and Jobs Act.”  The bill would reduce individual and business tax rates, would modify or eliminate a variety of itemized deductions as well as repeal the estate and alternative minimum taxes, and would change the taxation of foreign income.  The Ways & Means Committee intends to formally markup the bill the week of November 6 with full House floor consideration planned before Thanksgiving.  Most of the provisions would be effective starting in 2018.
Details

Under the House bill, individuals would be subject to four tax brackets at 12, 25, 35, and 39.6 percent.  The 39.6 rate would apply at $1 million for married taxpayers filing jointly and $500,000 for other filers.  The standard deduction would be increased, from $6,350 to $12,200 for single filers and from $12,700 to $24,400 for married taxpayers filing jointly.  Personal exemptions would be repealed; however, the child tax credit would be expanded.

Itemized deductions would be changed significantly by the bill.  Deductions for state and local income and sales taxes would be eliminated for individuals, and the deduction for local property taxes paid would be capped at $10,000.  Mortgage interest expense deductions would be limited to acquisition indebtedness on the taxpayer’s principal residence of up to $500,000 for new mortgage indebtedness, reduced from the current limit of $1 million (existing mortgages would be grandfathered).  Home equity indebtedness would no longer be deductible. Cash contributions to public charities would be limited to 60 percent of the donor’s adjusted gross income, an increase from 50 percent adjusted gross income limitation under current law.  Deductions for tax preparation fees, medical expenses, moving expenses, and personal casualty losses would be repealed, but the deduction for personal casualty losses would remain for relief provided under special disaster relief legislation. The overall limitation on itemized deductions would also be removed.  The individual alternative minimum tax (AMT) would be repealed. Transition provisions would ensure taxpayers with AMT carryforwards would be able to use the remaining credits between 2018 and 2022.

Notably, most of the reform provisions are effective beginning after 2017; however, the changes to the mortgage interest expense deduction are effective for debt incurred on or after November 2, 2017.

The exclusion of gain from the sale of a principal residence would be phased out for married taxpayers with an adjusted gross income in excess of $500,000 ($250,000 for single filers) but the act changes the use requirements and calls for taxpayers to live in the residence for five of the previous eight years to qualify, up from the current requirement to use the residence for two of the previous five years. The bill further repeals the deduction for alimony payments effective for any divorce decree or separation agreement executed after 2017.

Estate, gift, and generation-skipping transfer (GST) tax exclusions for individuals would be increased to $10 million (as of 2011) and then adjusted for inflation, and the estate and GST taxes would then be repealed after 2023 but would maintain the step-up in basis provisions. Beginning in 2024, the top gift tax rate would be lowered to 35 percent with a lifetime exemption of $10 million and an annual exclusion of $14,000 (as of 2017) indexed for inflation.

Impacting businesses, the corporate tax rate would be reduced from 35 percent to 20 percent, and certain “business income” from pass-through entities would be taxed at 25 percent instead of an owner’s individual rate.  Bonus depreciation of 100 percent would be available for qualifying property placed in service before January 1, 2023, new property types would qualify for bonus depreciation and expense amounts would be expanded.  The bill proposes to eliminate the Domestic Production Activities Deduction and change other aspects of entertainment expenses, net operating losses, like-kind exchanges, business credits, and small-business accounting methods, among other provisions.  The bill would also repeal the corporate alternative minimum tax (AMT) and make existing AMT credit carryforwards refundable over a period of five years.

Taxation of a corporation’s foreign income would change from a worldwide system to an exemption system, with a 100-percent exemption from U.S. tax for the foreign source portion of dividends paid by a foreign subsidiary to U.S. corporate shareholders that own 10 percent or more of the foreign subsidiary.  To transition to the exemption system, the bill also includes a transition tax for untaxed foreign earnings accumulated under the current worldwide taxing system. The House bill also includes provisions to prevent base erosion. A separate tax alert discussing in more detail the House bill’s proposals relating to the taxation of foreign income and foreign persons is forthcoming.

The bill would impact tax-exempt entities as well through the expanded application of unrelated business income tax (UBIT) rules and a flat 1.4 percent tax of the net investment income of entities including private foundations.
Insights

The release of the House bill represents the first significant and detailed legislative step toward tax reform under the Trump Administration.  As drafted, most of the provisions would be effective for the 2018 tax year.  The House Ways & Means Committee is expected to formally markup the legislation the week of November 6, with full House consideration planned before Thanksgiving.

There are additional provisions in the proposed legislation effecting education credits, retirement accounts, deferred compensation, and private foundations, among others.

https://scheffelboyle.com/wp-content/uploads/2018/06/pexels-photo-921783.jpeg 571 640 jordan@bonniburns.com https://scheffelboyle.com/wp-content/uploads/2022/06/Transparent-Logo-5.png jordan@bonniburns.com2017-11-01 18:35:472018-07-31 10:34:59House Tax Bill Released

Write-Off Hunger Raises Thousands

October 4, 2017

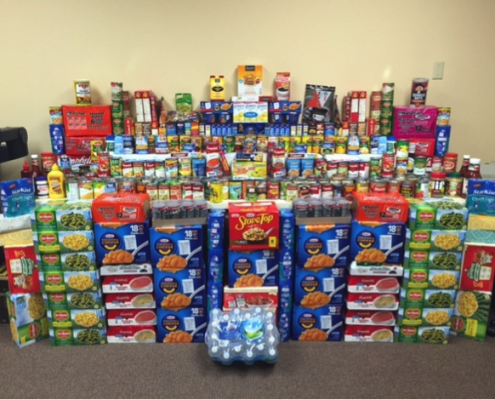
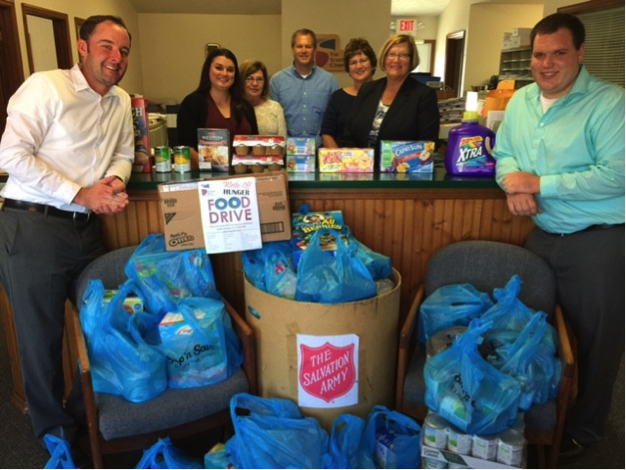
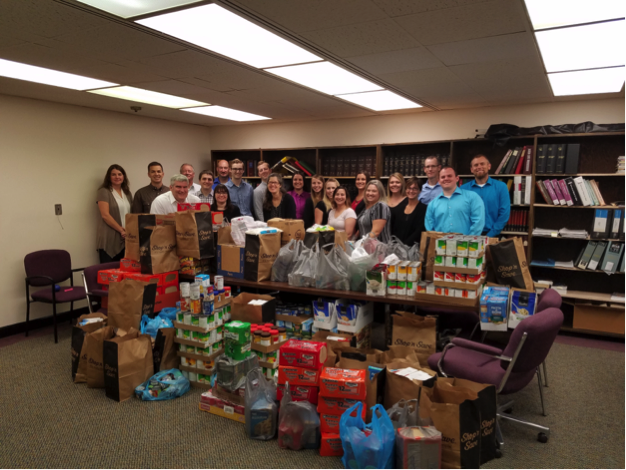
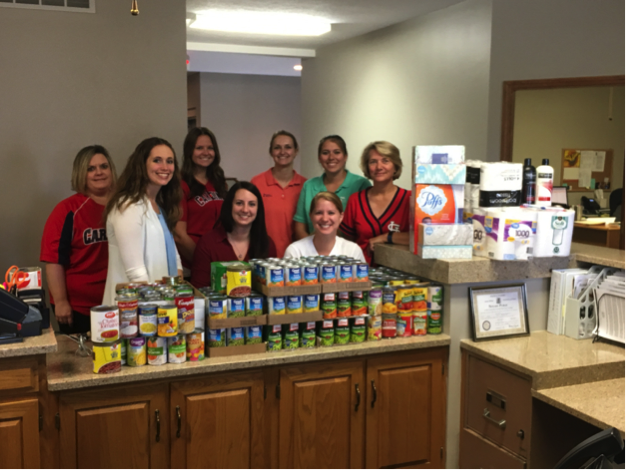
We recently teamed together for our annual Scheffel Boyle Shares project. Each year, we plan philanthropic activities throughout our offices to give back to our local communities. This year, our employees organized the “Write-Off Hunger” food drive which culminated in the collection of more than 5,500 food items to be donated to local food pantries!

Each of our offices strategized and found creative ways to raise the most donations possible. One office organized a “Cars for Cans” car wash in their parking lot where the fee for a wash was $5 or 5 items of non-perishable food items. Another took to social media to raise funds and “coupon shopped” to get the most out of their donated dollars. Each office exercised their entrepreneurial spirit to find innovative ways of collecting donations for the drive. We are so proud of all they accomplished!

Firm leadership also organized two “Cardinals for Cans” days, where employees could wear their St. Louis Cardinal gear for a fee of $5 or 5 cans. In addition, we also hosted a “Dress for Success” day where if an employee were to forego their normal casual Friday and dress for success instead, the firm would give $5 in their name toward their office’s donation fund.

While it was a firm-wide project, each office will donate what they raised to their own local community food bank. Some organizations who will receive donations from Write-Off Hunger include the Salvation Army Food Pantry of Jerseyville, the Glen-Ed Food Pantry, the Crisis Food Center, the Carrollton Food Pantry, Community Care Center, the Highland Area Christian Service Ministry, and the Community Hope Center, among others.


https://scheffelboyle.com/wp-content/uploads/2018/06/pic2.png 470 626 jordan@bonniburns.com https://scheffelboyle.com/wp-content/uploads/2022/06/Transparent-Logo-5.png jordan@bonniburns.com2017-10-04 18:40:122018-07-31 10:35:29Write-Off Hunger Raises Thousands

Tax News October 2017

October 3, 2017

HOW TO STEER CLEAR OF TAX ISSUES RELATED TO SHAREHOLDER LOANS

Owners occasionally need to borrow funds from their businesses. If your business is structured as a corporation and it has extra cash on hand, a shareholder loan can be a convenient and low-cost option — but it’s important to treat the transaction as a bona fide loan. If you don’t, the IRS may claim you received a taxable dividend or compensation payment rather than a loan.

Taking a closer look

A corporation can make de minimis loans of $10,000 or less to shareholders without paying interest. But, if all of the loans from the corporation to a shareholder add up to more than $10,000, the advances may be subject to a complicated set of below-market interest rules unless you charge what the IRS considers an “adequate” rate of interest. Each month the IRS publishes its applicable federal rates (AFRs), which vary depending on the term of the loan.

Right now, although interest rates are starting to rise, they’re still near historic lows, making it a good time to borrow money. For example, in July 2017, the adjusted AFR for short-term loans (of not more than three years) was only 1.22% (up from 0.71% in July 2016). The rate was 1.89% (up from 1.43% in July 2016) for midterm loans (with terms ranging from more than three years to not more than nine years).

The AFRs are typically below what a bank would charge. As long as the corporation charged interest at the AFR (or higher), the loan would be exempt from the complicated below-market interest rules the IRS imposes.

The interest rate for a demand loan — which is payable whenever the corporation wants to collect it — isn’t fixed when the loan is set up. Instead it varies depending on market conditions. So, calculating the correct AFR for a demand loan is more complicated than it is for a term loan. In general, it’s easier to administer a shareholder loan with a prescribed term than a demand note.

Staying under market

If a corporation lends money to a shareholder at an interest rate that’s below the AFR, the IRS requires it to impute interest using the below-market interest rules. These calculations can be complicated. The amount of incremental imputed interest (beyond what the corporation already charges the shareholder) depends on when the loan was set up and whether it’s a demand or term loan. There are also tax consequences for this imputed interest to both the corporation and the shareholder.

Additionally, the IRS may argue that the loan should be reclassified as either a dividend or additional compensation. The corporation may deduct the latter, but it will also be subject to payroll taxes. Both dividends and additional compensation would be taxable income to the shareholder personally, however.

Making it bona fide

When deciding whether payments made to shareholders qualify as bona fide loans, the IRS considers a variety of factors. It assesses the size of the loan, as well as the corporation’s history of earnings, dividend payments and loan repayments. It also looks at the shareholder’s ability to repay the loan and power to make corporate decisions.

In addition, the IRS will factor in whether you’ve executed a formal, written note that specifies repayment terms — including the interest rate, maturity date and collateral.

Getting started

Under the right circumstances, a shareholder loan could be a smart tax planning move to make this year. Contact our firm to help you set up and monitor your shareholder loans to ensure compliance with the IRS rules.


WILLS AND LIVING TRUSTS: ESTATE PLANNING IMPERATIVES

Well-crafted, up-to-date estate planning documents are an imperative for everyone. They also can help ease the burdens on your family during a difficult time. Two important examples: wills and living trusts.

The will

A will is a legal document that arranges for the distribution of your property after you die and allows you to designate a guardian for minor children or other dependents. It should name the executor or personal representative who’ll be responsible for overseeing your estate as it goes through probate. (Probate is the court-supervised process of paying any debts and taxes and distributing your property after you die.) To be valid, a will must meet the legal requirements in your state.

If you die without a will (that is, “intestate”), the state will appoint an administrator to determine how to distribute your property based on state law. The administrator also will decide who will assume guardianship of any minor children or other dependents. Bottom line? Your assets may be distributed — and your dependents provided for — in ways that differ from what you would have wanted.

The living trust

Because probate can be time-consuming, expensive and public, you may prefer to avoid it. A living trust can help. It’s a legal entity to which you, as the grantor, transfer title to your property. During your life, you can act as the trustee, maintaining control over the property in the trust. On your death, the person (such as a family member or advisor) or institution (such as a bank or trust company) you’ve named as the successor trustee distributes the trust assets to the beneficiaries you’ve named.

Assets held in a living trust avoid probate — with very limited exceptions. Another benefit is that the successor trustee can take over management of the trust assets should you become incapacitated.

Having a living trust doesn’t eliminate the need for a will. For example, you can’t name a guardian for minor children or other dependents in a trust. However, a “pour over” will can direct that assets you own outside the living trust be transferred to it on your death.

Other documents

There are other documents that can complement a will and living trust. A “letter of instruction,” for example, provides information that your family will need after your death. In it, you can express your desires for the memorial service, as well as the contact information for your employer, accountant and any other important advisors. (Note: It’s not a legal document.)

Also consider powers of attorney. A durable power of attorney for property allows you to appoint someone to act on your behalf on financial matters should you become incapacitated. A power of attorney for health care covers medical decisions and also takes effect if you become incapacitated. The person to whom you’ve transferred this power — your health care agent — can make medical decisions on your behalf.

Foundational elements

These are just a few of the foundational elements of a strong estate plan. We can work with you and your attorney to address the tax issues involved.

SHOULD YOU CHANGE YOUR BUSINESS – OR TRANSFORM IT?

As its market and technological needs evolve, every company needs to change. There’s even a formal term for the undertaking: “change management.” From an operational standpoint, change involves opening up the hood and switching out old engine parts for new ones. Even if it affects the business as a whole, change means focusing on specific areas and making alterations over relatively short periods.

At some point in the existence of many companies, the organization needs to go beyond change to transformation. This is much different. Business transformations aren’t so much about switching out parts as overhauling the entire engine, possibly modifying the frame and even applying a new coat of paint. Let’s look a little more closely at the distinction.

Reinvent yourself

Say a large commercial construction company was having trouble meeting its sales goals because of environmental regulations. So, it decided to augment its sales teams with environmental engineers who could better assess the compliance impact. The company applied change management principles — such as building a case for the idea and adjusting its business culture — and was successful. This was no doubt an important change, but the business itself wasn’t transformed.

The objective of a true transformation is to essentially reinvent the company and implement a new business model. And that model needs to be a carefully, formally devised chain of interlocking strategic initiatives that apply to the entire organization.

Perhaps the most obvious and universal example of a business transformation is Apple. The technology giant, once a head-to-head competitor with IBM on the personal computer market, found itself struggling in the 1990s. So, under the tutelage of the late Steve Jobs, it transformed itself into a mobile technology company. It still makes computers, of course, but the company’s transformative success can really be attributed to its mobile devices and operating systems.

Think and act wisely

Every business transformation differs based on the history, nature and size of the company in question. But there are best practices to keep in mind. For example, start with your customers, visualizing what they need (even if they don’t know it yet). Also, build a chain of initiatives, so you’re not trying to do everything all at once. And use metrics, so you can track specific dollar amounts and productivity goals throughout the transformation.

Above all, be ready for anything. Even the best-planned transformations can produce unpredictable results. So keep expectations in line and take a measured, patient approach to every initiative involved.

Bring along help

Successful business transformations can be spectacular and profitable. But, make no mistake, the risk level is high. So if you decide to embark on this journey, bring along your trusted financial, legal and strategic advisors.

3 STRATEGIES FOR HANDLING ESTIMATED TAX PAYMENTS

In today’s economy, many individuals are self-employed. Others generate income from interest, rent or dividends. If these circumstances sound familiar, you might be at risk of penalties if you don’t pay enough tax during the year through estimated tax payments and withholding. Here are three strategies to help avoid underpayment penalties:

  1. Know the minimum payment rules.For you to avoid penalties, your estimated payments and withholding must equal at least:
  • 90% of your tax liability for the year,
  • 110% of your tax for the previous year, or
  • 100% of your tax for the previous year if your adjusted gross income for the previous year was $150,000 or less ($75,000 or less if married filing separately).
  1. Use the annualized income installment method.This method often benefits taxpayers who have large variability in income by month due to bonuses, investment gains and losses, or seasonal income — especially if it’s skewed toward year end. Annualizing calculates the tax due based on income, gains, losses and deductions through each “quarterly” estimated tax period.
  2. Estimate your tax liability and increase withholding.If, as year end approaches, you determine you’ve underpaid, consider having the tax shortfall withheld from your salary or year-end bonus by December 31. Because withholding is considered to have been paid ratably throughout the year, this is often a better strategy than making up the difference with an increased quarterly tax payment, which may trigger penalties for earlier quarters.

Finally, beware that you also could incur interest and penalties if you’re subject to the additional 0.9% Medicare tax and it isn’t withheld from your pay and you don’t make sufficient estimated tax payments. Please contact us for help with this tricky tax task.

TAX CALENDAR

October 16 — Personal returns that received an automatic six-month extension must be filed today and any tax, interest and penalties due must be paid.

  • The Financial Crimes Enforcement Network (FinCEN) Form 114, “Report of Foreign Bank and Financial Accounts (FBAR),” must be filed by today, if it hasn’t been filed already, for offshore bank account reporting. (This report received an automatic extension to today if not filed by the original due date of April 18.)
  • If a six-month extension was obtained, calendar-year C corporations should file their 2016 Form 1120 by this date.
  • If the monthly deposit rule applies, employers must deposit the tax for payments in September for Social Security, Medicare, withheld income tax and nonpayroll withholding.

October 31 — The third quarter Form 941 (“Employer’s Quarterly Federal Tax Return”) is due today and any undeposited tax must be deposited. (If your tax liability is less than $2,500, you can pay it in full with a timely filed return.) If you deposited the tax for the quarter in full and on time, you have until November 10 to file the return.

  • If you have employees, a federal unemployment tax (FUTA) deposit is due if the FUTA liability through September exceeds $500.

November 15 — If the monthly deposit rule applies, employers must deposit the tax for payments in October for Social Security, Medicare, withheld income tax, and nonpayroll withholding.

December 15 — Calendar-year corporations must deposit the fourth installment of estimated income tax for 2017.

  • If the monthly deposit rule applies, employers must deposit the tax for payments in November for Social Security, Medicare, withheld income tax and nonpayroll withholding.


Important Information: The information contained in this newsletter was not intended or written to be used and cannot be used for the purpose of (1) avoiding tax-related penalties prescribed by the Internal Revenue Code or (2) promoting or marketing any tax-related matter addressed herein.

The Tax and Business Alert is designed to provide accurate information regarding the subject matter covered. However, before completing any significant transactions based on the information contained herein, please contact us for advice on how the information applies in your specific situation. Tax and Business Alert is a trademark used herein under license. © Copyright 2017.
https://scheffelboyle.com/wp-content/uploads/2018/06/pexels-photo-921783.jpeg 571 640 jordan@bonniburns.com https://scheffelboyle.com/wp-content/uploads/2022/06/Transparent-Logo-5.png jordan@bonniburns.com2017-10-03 18:43:072018-07-31 10:35:53Tax News October 2017

Tax News September 2017

September 7, 2017

DO YOU NEED THE PROTECTION OF A D&O INSURANCE POLICY?

Your efforts toward ensuring your financial security might be focused on building up your assets through wise investing or growing your business. But protecting the assets you already have is just as important. And if you serve as a director or officer of a company, or even sit on the board of a nonprofit, your assets may be vulnerable. One way to gain some protection is to obtain coverage under a directors and officers (D&O) insurance policy.

Assessing your risks

D&O insurance helps protect an organization’s directors, officers and board members from liability resulting from management decisions. Just a few examples of how such individuals can put themselves at risk include:

  • Committing a crime,
  • Failing to disclose a conflict of interest, or
  • Breaching their fiduciary responsibilities.

But even if directors or officers do nothing wrong, they still can be held financially responsible for others’ missteps if they’re sued and the organization lacks sufficient assets to protect them. Indeed, directors and officers are vulnerable to many types of lawsuits.

Employment-related litigation — covering such claims as harassment, discrimination and wrongful termination — is particularly common, while legal action also may be brought by unhappy shareholders, lenders, customers, suppliers, competitors or government regulators.

You may feel less vulnerable if you sit on the board of directors of a nonprofit. Although nonprofits do lack shareholders, they still have stakeholders — financial contributors or other individuals with a personal interest in the organization’s mission. Thus, nonprofit directors, officers and board members can find themselves at risk if these stakeholders decide to sue its leaders for mismanagement.

Contemplating coverage

When contemplating a D&O policy, determine exactly what it covers. For example, some insurers won’t cover fraud-related claims, while others specifically exclude employment-related litigation.

Next, weigh what’s covered against the specific risks you’re most likely to face. For example, if you’re thinking about joining the board of an organization with a history of rocky employee relations, determine whether you’ll be protected from employee-related lawsuits. If you uncover potential gaps in the D&O policy, or if it includes provisions that could lead to your coverage being rescinded in certain situations, you may need to obtain additional protection through supplemental liability insurance.

Building a safeguard

Make no mistake, a D&O policy can be costly because of the high financial stakes involved. So an organization in cost-cutting mode may not wish to offer you this coverage. Nonetheless, if you’re a director, officer or board member, a policy may serve as a critical safeguard for your family’s assets. Contact our firm for an assessment of your situation.

Sidebar: D&O vs. E&O

Many people mistakenly view errors and omissions (E&O) insurance as an alternative to a directors and officers (D&O) policy. Don’t be among them; the two types of policies cover different sets of risks.

E&O insurance covers the business itself against problems stemming from potential failures in the products and services a business offers its customers; D&O insurance protects individual officers and directors from financial risk stemming from management decisions — either yours or someone else’s.


BEWARE THE ONGOING RISK OF EMPLOYEE MISCLASSIFICATION


We live in an increasingly specialized society. As such, there’s a growing subset of the workforce with distinctive skill sets that can perform high-quality services. Through independent contractor relationships, companies are able to access these services without the long-term entanglements of traditional employment.

And yet, risk remains. Classifying a worker as an independent contractor frees a business from payroll tax liability and allows it to forgo providing overtime pay, unemployment compensation, and other employee benefits. Also, independent status takes an individual off the company payroll, where an employee’s share of payroll taxes, plus income taxes, is automatically withheld.

For these reasons, the federal government views misclassifying a bona fide employee as an independent contractor as forcing a square peg into a round hole.

Key factors

The IRS has long been a primary enforcer of proper worker classification. When assessing worker classification, the agency typically looks at the:

Level of behavioral control. This means the extent to which the company instructs a worker on when and where to do the work, what tools or equipment to use, whom to hire, where to purchase supplies and so on. Also, control typically involves providing training and evaluating the worker’s performance. The more control the company exercises, the more likely the worker is an employee.

Level of financial control. Independent contractors are more likely to invest in their own equipment or facilities, incur unreimbursed business expenses, and market their services to other customers. Employees are more likely to be paid by the hour or week or some other time period; independent contractors are more likely to receive a flat fee.

Relationship of the parties. Independent contractors are often engaged for a discrete project, while employees are typically hired permanently (or at least for an indefinite period). Also, workers who serve a key business function are more likely to be classified as employees.

The IRS examines a variety of factors within each category. You need to consider all of the facts and circumstances surrounding each worker relationship.

Protective measures

Once you’ve completed your review, there are several strategies you can use to minimize your exposure. When in doubt, reclassify questionable independent contractors as employees. This may increase your tax and benefit costs, but it will eliminate reclassification risk.

From there, modify your relationships with independent contractors to better ensure compliance. For example, you might exercise less behavioral control by reducing your level of supervision or allowing workers to set their own hours or work from home.

Also, consider using an employee-leasing company. Workers leased from these firms are employees of the leasing company, which is responsible for taxes, benefits and other employer obligations.

Before and during

Sometimes a company engages an independent contractor with short-term intentions only to gradually integrate the person into its staff, creating a risk of employee misclassification. Our firm can help you review the pertinent factors and use protective measures before and duringan engagement.


UNDERSTANDING THE DIFFERENCES BETWEEN HEALTH CARE ACCOUNTS


Health care costs continue to be in the news and on everyone’s mind. As a result, tax-friendly ways to pay for these expenses are very much in play for many people. The three primary players, so to speak, are Health Savings Accounts (HSAs), Flexible Spending Arrangements (FSAs) and Health Reimbursement Arrangements (HRAs).

All provide opportunities for tax-advantaged funding of health care expenses. But what’s the difference between these three types of accounts? Here’s an overview of each one:

HSAs. If you’re covered by a qualified high-deductible health plan (HDHP), you can contribute pretax income to an employer-sponsored HSA — or make deductible contributions to an HSA you set up yourself — up to $3,400 for self-only coverage and $6,750 for family coverage for 2017. Plus, if you’re age 55 or older, you may contribute an additional $1,000.

You own the account, which can bear interest or be invested, growing tax-deferred similar to an IRA. Withdrawals for qualified medical expenses are tax-free, and you can carry over a balance from year to year.

FSAs. Regardless of whether you have an HDHP, you can redirect pretax income to an employer-sponsored FSA up to an employer-determined limit — not to exceed $2,600 in 2017. The plan pays or reimburses you for qualified medical expenses.

What you don’t use by the plan year’s end, you generally lose — though your plan might allow you to roll over up to $500 to the next year. Or it might give you a 2½-month grace period to incur expenses to use up the previous year’s contribution. If you have an HSA, your FSA is limited to funding certain “permitted” expenses.

HRAs. An HRA is an employer-sponsored arrangement that reimburses you for medical expenses. Unlike an HSA, no HDHP is required. Unlike an FSA, any unused portion typically can be carried forward to the next year. And there’s no government-set limit on HRA contributions. But only your employer can contribute to an HRA; employees aren’t allowed to contribute.

Please bear in mind that these plans could be affected by health care or tax legislation. Contact our firm for the latest information, as well as to discuss these and other ways to save taxes in relation to your health care expenses.


5 KEYS TO DISASTER PLANNING FOR INDIVIDUALS

Disaster planning is usually associated with businesses. But individuals need to prepare for worst-case scenarios, as well. Unfortunately, the topic can seem a little overwhelming. To help simplify matters, here are five keys to disaster planning that everyone should consider:

  1. Insurance.Start with your homeowners’ coverage. Make sure your policy covers flood, wind and other damage possible in your region and that its dollar amount is adequate to cover replacement costs. Also review your life and disability insurance.
  2. Asset documentation.Create a list of your bank accounts, titles, deeds, mortgages, home equity loans, investments and tax records. Inventory physical assets not only in writing (including brand names and model and serial numbers), but also by photographing or videoing them.
  3. Document storage.Keep copies of financial and personal documents somewhere other than your home, such as a safe deposit box or the distant home of a trusted friend or relative. Also consider “cloud computing” — storing digital files with a secure Web-based provider.
  4. Cash.You may not receive insurance money right away. A good rule of thumb is to set aside three to six months’ worth of living expenses in a savings or money market account. Also maintain a cash reserve in your home in a durable, fireproof safe.
  5. An emergency plan.Establish a family emergency plan that includes evacuation routes, methods of getting in touch and a safe place to meet. Because a disaster might require you to stay in your home, stock a supply kit with water, nonperishable food, batteries and a first aid kit.


Important Information: The information contained in this newsletter was not intended or written to be used and cannot be used for the purpose of (1) avoiding tax-related penalties prescribed by the Internal Revenue Code or (2) promoting or marketing any tax-related matter addressed herein.

The Tax and Business Alert is designed to provide accurate information regarding the subject matter covered. However, before completing any significant transactions based on the information contained herein, please contact us for advice on how the information applies in your specific situation. Tax and Business Alert is a trademark used herein under license. © Copyright 2017.
https://scheffelboyle.com/wp-content/uploads/2018/06/pexels-photo-921783.jpeg 571 640 jordan@bonniburns.com https://scheffelboyle.com/wp-content/uploads/2022/06/Transparent-Logo-5.png jordan@bonniburns.com2017-09-07 18:48:432018-07-31 10:35:51Tax News September 2017
Page 22 of 25«‹2021222324›»

Pages

  • 2025 Seminar Registration
  • 2025 Seminar Registration Presentation Slides
  • 2026 Summer Sneak Peek
  • About Us
  • Accounting and Office Manager
  • Accounting Clerk
  • Accounting Services
  • Administrative Assistant
  • Administrative Assistant – Columbia Office
  • Administrative Assistant – Edwardsville Office
  • Administrative Support Specialist
  • Administrative Support Specialist
  • AGCI Webinar Presentation
  • Agribusiness
  • Alton, IL
  • Andrea Suhre
  • Andrea Suhre
  • Audit & Assurance
  • Available Opportunities
  • BDO Alliance USA
  • Belleville, IL
  • Bookkeeper
  • Bookkeeper/Payroll Specialist
  • Brian Otten
  • Business Valuations
  • Careers
  • Carrollton, IL
  • Columbia, IL
  • Construction Accounting
  • Construction Newsletter
  • Construction Tax Seminar Presentation
  • Consulting Services
  • Contact Us
  • Coronavirus Resource Center
  • Cory E. Gallivan
  • Crystal Bock
  • Crystal Bock
  • Dale Holtmann
  • Daniel Phipps
  • Data Entry Assistants
  • Dennis E. Ulrich
  • E-News Sign Up
  • Edwardsville, IL
  • Elements
  • Employee Benefit Plans
  • Experienced Accountants
  • Experienced Public Accountant
  • Financial Calculators
  • Financial Institution
  • FOCUS Internship Program
  • Full-Time Interview Sign-Up
  • George Moore
  • Governmental Entities
  • Heather Clugston
  • Helpful Links
  • Highland, IL
  • Home
  • Howard Held
  • Individual Clients
  • Industries
  • Interview Thank You
  • Interview Timeslots
  • Jerseyville, IL
  • Julie Billeter
  • Julie Graham
  • Kathy Fitzgerald
  • Keith Brinkmann
  • Knowledge Center
  • Lisa Bohnenstiehl
  • Locations
  • Mark Korte
  • Marketing Specialist
  • Michael D. Ulrich
  • Michael E. Fitzgerald
  • Michael T. Brokering
  • Non-Profit Organizations
  • Office Accounting Assistant
  • Our Team
  • Outsourced Accountant
  • Part-Time Bookkeeper
  • Payroll Assistant
  • Payroll Supervisor
  • Peer Review
  • Privacy Policy
  • Privately-Held Businesses
  • Professional Affiliations
  • Recruiting Events
  • Recruiting/Human Resources Coordinator
  • Resources
  • Robyn M. Klingler
  • Russell Gregson
  • Sarah Smith
  • Scheffel Boyle News
  • Scheffel Boyle Shares
  • Scott Weber
  • Seasonal Tax Preparer
  • Services
  • SIBA Webinar Presentation
  • Sneak Peek Survey
  • Spring Tax Internship Program 2026
  • STL Ag Club Webinar Prez
  • Summer Audit Internship Program
  • Summer Audit Internship Program 2026
  • Tax Planning & Preparation
  • Tax Talks Information
  • Tax Talks Presentation
  • Testimonials
  • Webinar Presentation May 14
  • Welcome Email
  • Year-End Tax Planning Seminars
  • Accountant – Carrollton
  • Administrative Assistant – Alton Office
  • Administrative Assistant – Belleville Office
  • Administrative Assistant – Columbia Office
  • Seasonal Administrative Assistants
  • Seasonal Data Input
  • Staff Accountant

Categories

  • Blog
  • Construction
  • Coronavirus Resource Center
  • Frontpage
  • Knowledge Center
  • Scheffel News
  • Uncategorized

Archive

  • August 2026
  • May 2026
  • November 2025
  • October 2025
  • July 2025
  • February 2024
  • July 2023
  • May 2023
  • February 2023
  • January 2023
  • November 2022
  • August 2022
  • July 2022
  • June 2022
  • March 2022
  • February 2022
  • January 2022
  • December 2021
  • June 2021
  • May 2021
  • April 2021
  • March 2021
  • February 2021
  • January 2021
  • December 2020
  • November 2020
  • October 2020
  • September 2020
  • August 2020
  • July 2020
  • June 2020
  • May 2020
  • April 2020
  • March 2020
  • February 2020
  • January 2020
  • December 2019
  • November 2019
  • October 2019
  • September 2019
  • August 2019
  • July 2019
  • June 2019
  • May 2019
  • April 2019
  • March 2019
  • February 2019
  • January 2019
  • December 2018
  • November 2018
  • October 2018
  • September 2018
  • August 2018
  • July 2018
  • June 2018
  • May 2018
  • April 2018
  • March 2018
  • February 2018
  • January 2018
  • December 2017
  • November 2017
  • October 2017
  • September 2017
  • August 2017
  • July 2017
  • June 2017
  • May 2017
  • April 2017
  • March 2017
  • February 2017
  • January 2017
  • December 2016
  • October 2016
  • September 2016
  • August 2016
  • July 2016
  • May 2016
  • April 2016
  • March 2016
  • February 2016
  • January 2016
  • December 2015
  • November 2015
  • August 2015
  • July 2015
  • June 2015
  • February 2015
  • January 2015
  • December 2014
  • November 2014
  • September 2014
  • August 2014
  • March 2014
  • February 2014
  • December 2013
  • November 2013
  • October 2013
  • August 2013
  • July 2013
  • June 2013
  • May 2013
  • February 2013
  • January 2013

About Us


Serving St. Louis, the Metro-East and Southwestern Illinois since 1924.

Knowledge Center

  • New Rules Could Increase Taxable Income for GamblersAugust 24, 2026 - 3:20 pm
  • IRS Notice CP53E and the Rise of Refund-Related ScamsMay 18, 2026 - 9:55 am
  • Potential Refund Deadline Extensions Under the Kwong CaseMay 7, 2026 - 11:40 am

Quick Links

  • Services
  • Clients & Industries
  • Our Team
  • Scheffel Boyle News
  • Careers

 Contact Us

Alton, IL: 618.465.4288
Edwardsville, IL: 618.656.1206
Belleville, IL: 618.277.8100
Highland, IL: 618.654.9895
Jerseyville, IL: 618.498.6841
Columbia, IL: 618.281.7605
Carrollton, IL: 217.942.3821

© Copyright 2021 Scheffel Boyle — All rights reserved
  • Site Map
  • Privacy Policy
Scroll to top Scroll to top Scroll to top