Loading
Scheffel Boyle
  • Home
  • About Us
    • Our Team
    • Our Values
    • Scheffel Boyle News
    • Professional Affiliations
    • Client Testimonials
    • Peer Review
    • Scheffel Boyle Shares
    • BDO Alliance USA
  • Services
    • Tax Planning & Preparation
    • Audit & Assurance
    • Accounting Services
    • Consulting Services
    • Financial Advisory
  • Clients & Industries
    • Construction
    • Financial Institutions
    • Agribusiness
    • Governmental Entities
    • Non-Profit Organizations
    • Privately-Held Businesses
    • Individual Clients
    • Employee Benefit Plans
  • Resources
    • Knowledge Center
    • Coronavirus Resource Center
    • Helpful Links
  • Careers
    • Benefits
    • Available Opportunities
    • College Students
  • Contact Us
    • Locations
      • Alton, IL
      • Belleville, IL
      • Carrollton, IL
      • Columbia, IL
      • Edwardsville, IL
      • Highland, IL
      • Jerseyville, IL
  • Click to open the search input field Click to open the search input field Search
  • Menu Menu
  • Link to Facebook
  • Link to LinkedIn

Write-Off Hunger Raises Thousands

October 4, 2017

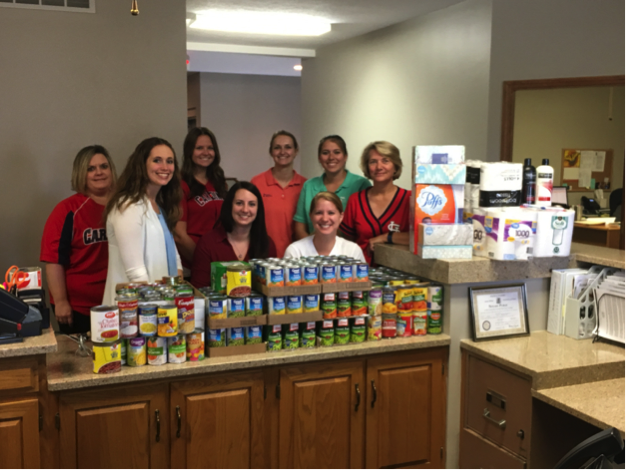
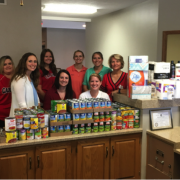
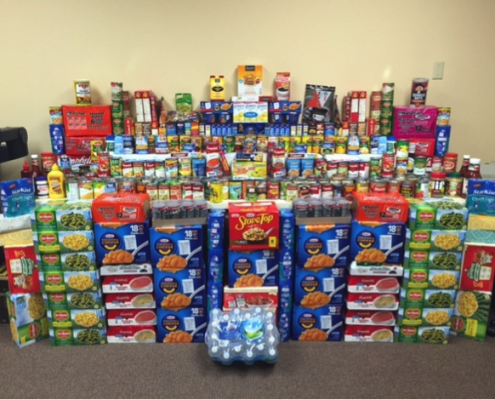
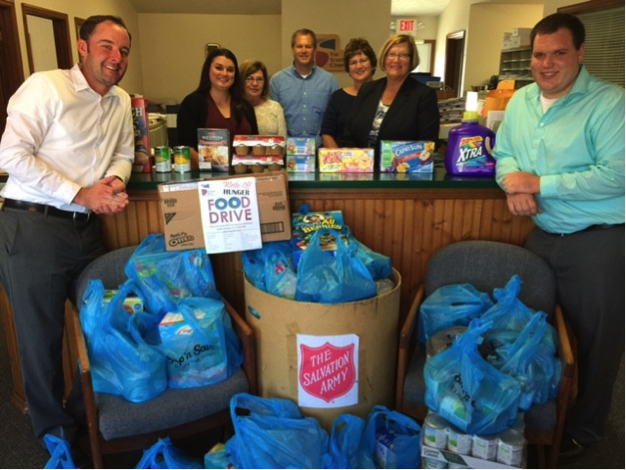
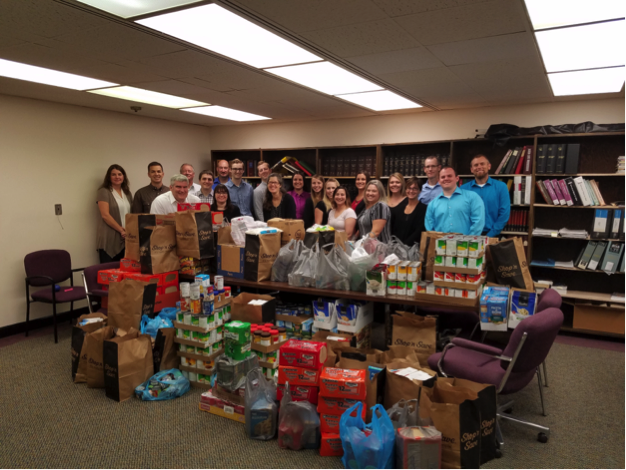
We recently teamed together for our annual Scheffel Boyle Shares project. Each year, we plan philanthropic activities throughout our offices to give back to our local communities. This year, our employees organized the “Write-Off Hunger” food drive which culminated in the collection of more than 5,500 food items to be donated to local food pantries!

Each of our offices strategized and found creative ways to raise the most donations possible. One office organized a “Cars for Cans” car wash in their parking lot where the fee for a wash was $5 or 5 items of non-perishable food items. Another took to social media to raise funds and “coupon shopped” to get the most out of their donated dollars. Each office exercised their entrepreneurial spirit to find innovative ways of collecting donations for the drive. We are so proud of all they accomplished!

Firm leadership also organized two “Cardinals for Cans” days, where employees could wear their St. Louis Cardinal gear for a fee of $5 or 5 cans. In addition, we also hosted a “Dress for Success” day where if an employee were to forego their normal casual Friday and dress for success instead, the firm would give $5 in their name toward their office’s donation fund.

While it was a firm-wide project, each office will donate what they raised to their own local community food bank. Some organizations who will receive donations from Write-Off Hunger include the Salvation Army Food Pantry of Jerseyville, the Glen-Ed Food Pantry, the Crisis Food Center, the Carrollton Food Pantry, Community Care Center, the Highland Area Christian Service Ministry, and the Community Hope Center, among others.


https://scheffelboyle.com/wp-content/uploads/2018/06/pic2.png 470 626 jordan@bonniburns.com https://scheffelboyle.com/wp-content/uploads/2022/06/Transparent-Logo-5.png jordan@bonniburns.com2017-10-04 18:40:122018-07-31 10:35:29Write-Off Hunger Raises Thousands

Scheffel Boyle Named a “Best Consulting Firm”

October 3, 2017

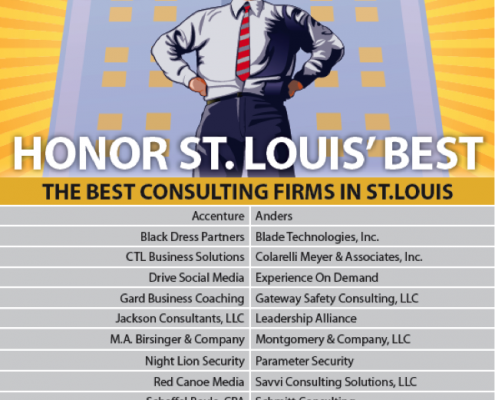
We are proud to announce that we were named a “Best Consulting Firm” by St. Louis Small Business Monthly for 2017! Thank you to all who nominated us and to our employees for always going above and beyond for our clients.

https://scheffelboyle.com/wp-content/uploads/2018/06/best-consulting-2017-1.png 663 645 jordan@bonniburns.com https://scheffelboyle.com/wp-content/uploads/2022/06/Transparent-Logo-5.png jordan@bonniburns.com2017-10-03 18:46:572019-09-20 08:11:07Scheffel Boyle Named a “Best Consulting Firm”

Tax News October 2017

October 3, 2017

HOW TO STEER CLEAR OF TAX ISSUES RELATED TO SHAREHOLDER LOANS

Owners occasionally need to borrow funds from their businesses. If your business is structured as a corporation and it has extra cash on hand, a shareholder loan can be a convenient and low-cost option — but it’s important to treat the transaction as a bona fide loan. If you don’t, the IRS may claim you received a taxable dividend or compensation payment rather than a loan.

Taking a closer look

A corporation can make de minimis loans of $10,000 or less to shareholders without paying interest. But, if all of the loans from the corporation to a shareholder add up to more than $10,000, the advances may be subject to a complicated set of below-market interest rules unless you charge what the IRS considers an “adequate” rate of interest. Each month the IRS publishes its applicable federal rates (AFRs), which vary depending on the term of the loan.

Right now, although interest rates are starting to rise, they’re still near historic lows, making it a good time to borrow money. For example, in July 2017, the adjusted AFR for short-term loans (of not more than three years) was only 1.22% (up from 0.71% in July 2016). The rate was 1.89% (up from 1.43% in July 2016) for midterm loans (with terms ranging from more than three years to not more than nine years).

The AFRs are typically below what a bank would charge. As long as the corporation charged interest at the AFR (or higher), the loan would be exempt from the complicated below-market interest rules the IRS imposes.

The interest rate for a demand loan — which is payable whenever the corporation wants to collect it — isn’t fixed when the loan is set up. Instead it varies depending on market conditions. So, calculating the correct AFR for a demand loan is more complicated than it is for a term loan. In general, it’s easier to administer a shareholder loan with a prescribed term than a demand note.

Staying under market

If a corporation lends money to a shareholder at an interest rate that’s below the AFR, the IRS requires it to impute interest using the below-market interest rules. These calculations can be complicated. The amount of incremental imputed interest (beyond what the corporation already charges the shareholder) depends on when the loan was set up and whether it’s a demand or term loan. There are also tax consequences for this imputed interest to both the corporation and the shareholder.

Additionally, the IRS may argue that the loan should be reclassified as either a dividend or additional compensation. The corporation may deduct the latter, but it will also be subject to payroll taxes. Both dividends and additional compensation would be taxable income to the shareholder personally, however.

Making it bona fide

When deciding whether payments made to shareholders qualify as bona fide loans, the IRS considers a variety of factors. It assesses the size of the loan, as well as the corporation’s history of earnings, dividend payments and loan repayments. It also looks at the shareholder’s ability to repay the loan and power to make corporate decisions.

In addition, the IRS will factor in whether you’ve executed a formal, written note that specifies repayment terms — including the interest rate, maturity date and collateral.

Getting started

Under the right circumstances, a shareholder loan could be a smart tax planning move to make this year. Contact our firm to help you set up and monitor your shareholder loans to ensure compliance with the IRS rules.


WILLS AND LIVING TRUSTS: ESTATE PLANNING IMPERATIVES

Well-crafted, up-to-date estate planning documents are an imperative for everyone. They also can help ease the burdens on your family during a difficult time. Two important examples: wills and living trusts.

The will

A will is a legal document that arranges for the distribution of your property after you die and allows you to designate a guardian for minor children or other dependents. It should name the executor or personal representative who’ll be responsible for overseeing your estate as it goes through probate. (Probate is the court-supervised process of paying any debts and taxes and distributing your property after you die.) To be valid, a will must meet the legal requirements in your state.

If you die without a will (that is, “intestate”), the state will appoint an administrator to determine how to distribute your property based on state law. The administrator also will decide who will assume guardianship of any minor children or other dependents. Bottom line? Your assets may be distributed — and your dependents provided for — in ways that differ from what you would have wanted.

The living trust

Because probate can be time-consuming, expensive and public, you may prefer to avoid it. A living trust can help. It’s a legal entity to which you, as the grantor, transfer title to your property. During your life, you can act as the trustee, maintaining control over the property in the trust. On your death, the person (such as a family member or advisor) or institution (such as a bank or trust company) you’ve named as the successor trustee distributes the trust assets to the beneficiaries you’ve named.

Assets held in a living trust avoid probate — with very limited exceptions. Another benefit is that the successor trustee can take over management of the trust assets should you become incapacitated.

Having a living trust doesn’t eliminate the need for a will. For example, you can’t name a guardian for minor children or other dependents in a trust. However, a “pour over” will can direct that assets you own outside the living trust be transferred to it on your death.

Other documents

There are other documents that can complement a will and living trust. A “letter of instruction,” for example, provides information that your family will need after your death. In it, you can express your desires for the memorial service, as well as the contact information for your employer, accountant and any other important advisors. (Note: It’s not a legal document.)

Also consider powers of attorney. A durable power of attorney for property allows you to appoint someone to act on your behalf on financial matters should you become incapacitated. A power of attorney for health care covers medical decisions and also takes effect if you become incapacitated. The person to whom you’ve transferred this power — your health care agent — can make medical decisions on your behalf.

Foundational elements

These are just a few of the foundational elements of a strong estate plan. We can work with you and your attorney to address the tax issues involved.

SHOULD YOU CHANGE YOUR BUSINESS – OR TRANSFORM IT?

As its market and technological needs evolve, every company needs to change. There’s even a formal term for the undertaking: “change management.” From an operational standpoint, change involves opening up the hood and switching out old engine parts for new ones. Even if it affects the business as a whole, change means focusing on specific areas and making alterations over relatively short periods.

At some point in the existence of many companies, the organization needs to go beyond change to transformation. This is much different. Business transformations aren’t so much about switching out parts as overhauling the entire engine, possibly modifying the frame and even applying a new coat of paint. Let’s look a little more closely at the distinction.

Reinvent yourself

Say a large commercial construction company was having trouble meeting its sales goals because of environmental regulations. So, it decided to augment its sales teams with environmental engineers who could better assess the compliance impact. The company applied change management principles — such as building a case for the idea and adjusting its business culture — and was successful. This was no doubt an important change, but the business itself wasn’t transformed.

The objective of a true transformation is to essentially reinvent the company and implement a new business model. And that model needs to be a carefully, formally devised chain of interlocking strategic initiatives that apply to the entire organization.

Perhaps the most obvious and universal example of a business transformation is Apple. The technology giant, once a head-to-head competitor with IBM on the personal computer market, found itself struggling in the 1990s. So, under the tutelage of the late Steve Jobs, it transformed itself into a mobile technology company. It still makes computers, of course, but the company’s transformative success can really be attributed to its mobile devices and operating systems.

Think and act wisely

Every business transformation differs based on the history, nature and size of the company in question. But there are best practices to keep in mind. For example, start with your customers, visualizing what they need (even if they don’t know it yet). Also, build a chain of initiatives, so you’re not trying to do everything all at once. And use metrics, so you can track specific dollar amounts and productivity goals throughout the transformation.

Above all, be ready for anything. Even the best-planned transformations can produce unpredictable results. So keep expectations in line and take a measured, patient approach to every initiative involved.

Bring along help

Successful business transformations can be spectacular and profitable. But, make no mistake, the risk level is high. So if you decide to embark on this journey, bring along your trusted financial, legal and strategic advisors.

3 STRATEGIES FOR HANDLING ESTIMATED TAX PAYMENTS

In today’s economy, many individuals are self-employed. Others generate income from interest, rent or dividends. If these circumstances sound familiar, you might be at risk of penalties if you don’t pay enough tax during the year through estimated tax payments and withholding. Here are three strategies to help avoid underpayment penalties:

  1. Know the minimum payment rules.For you to avoid penalties, your estimated payments and withholding must equal at least:
  • 90% of your tax liability for the year,
  • 110% of your tax for the previous year, or
  • 100% of your tax for the previous year if your adjusted gross income for the previous year was $150,000 or less ($75,000 or less if married filing separately).
  1. Use the annualized income installment method.This method often benefits taxpayers who have large variability in income by month due to bonuses, investment gains and losses, or seasonal income — especially if it’s skewed toward year end. Annualizing calculates the tax due based on income, gains, losses and deductions through each “quarterly” estimated tax period.
  2. Estimate your tax liability and increase withholding.If, as year end approaches, you determine you’ve underpaid, consider having the tax shortfall withheld from your salary or year-end bonus by December 31. Because withholding is considered to have been paid ratably throughout the year, this is often a better strategy than making up the difference with an increased quarterly tax payment, which may trigger penalties for earlier quarters.

Finally, beware that you also could incur interest and penalties if you’re subject to the additional 0.9% Medicare tax and it isn’t withheld from your pay and you don’t make sufficient estimated tax payments. Please contact us for help with this tricky tax task.

TAX CALENDAR

October 16 — Personal returns that received an automatic six-month extension must be filed today and any tax, interest and penalties due must be paid.

  • The Financial Crimes Enforcement Network (FinCEN) Form 114, “Report of Foreign Bank and Financial Accounts (FBAR),” must be filed by today, if it hasn’t been filed already, for offshore bank account reporting. (This report received an automatic extension to today if not filed by the original due date of April 18.)
  • If a six-month extension was obtained, calendar-year C corporations should file their 2016 Form 1120 by this date.
  • If the monthly deposit rule applies, employers must deposit the tax for payments in September for Social Security, Medicare, withheld income tax and nonpayroll withholding.

October 31 — The third quarter Form 941 (“Employer’s Quarterly Federal Tax Return”) is due today and any undeposited tax must be deposited. (If your tax liability is less than $2,500, you can pay it in full with a timely filed return.) If you deposited the tax for the quarter in full and on time, you have until November 10 to file the return.

  • If you have employees, a federal unemployment tax (FUTA) deposit is due if the FUTA liability through September exceeds $500.

November 15 — If the monthly deposit rule applies, employers must deposit the tax for payments in October for Social Security, Medicare, withheld income tax, and nonpayroll withholding.

December 15 — Calendar-year corporations must deposit the fourth installment of estimated income tax for 2017.

  • If the monthly deposit rule applies, employers must deposit the tax for payments in November for Social Security, Medicare, withheld income tax and nonpayroll withholding.


Important Information: The information contained in this newsletter was not intended or written to be used and cannot be used for the purpose of (1) avoiding tax-related penalties prescribed by the Internal Revenue Code or (2) promoting or marketing any tax-related matter addressed herein.

The Tax and Business Alert is designed to provide accurate information regarding the subject matter covered. However, before completing any significant transactions based on the information contained herein, please contact us for advice on how the information applies in your specific situation. Tax and Business Alert is a trademark used herein under license. © Copyright 2017.
https://scheffelboyle.com/wp-content/uploads/2018/06/pexels-photo-921783.jpeg 571 640 jordan@bonniburns.com https://scheffelboyle.com/wp-content/uploads/2022/06/Transparent-Logo-5.png jordan@bonniburns.com2017-10-03 18:43:072018-07-31 10:35:53Tax News October 2017

Tax News September 2017

September 7, 2017

DO YOU NEED THE PROTECTION OF A D&O INSURANCE POLICY?

Your efforts toward ensuring your financial security might be focused on building up your assets through wise investing or growing your business. But protecting the assets you already have is just as important. And if you serve as a director or officer of a company, or even sit on the board of a nonprofit, your assets may be vulnerable. One way to gain some protection is to obtain coverage under a directors and officers (D&O) insurance policy.

Assessing your risks

D&O insurance helps protect an organization’s directors, officers and board members from liability resulting from management decisions. Just a few examples of how such individuals can put themselves at risk include:

  • Committing a crime,
  • Failing to disclose a conflict of interest, or
  • Breaching their fiduciary responsibilities.

But even if directors or officers do nothing wrong, they still can be held financially responsible for others’ missteps if they’re sued and the organization lacks sufficient assets to protect them. Indeed, directors and officers are vulnerable to many types of lawsuits.

Employment-related litigation — covering such claims as harassment, discrimination and wrongful termination — is particularly common, while legal action also may be brought by unhappy shareholders, lenders, customers, suppliers, competitors or government regulators.

You may feel less vulnerable if you sit on the board of directors of a nonprofit. Although nonprofits do lack shareholders, they still have stakeholders — financial contributors or other individuals with a personal interest in the organization’s mission. Thus, nonprofit directors, officers and board members can find themselves at risk if these stakeholders decide to sue its leaders for mismanagement.

Contemplating coverage

When contemplating a D&O policy, determine exactly what it covers. For example, some insurers won’t cover fraud-related claims, while others specifically exclude employment-related litigation.

Next, weigh what’s covered against the specific risks you’re most likely to face. For example, if you’re thinking about joining the board of an organization with a history of rocky employee relations, determine whether you’ll be protected from employee-related lawsuits. If you uncover potential gaps in the D&O policy, or if it includes provisions that could lead to your coverage being rescinded in certain situations, you may need to obtain additional protection through supplemental liability insurance.

Building a safeguard

Make no mistake, a D&O policy can be costly because of the high financial stakes involved. So an organization in cost-cutting mode may not wish to offer you this coverage. Nonetheless, if you’re a director, officer or board member, a policy may serve as a critical safeguard for your family’s assets. Contact our firm for an assessment of your situation.

Sidebar: D&O vs. E&O

Many people mistakenly view errors and omissions (E&O) insurance as an alternative to a directors and officers (D&O) policy. Don’t be among them; the two types of policies cover different sets of risks.

E&O insurance covers the business itself against problems stemming from potential failures in the products and services a business offers its customers; D&O insurance protects individual officers and directors from financial risk stemming from management decisions — either yours or someone else’s.


BEWARE THE ONGOING RISK OF EMPLOYEE MISCLASSIFICATION


We live in an increasingly specialized society. As such, there’s a growing subset of the workforce with distinctive skill sets that can perform high-quality services. Through independent contractor relationships, companies are able to access these services without the long-term entanglements of traditional employment.

And yet, risk remains. Classifying a worker as an independent contractor frees a business from payroll tax liability and allows it to forgo providing overtime pay, unemployment compensation, and other employee benefits. Also, independent status takes an individual off the company payroll, where an employee’s share of payroll taxes, plus income taxes, is automatically withheld.

For these reasons, the federal government views misclassifying a bona fide employee as an independent contractor as forcing a square peg into a round hole.

Key factors

The IRS has long been a primary enforcer of proper worker classification. When assessing worker classification, the agency typically looks at the:

Level of behavioral control. This means the extent to which the company instructs a worker on when and where to do the work, what tools or equipment to use, whom to hire, where to purchase supplies and so on. Also, control typically involves providing training and evaluating the worker’s performance. The more control the company exercises, the more likely the worker is an employee.

Level of financial control. Independent contractors are more likely to invest in their own equipment or facilities, incur unreimbursed business expenses, and market their services to other customers. Employees are more likely to be paid by the hour or week or some other time period; independent contractors are more likely to receive a flat fee.

Relationship of the parties. Independent contractors are often engaged for a discrete project, while employees are typically hired permanently (or at least for an indefinite period). Also, workers who serve a key business function are more likely to be classified as employees.

The IRS examines a variety of factors within each category. You need to consider all of the facts and circumstances surrounding each worker relationship.

Protective measures

Once you’ve completed your review, there are several strategies you can use to minimize your exposure. When in doubt, reclassify questionable independent contractors as employees. This may increase your tax and benefit costs, but it will eliminate reclassification risk.

From there, modify your relationships with independent contractors to better ensure compliance. For example, you might exercise less behavioral control by reducing your level of supervision or allowing workers to set their own hours or work from home.

Also, consider using an employee-leasing company. Workers leased from these firms are employees of the leasing company, which is responsible for taxes, benefits and other employer obligations.

Before and during

Sometimes a company engages an independent contractor with short-term intentions only to gradually integrate the person into its staff, creating a risk of employee misclassification. Our firm can help you review the pertinent factors and use protective measures before and duringan engagement.


UNDERSTANDING THE DIFFERENCES BETWEEN HEALTH CARE ACCOUNTS


Health care costs continue to be in the news and on everyone’s mind. As a result, tax-friendly ways to pay for these expenses are very much in play for many people. The three primary players, so to speak, are Health Savings Accounts (HSAs), Flexible Spending Arrangements (FSAs) and Health Reimbursement Arrangements (HRAs).

All provide opportunities for tax-advantaged funding of health care expenses. But what’s the difference between these three types of accounts? Here’s an overview of each one:

HSAs. If you’re covered by a qualified high-deductible health plan (HDHP), you can contribute pretax income to an employer-sponsored HSA — or make deductible contributions to an HSA you set up yourself — up to $3,400 for self-only coverage and $6,750 for family coverage for 2017. Plus, if you’re age 55 or older, you may contribute an additional $1,000.

You own the account, which can bear interest or be invested, growing tax-deferred similar to an IRA. Withdrawals for qualified medical expenses are tax-free, and you can carry over a balance from year to year.

FSAs. Regardless of whether you have an HDHP, you can redirect pretax income to an employer-sponsored FSA up to an employer-determined limit — not to exceed $2,600 in 2017. The plan pays or reimburses you for qualified medical expenses.

What you don’t use by the plan year’s end, you generally lose — though your plan might allow you to roll over up to $500 to the next year. Or it might give you a 2½-month grace period to incur expenses to use up the previous year’s contribution. If you have an HSA, your FSA is limited to funding certain “permitted” expenses.

HRAs. An HRA is an employer-sponsored arrangement that reimburses you for medical expenses. Unlike an HSA, no HDHP is required. Unlike an FSA, any unused portion typically can be carried forward to the next year. And there’s no government-set limit on HRA contributions. But only your employer can contribute to an HRA; employees aren’t allowed to contribute.

Please bear in mind that these plans could be affected by health care or tax legislation. Contact our firm for the latest information, as well as to discuss these and other ways to save taxes in relation to your health care expenses.


5 KEYS TO DISASTER PLANNING FOR INDIVIDUALS

Disaster planning is usually associated with businesses. But individuals need to prepare for worst-case scenarios, as well. Unfortunately, the topic can seem a little overwhelming. To help simplify matters, here are five keys to disaster planning that everyone should consider:

  1. Insurance.Start with your homeowners’ coverage. Make sure your policy covers flood, wind and other damage possible in your region and that its dollar amount is adequate to cover replacement costs. Also review your life and disability insurance.
  2. Asset documentation.Create a list of your bank accounts, titles, deeds, mortgages, home equity loans, investments and tax records. Inventory physical assets not only in writing (including brand names and model and serial numbers), but also by photographing or videoing them.
  3. Document storage.Keep copies of financial and personal documents somewhere other than your home, such as a safe deposit box or the distant home of a trusted friend or relative. Also consider “cloud computing” — storing digital files with a secure Web-based provider.
  4. Cash.You may not receive insurance money right away. A good rule of thumb is to set aside three to six months’ worth of living expenses in a savings or money market account. Also maintain a cash reserve in your home in a durable, fireproof safe.
  5. An emergency plan.Establish a family emergency plan that includes evacuation routes, methods of getting in touch and a safe place to meet. Because a disaster might require you to stay in your home, stock a supply kit with water, nonperishable food, batteries and a first aid kit.


Important Information: The information contained in this newsletter was not intended or written to be used and cannot be used for the purpose of (1) avoiding tax-related penalties prescribed by the Internal Revenue Code or (2) promoting or marketing any tax-related matter addressed herein.

The Tax and Business Alert is designed to provide accurate information regarding the subject matter covered. However, before completing any significant transactions based on the information contained herein, please contact us for advice on how the information applies in your specific situation. Tax and Business Alert is a trademark used herein under license. © Copyright 2017.
https://scheffelboyle.com/wp-content/uploads/2018/06/pexels-photo-921783.jpeg 571 640 jordan@bonniburns.com https://scheffelboyle.com/wp-content/uploads/2022/06/Transparent-Logo-5.png jordan@bonniburns.com2017-09-07 18:48:432018-07-31 10:35:51Tax News September 2017

Tax News August 2017

August 8, 2017

SHOULD YOU CONVERT FROM A C CORPORATION TO AN S CORPORATION?

Many private business owners elect to incorporate, turning their companies into C corporations. But, at some point, you may consider converting to an S corporation. This isn’t necessarily a bad idea, but it’s important to know the ramifications involved.

Similarities and differences

S and C corporations use many of the same recordkeeping practices. Both types of entities maintain books, records and bank accounts separate from those of their owners. They also follow state rules regarding annual directors meetings, fees and administrative filings. And both must pay and withhold payroll taxes for working owners who are active in the business.

There are, however, a few important distinctions. First, S corporations don’t incur corporate-level tax, so they don’t report federal (and possibly state) income tax expenses on their income statements. Also, S corporations generally don’t report prepaid income taxes, income taxes payable, or deferred income tax assets and liabilities on their balance sheets.

As an S corporation owner, you’d pay tax at the personal level on your share of the corporation’s income and gains. The combined personal tax obligations of S corporation owners can be significant at higher income levels.

Dividends vs. distributions

Other financial reporting differences between a C corporation and S corporation are more subtle. For instance, when C corporations pay dividends, they’re taxed twice: They pay tax at the corporate level when the company files its annual tax return, and the individual owners pay again when dividends and liquidation proceeds are taxed at the personal level.

When S corporations pay distributions — the name for dividends paid by S corporations — the payout generally isn’t subject to personal-level tax as long as the shares have positive tax “basis.” (S corporation basis is typically a function of capital contributions, earnings and distributions.)

Risk of tax audits

C corporations may be tempted to pay owners deductible above-market salaries to get cash out of the business and avoid the double taxation that comes with dividends. Conversely, S corporation owners may try to maximize tax-free distributions and pay owners below-market salaries to minimize payroll taxes.

The IRS is on the lookout for both scenarios. Corporations that compensate owners too much or too little may find themselves under audit. Regardless of entity type, an owner’s compensation should always be commensurate with his or her skills, experience and business involvement.

The right decision

For businesses that qualify (see sidebar), an S corporation conversion may be a wise move. But, as noted, there are rules and risks to consider. Also, as of this writing, there are tax reform proposals under consideration in Washington that could affect the impact of a conversion. Our firm can help you make the right decision.

Sidebar: Which companies can elect S status?

Not every private business is eligible to be an S corporation. In order to elect S status, a company must:

  • Be a domestic corporation,
  • Have only allowable shareholders (individuals, certain trusts and estates, but not partnerships, corporations or nonresident alien shareholders),
  • Have no more than 100 shareholders,
  • Have only one class of stock, and
  • Not be an ineligible corporation, including certain financial institutions, insurance companies, and domestic international sales corporations.

All shareholders must consent to the S election by signing Form 2553, “Election by a Small Business Corporation.”


COOL DOWN WITH A DIP INTO YOUR TAX RECORDS


In many parts of the country, the dog days of summer are a good time to stay inside. If you’re looking for a practical activity while you beat the heat, consider organizing your tax records. Granted, it may not be as exhilarating as jumping off the high dive, but a dip into these important documents now may save you a multitude of headaches later.

Tax law rules

Generally, you should keep tax-related records as long as the IRS has the ability to audit your return or assess additional taxes — in other words, until the statute of limitations expires. That means three years after you file your return or, if later, three years after the tax return’s original due date.

In some cases, the statute of limitations extends beyond three years. If you understate your adjusted gross income by more than 25%, for example, the period jumps to six years. And there’s no statute of limitations if you fail to file a tax return or file a fraudulent one.

Longer periods

Although the IRS statute of limitations is a good rule of thumb, there are exceptions to consider. For example, it’s wise to keep your tax returns themselves indefinitely because you never know when you’ll need a copy of your individual income tax return.

For one thing, the IRS often destroys original returns after four or five years. So if the IRS comes back 10 years later and claims you never filed a return for a particular year, it can assess tax for that year even though the limitations period for properly filed returns has long since expired. As you can see, it would be difficult to defend yourself without a copy of your tax return.

W-2 forms also are important to keep at least until you start receiving Social Security benefits. You may need them if there’s a question about your work record or earnings in a particular year.

Property and investments

If you have property records, it’s ideal to keep closing documents and records related to initial purchases and capital improvements until at least three years (preferably six years in case you understated your income by more than 25%) after you file your return for the year in which you sell the property.

When it comes to sales of stocks or other securities, retain purchase statements and trade confirmations until at least three years (preferably six years) after you file your return for the year in which you sell these stocks or other securities.

Grains of sand

Many years’ worth of tax and financial records can accumulate like grains of sand on your favorite beach. So the better your documentation is organized, the easier time you’ll have filing your return every year and dealing with any IRS surprises. Our firm can assist you in determining what you should keep.


IRS PERMITS HIGH-EARNER ROTH IRA ROLLOVER OPPORTUNITY


Are you a highly compensated employee (HCE) approaching retirement? If so, and you have a 401(k), you should consider a potentially useful tax-efficient IRA rollover technique. The IRS has specific rules about how participants such as you can allocate accumulated 401(k) plan assets based on pretax and after-tax employee contributions between standard IRAs and Roth IRAs.

High-earner dilemma

In 2017, the top pretax contribution that participants can make to a 401(k) is $18,000 ($24,000 for those 50 and older). Plans that permit after-tax contributions (several do) allow participants to contribute a total of $54,000 ($36,000 above the $18,000 pretax contribution limit). While some highly compensated supersavers may have significant accumulations of after-tax contributions in their 401(k) accounts, the tax law income caps block the highest paid HCEs from opening a Roth IRA.

However, under IRS rules, these participants can roll dollars representing their after-tax 401(k) contributions directly into a new Roth IRA when they retire or no longer work for the companies. Thus, they’ll ultimately be able to withdraw the dollars representing the original after-tax contributions — and subsequent earnings on those dollars — tax-free.

An example

Participants can contribute rollover dollars to conventional and Roth IRAs on a pro-rata basis. For example, suppose a retiring participant had $1 million in his 401(k) plan account, $600,000 of which represents contributions. Suppose further that 70% of that $600,000 represents pretax contributions, and 30% is from after-tax contributions. IRS guidance clarifies that the participant can roll $700,000 (70% of the $1 million) into a conventional IRA, and $300,000 (30% of the $1 million) into a Roth IRA.

The IRS rules allow the retiree to roll over not only the after-tax contributions, but the earnings on those after-tax contributions (40% of the $300,000, or $120,000) to the Roth IRA provided that the $120,000 will be taxable for the year of the rollover.

Alternatively, the IRS rules allow the retiree to delay taxation on the earnings attributable to the after-tax contributions ($120,000) until the money is distributed by contributing that amount to a conventional IRA, and the remaining $180,000 to the Roth IRA.

Under each approach, the subsequent growth in the Roth IRA will be tax-free when withdrawn. Partial rollovers can also be made, and the same principles apply.

Golden years ahead

HCEs face some complex decisions when it comes to retirement planning. Let our firm help you make the right moves now for your golden years ahead.

SHIFTING CAPITAL GAINS TO YOUR CHILDREN


If you’re an investor looking to save tax dollars, your kids might be able to help you out. Giving appreciated stock or other investments to your children can minimize the impact of capital gains taxes.

For this strategy to work best, however, your child must not be subject to the “kiddie tax.” This tax applies your marginal rate to unearned income in excess of a specified threshold ($2,100 in 2017) received by your child who at the end of the tax year was either: 1) under 18, 2) 18 (but not older) and whose earned income didn’t exceed one-half of his or her own support for the year (excluding scholarships if a full-time student), or 3) a full-time student age 19 to 23 who had earned income that didn’t exceed half of his or her own support (excluding scholarships).

Here’s how it works: Say Bill, who’s in the top tax bracket, wants to help his daughter, Molly, buy a new car. Molly is 22 years old, just out of college, and currently looking for a job — and, for purposes of the example, won’t be considered a dependent for 2017.

Even if she finds a job soon, she’ll likely be in the 10% or 15% tax bracket this year. To finance the car, Bill plans to sell $20,000 of stock that he originally purchased for $2,000. If he sells the stock, he’ll have to pay $3,600 in capital gains tax (20% of $18,000), plus the 3.8% net investment income tax, leaving $15,716 for Molly. But if Bill gives the stock to Molly, she can sell it tax-free and use the entire $20,000 to buy a car. (The capital gains rate for the two lowest tax brackets is generally 0%.)


Important Information: The information contained in this newsletter was not intended or written to be used and cannot be used for the purpose of (1) avoiding tax-related penalties prescribed by the Internal Revenue Code or (2) promoting or marketing any tax-related matter addressed herein.

The Tax and Business Alert is designed to provide accurate information regarding the subject matter covered. However, before completing any significant transactions based on the information contained herein, please contact us for advice on how the information applies in your specific situation. Tax and Business Alert is a trademark used herein under license. © Copyright 2017.
https://scheffelboyle.com/wp-content/uploads/2018/01/pexels-photo-297755.jpeg 417 640 jordan@bonniburns.com https://scheffelboyle.com/wp-content/uploads/2022/06/Transparent-Logo-5.png jordan@bonniburns.com2017-08-08 18:50:222018-07-31 10:35:57Tax News August 2017

Illinois Income Tax Law Changes for 2017

July 21, 2017

The Illinois House recently followed the Senate’s lead in overriding Governor Rauner’s veto of the Illinois budget. Senate Bill 9 raises around $5 billion of new permanent income taxes. The individual income tax rates increased from 3.75% to 4.95%, while the corporate rates rose from 5.25% to 7.0%. These rate increases were effective on July 1, 2017.

The difficulty with the midyear tax increase is that the law imposes the new tax rate effective July 1, 2017 so that net income is taxed at the 3.75% rate from January 1 through June 30, 2017.  Likewise an income tax rate of 4.95% is imposed on the income earned from July 1 through December 31, 2017.  Illinois taxpayers are provided two options to calculate income subject to different rates in the same tax year.  A taxpayer may divide its full year net income proportionally based on the number of months subject to the former rate and the new rate.  This would effectively result in a tax rate of 4.35% to be applied to the entire 2017 tax year for individuals.  Alternatively, a taxpayer may elect to specifically account for items of income and deduction based on when they were generated during the tax year.  See the following example for this election.


Example: A husband and wife file a joint Illinois income tax return for 2017. The husband earns $75,000 plus a $30,000 bonus received in January 2017. The wife earns a salary of $50,000 plus she sold a stock and received a capital gain of $10,000 in November 2017. To the best of our knowledge, the income tax calculations would be as follows:

1/1/17 – 6/30/17 7/1/17 – 12/31/17 TOTAL
Husband salary $37,500 $37,500 $75,000
Wife salary  25,000 25,000 50,000
Husband bonus received in January  30,000 —— 30,000
Wife capital gain in November —— 10,000 10,000
Total income $92,500 $72,500 $165,000
Tax rate  3.75% 4.95%
Tax $3,469 $3,589 $7,058


If the taxpayers did not make the election to specifically allocate income, the use of the blended rate of 4.35% would result in an Illinois income tax of $7,178 ($165,000 * 4.35%).  Therefore, the election results in savings to the taxpayers of $120 ($7,178 – $7,058).  Note that this illustration does not factor in other adjustments that may impact the calculation such as exemptions, adjustments, etc.

The corporate income tax calculation will work in the same manner. As you can see, additional work will be required on your part in breaking down your income as to whether it was received prior to July 1 or after July 1.

For those of you with businesses who have employees, obviously the Illinois withholding on wages paid after June 30, 2017 will be required to be withheld at the 4.95% rate.

Other changes included in the new law include the elimination of personal exemptions, education expense credit and the real estate tax credit for single filers with income of $250,000 per year and for joint filers with income of $500,000 per year starting in 2017. The law also increases the earned income credit from 10% to 14% for 2017 and then to 18% in 2018. The cap on the education expense credit will increase from $500 to $750 in 2017 and the teachers’ deduction (for federal purposes) of $250 will become a $250 credit for Illinois.


Many of these changes could greatly affect your income tax situation for 2017 and beyond. Please contact us if we can be of any assistance.


https://scheffelboyle.com/wp-content/uploads/2018/06/pexels-photo-209224.jpeg 426 640 jordan@bonniburns.com https://scheffelboyle.com/wp-content/uploads/2022/06/Transparent-Logo-5.png jordan@bonniburns.com2017-07-21 18:56:392018-07-31 10:36:02Illinois Income Tax Law Changes for 2017

Illinois Income Tax Law Changes for 2017

July 21, 2017

The Illinois House recently followed the Senate’s lead in overriding Governor Rauner’s veto of the Illinois budget. Senate Bill 9 raises around $5 billion of new permanent income taxes. The individual income tax rates increased from 3.75% to 4.95%, while the corporate rates rose from 5.25% to 7.0%. These rate increases were effective on July 1, 2017.


The difficulty with the midyear tax increase is that the law imposes the new tax rate effective July 1, 2017 so that net income is taxed at the 3.75% rate from January 1 through June 30, 2017.  Likewise an income tax rate of 4.95% is imposed on the income earned from July 1 through December 31, 2017.  Illinois taxpayers are provided two options to calculate income subject to different rates in the same tax year.  A taxpayer may divide its full year net income proportionally based on the number of months subject to the former rate and the new rate.  This would effectively result in a tax rate of 4.35% to be applied to the entire 2017 tax year for individuals.  Alternatively, a taxpayer may elect to specifically account for items of income and deduction based on when they were generated during the tax year.  See the following example for this election.


Example: A husband and wife file a joint Illinois income tax return for 2017. The husband earns $75,000 plus a $30,000 bonus received in January 2017. The wife earns a salary of $50,000 plus she sold a stock and received a capital gain of $10,000 in November 2017. To the best of our knowledge, the income tax calculations would be as follows:

1/1/17 – 6/30/17 7/1/17 – 12/31/17 TOTAL
Husband salary $37,500 $37,500 $75,000
Wife salary  25,000 25,000 50,000
Husband bonus received in January  30,000 —— 30,000
Wife capital gain in November —— 10,000 10,000
Total income $92,500 $72,500 $165,000
Tax rate  3.75% 4.95%
Tax $3,469 $3,589 $7,058


If the taxpayers did not make the election to specifically allocate income, the use of the blended rate of 4.35% would result in an Illinois income tax of $7,178 ($165,000 * 4.35%).  Therefore, the election results in savings to the taxpayers of $120 ($7,178 – $7,058).  Note that this illustration does not factor in other adjustments that may impact the calculation such as exemptions, adjustments, etc.


The corporate income tax calculation will work in the same manner. As you can see, additional work will be required on your part in breaking down your income as to whether it was received prior to July 1 or after July 1.


For those of you with businesses who have employees, obviously the Illinois withholding on wages paid after June 30, 2017 will be required to be withheld at the 4.95% rate.


Other changes included in the new law include the elimination of personal exemptions, education expense credit and the real estate tax credit for single filers with income of $250,000 per year and for joint filers with income of $500,000 per year starting in 2017. The law also increases the earned income credit from 10% to 14% for 2017 and then to 18% in 2018. The cap on the education expense credit will increase from $500 to $750 in 2017 and the teachers’ deduction (for federal purposes) of $250 will become a $250 credit for Illinois.


Many of these changes could greatly affect your income tax situation for 2017 and beyond. Please contact us if we can be of any assistance.

https://scheffelboyle.com/wp-content/uploads/2018/06/pexels-photo-1028726.jpeg 426 640 jordan@bonniburns.com https://scheffelboyle.com/wp-content/uploads/2022/06/Transparent-Logo-5.png jordan@bonniburns.com2017-07-21 18:51:572018-07-31 10:36:10Illinois Income Tax Law Changes for 2017

Tax News July 2017

July 7, 2017

WHY YOU SHOULD (OR SHOULDN’T) PURSUE AN ACQUISITION

Like so many aspects of the national and global economies, merger and acquisition (M&A) activity tends to wax and wane. Nonetheless, billions of dollars continue to change hands annually, and an acquisition can be a great way to grow a business. So if one of these deals comes your way, it’s important to carefully consider both the pros and cons.

Look at the possibilities

Merging with, or acquiring, another company is one of the best ways to grow rapidly. You might be able to significantly boost revenue, literally overnight, by acquiring another business. Achieving a comparable rate of growth organically — by increasing sales of existing products and services or adding new product and service lines — can take years.

An acquisition also might enable your company to expand into new geographic areas and new customer segments more quickly and easily. You can do this via a horizontal acquisition (acquiring another company that’s similar to yours) or a vertical acquisition (acquiring another company along your supply chain).

In addition, you can realize synergies by acquiring the right type of company. Synergies are business characteristics and capabilities that complement and work well with those of your own company. The idea is to find an acquisition target that offers the right synergies so that the new combined entity will be stronger than either business would have been on its own.

Be aware of drawbacks

Although there are many potential benefits to acquiring another business, there are some potential drawbacks as well. For example, completing an acquisition is a costly process, from both a financial and a time-commitment perspective.

Therefore, you should determine how much the transaction will cost and how it will be financed before beginning the M&A process. Also try to get an idea of how much time you and your key managers will have to spend on M&A-related tasks in the coming months — and how this could impact your existing operations.

A loss of control is another potential drawback to consider. Depending on the deal’s structure, some degree of control may have to be shared with the owners of the business you’re acquiring, especially if the owners aren’t retiring but intend to be actively involved with the merged entity.

It’s also critical to try to ensure that the cultures of the two merging businesses will be compatible. Mismatched corporate cultures have been the main cause of numerous failed mergers, including some high-profile megamergers. For instance, if one company has a more formal and buttoned-down culture while the other is more casual and laid back, conflicts will likely ensue unless you plan carefully for how the two divergent cultures will be blended together.

Perform due diligence

The best way to reduce the risk involved in buying another business is to perform solid due diligence on your acquisition target. Your objective should be to confirm claims made by the seller about the company regarding its financial condition, clients, contracts, employees and management team.

The most important step in M&A due diligence is a careful examination of the company’s financial statements — specifically, the income statement, cash flow statement and balance sheet. Also scrutinize the existing client base and client contracts (if any exist) because projected future earnings and cash flow will largely hinge on these.

Finally, try to get a good feel for the knowledge, skills and experience possessed by the company’s employees and key managers. In some circumstances, you might consider offering key executives ownership shares if they’ll commit to staying with the company for a certain length of time after the merger.

Map your course

An acquisition is one way to expand and grow your company. But be sure to map your course thoroughly before heading down the M&A road. Our firm can help steer you in the right direction.

LEASING PROPERTY TO YOUR BUSINESS MIGHT TRIGGER UNDESIRABLE TAX CONSEQUENCES

If you own property and a business, there’s an obvious temptation to lease that property to the business. Such an arrangement can make sense from many perspectives.

You’re no doubt familiar with the property and its advantages to your company; the deal could be carried out quickly; and the money changing hands would stay between you and your company. And if you participate in other loss-producing passive activities, you may be hoping to offset the net rental income with those losses.

There’s just one big problem: You’d risk triggering the “self-rental rule” and not achieving your desired tax outcome.

Self-rental rule in a nutshell

Internal Revenue Code (IRC) Section 469 generally prohibits taxpayers from deducting passive activity losses (PALs).

It typically applies to “flow-through” income and losses from partnerships, limited liability companies (if they’ve elected to be treated as a partnership for tax purposes), S corporations and trusts.

The rules define “passive activity” as any trade or business in which the taxpayer doesn’t materially participate. Rental real estate activities generally are considered passive activities regardless of whether the taxpayer materially participates. (There’s an exception if the taxpayer qualifies as a real estate professional.)

A PAL is the amount by which the taxpayer’s aggregate losses from all passive activities for the year exceed the aggregate income from all of those activities. A PAL can usually be used only to offset passive income, though there are a few exceptions.

The self-rental rule in IRC Sec. 469 applies when you rent property to a business in which you or your spouse materially participates. Under the rule, any net rental losses are still considered passive, but the net rental income is deemed nonpassive. That means your net rental income can’t be offset by other passive losses, yet net rental losses generally can offset only other passive income. This could have negative tax consequences if you’re hoping to offset your self-rental net income with passive losses from other activities.

The power of grouping

You may be able to avoid the negative tax consequences of IRC Sec. 469’s self-rental rule by “grouping.” The regulations allow you to group your separately owned rental building with your business to treat them as one activity for purposes of the passive loss rules if they constitute an “appropriate economic unit.”

The regulations determine this based on factors such as common ownership and control, types of activities and location. As long as you materially participate in the business — and the business isn’t a C corporation — the rental activity won’t be treated as passive for the purposes of income or losses.

To take advantage of this option, you must own both the rental property and the business. You could also use grouping if the rental activity is “insubstantial” (a term undefined by the regulations) in relation to the business activity.

Finding the best arrangement

Renting property to a business in which you materially participate can seem like a great idea. But doing so can turn out to be a lose-lose proposition when it comes to taxes — particularly for S corporation owners who may not understand the rules. Please contact our firm for help devising the most beneficial arrangement for your situation.

WHICH TYPE OF MORTGAGE LOAN MEETS YOUR NEEDS?

Few purchases during your lifetime will be as expensive as buying a home. Whether it’s your primary residence, a vacation home or an investment property, how you choose to pay for it can have a significant impact on your financial situation over time. If you’re considering a mortgage loan, understanding the main categories of mortgages — fixed-rate and adjustable-rate — and the situations they’re best designed for will help you match the right type for your needs.

Fixed-rate loans offer stability

A fixed-rate mortgage, as its name suggests, is a loan whose interest rate remains constant for the life of the loan — typically 15 or 30 years. One of the primary benefits of a fixed-rate loan is that it provides a measure of certainty about one of the biggest expenses in your monthly budget. With interest rates likely to rise after an extended period of historically low rates, you won’t have to worry about potentially higher payments in the future if you select a fixed-rate loan.

That said, if interest rates were to fall again, your fixed-rate loan would leave you unable to take advantage of the shift unless you refinance, which might involve fees. You’re also paying a premium for the stability offered by a fixed-rate mortgage. You could consider a 15-year fixed-rate loan, which would charge a lower rate than a 30-year loan, but the tradeoff will be higher monthly payments.

ARMs provide flexibility

Adjustable-rate mortgages (ARMs) typically offer a fixed interest rate for an initial period of years. This rate, which is usually lower than that of a comparable fixed-rate mortgage, resets periodically based on a benchmark interest rate. For example, a 5/1 ARM means that your interest rate is fixed for the first five years and then will adjust every year after that.

Paying less interest in the beginning frees your cash for other investments. You might also take advantage of an ARM if you’re confident that you’ll have more money in the future than you do today, or if you plan on selling your house before or soon after the initial fixed-rate period expires. When considering an ARM, you’ll need to assess your ability to keep up with potentially higher payments — say, if the initial period expires, your rate goes up and you’re unable to sell the home, or if your income changes.

The best for you

The right loan type depends, naturally, on your financial position. But whether you’re buying a primary residence, vacation home or investment property also plays a role. Regardless of which type of home you’re purchasing, having a basic knowledge of the loan types can help ease the buying process. Let our firm assist you in evaluating the best mortgage for your needs.

KNOW YOUR TAX HAND WHEN IT COMES TO GAMBLING

A royal flush can be quite a rush. But the IRS casts a wide net when defining gambling income. It includes winnings from casinos, horse races, lotteries and raffles, as well as any cash or prizes (appraised at fair market value) from contests. If you participate in any of these activities, you must report such winnings as income on your federal return.

If you’re a casual gambler, report your winnings as “Other income” on Form 1040. You may also take an itemized deduction for gambling losses, but the deduction is limited to the amount of winnings.

In some cases, casinos and other payers provide IRS Form W-2G, “Certain Gambling Winnings” — particularly if the entity in question withholds federal income tax from winnings. The information from these forms needs to be included on your tax return.

If you gamble often and actively, you might qualify as a professional gambler, which comes with tax benefits: It allows you to deduct not only losses, but also wagering-related business expenses — such as transportation, meals and entertainment, tournament and casino admissions, and applicable website and magazine subscriptions.

To qualify as a professional, you must be able to demonstrate to the IRS that a “profit motive” exists. The agency looks at a list of nonexclusive factors when making this determination, including:

  • Whether the taxpayer conducts the gambling activity in a “businesslike” manner,
  • The quantity of time spent gambling, and
  • How much income is earned from nongambling activities.

But don’t “go pro” for the tax benefits, since doing so is a major financial risk. If you enjoy the occasional game of chance, or particularly if you’re considering gambling as a profession, please contact our firm. We can help you manage the tax impact.

TAX CALENDAR

July 17 — If the monthly deposit rule applies, employers must deposit the tax for payments in June for Social Security, Medicare, withheld income tax and nonpayroll withholding.

July 31 — If you have employees, a federal unemployment tax (FUTA) deposit is due if the FUTA liability through June exceeds $500.

  • The second quarter Form 941 (“Employer’s Quarterly Federal Tax Return”) is also due today. (If your tax liability is less than $2,500, you can pay it in full with a timely filed return.) If you deposited the tax for the quarter in full and on time, you have until August 10 to file the return.

August 15 — If the monthly deposit rule applies, employers must deposit the tax for payments in July for Social Security, Medicare, withheld income tax and nonpayroll withholding.

September 15 — Third quarter estimated tax payments are due for individuals, trusts and calendar-year corporations.

  • If a six-month extension was obtained, partnerships should file their 2016 Form 1065 by this date.
  • If a six-month extension was obtained, calendar-year S corporations should file their 2016 Form 1120S by this date.
  • If the monthly deposit rule applies, employers must deposit the tax for payments in August for Social Security, Medicare, withheld income tax, and nonpayroll withholding.


Important Information: The information contained in this newsletter was not intended or written to be used and cannot be used for the purpose of (1) avoiding tax-related penalties prescribed by the Internal Revenue Code or (2) promoting or marketing any tax-related matter addressed herein.

The Tax and Business Alert is designed to provide accurate information regarding the subject matter covered. However, before completing any significant transactions based on the information contained herein, please contact us for advice on how the information applies in your specific situation. Tax and Business Alert is a trademark used herein under license. © Copyright 2017.
https://scheffelboyle.com/wp-content/uploads/2018/06/money-finance-bills-bank-notes.jpg 486 640 jordan@bonniburns.com https://scheffelboyle.com/wp-content/uploads/2022/06/Transparent-Logo-5.png jordan@bonniburns.com2017-07-07 18:54:412018-07-31 10:36:15Tax News July 2017

Tax News June 2017

June 5, 2017

IN DOWN YEARS, NOL RULES CAN OFFER TAX RELIEF

From time to time, a business may find that its operating expenses and other deductions for a particular year exceed its income. This is known as incurring a net operating loss (NOL).

In such cases, companies (or their owners) may be able to snatch some tax relief from this revenue defeat. Under the Internal Revenue Code, a corporation or individual may deduct an NOL from its income.

3 ways to play

Generally, you take an NOL deduction in one of three ways:

  1. Deducting the loss in previous years, called a “carryback,” which creates a refund,
  2. Deducting the loss in future years, called a “carryforward,” which lowers your future tax liability, or
  3. Doing a little bit of both.

A corporation or individual must carry back an NOL to the two years before the year it incurred the loss. But the carryback period may be increased to three years if a casualty or theft causes the NOL, or if you have a qualified small business and the loss is in a presidentially declared disaster area. The carryforward period is a maximum of 20 years.

Direction of travel

You must first carry back losses to the earliest tax year for which you qualify, depending on which carryback period applies. This can produce an immediate refund of taxes paid in the carryback years. From there, you may carry forward any remaining losses year by year up to the 20-year maximum.

You may, however, elect to forgo the carryback period and instead immediately carry forward a loss if you believe doing so will provide a greater tax benefit. But you’ll need to compare your marginal tax rate — that is, the tax rate of the last income dollar in the previous two years — with your expected marginal tax rates in future years.

For example, say your marginal tax rate was relatively low over the last two years, but you expect big profits next year. In this case, your increased income might put you in a higher marginal tax bracket. So you’d be smarter to waive the carryback period and carry forward the NOL to years in which you can use it to reduce income that otherwise would be taxed at the higher rate.

Then again, as of this writing, efforts are underway to pass tax law reform. So, if tax rates go down, it might be more beneficial to carry back an NOL as far as allowed before carrying it forward.

Whatever the reason

Many circumstances can create an NOL. Whatever the reason, the rules are complex. Let us help you work through the process.

Sidebar: AMT effect

One tricky aspect of navigating the net operating loss (NOL) rules is the impact of the alternative minimum tax (AMT). Many business owners wonder whether they can offset AMT liability with NOLs just as they can offset regular tax liability.

The answer is “yes” — you can deduct your AMT NOLs from your AMT income in generally the same manner as for regular NOLs. The excess of deductions allowed over the income recognized for AMT purposes is essentially the AMT NOL. But beware that different rules for deductions, exclusions and preferences apply to the AMT. (These rules apply to both individuals and corporations.)

ASKING THE RIGHT QUESTIONS ABOUT LONG-TERM CARE INSURANCE

Like most people, as you age into your 40s and 50s, you may wonder what the future holds for your health and well-being. Will you be as sharp mentally and robust physically as you are right now? Could a serious medical condition arise in your future that might prevent you from performing routine daily tasks?

Unfortunately, many of us require long-term care (LTC) at some point in our lives. To hedge against this considerable financial risk, insurers offer LTC coverage.

Do you really need it?

LTC insurance policies help pay for the cost of long-term nursing care or assistance with activities of daily living (ADLs), such as eating or bathing. Many policies cover care provided in the home, an assisted living facility or a nursing home, though some restrict coverage to only licensed facilities. Without this coverage, you’d likely need to pay these bills out of pocket.

Medicare or health insurance generally covers such expenses only if they’re temporary — that is, during a period over which you’re continuing to improve, such as recovering from surgery or a stroke. Once you’ve plateaued and are unlikely to improve further, health insurance or Medicare coverage typically ends.

That’s when LTC insurance may take over. But you need to balance the value of LTC insurance benefits with the cost of premiums, which can run several thousand dollars annually (though a portion may be tax deductible). Depending on your income and net worth, as well as your personal and family health history, LTC insurance may not be a worthwhile investment.

Should you buy now or later?

The younger you are when you buy a policy, the lower the premiums typically will be. And, the chance of being declined for a policy increases with age. Certain health conditions, such as Parkinson’s disease, can also make it more difficult, or impossible, for you to obtain an LTC policy. If you can still get coverage, it likely will be much more expensive.

So buying earlier in life may make sense. But, keep in mind you’ll potentially be paying premiums over a much longer period. You can often trim premium costs by choosing a longer elimination period or a shorter benefit period.

The elimination period is the amount of time between the start of the benefit trigger and the time that the policy begins paying benefits. This can range from 30 days to several months. Premium costs decrease as the elimination period increases.

Meanwhile, the benefit period is the period of time over which the policy pays for care. This can range from a year or two to an unlimited amount of time.

Boon or bust

Buying LTC insurance can be a boon or a bust. You should consider contacting our firm before making the purchase. We can help you determine whether LTC insurance is right for your situation and, if so, when to buy and the appropriate amount of coverage.

RENTING OUT YOUR VACATION HOME? ANTICIPATE THE TAX IMPACT

When buying a vacation home, the primary objective is usually to provide a place for many years of happy memories. But you might also view the property as an income-producing investment and choose to rent it out when you’re not using it. Let’s take a look at how the IRS generally treats income and expenses associated with a vacation home.

Mostly personal use

You can generally deduct interest up to $1 million in combined acquisition debt on your main residence and a second residence, such as a vacation home. In addition, you can also deduct property taxes on any number of residences.

If you (or your immediate family) use the home for more than 14 days and rent it out for less than 15 days during the year, the IRS will consider the property a “pure” personal residence, and you don’t have to report the rental income. But any expenses associated with the rental — such as advertising or cleaning — aren’t deductible.

More rental use

If you rent out the home for more than 14 days and you (or your immediate family) occupy the home for more than 14 days or 10% of the days you rent the property — whichever is greater — the IRS will still classify the home as a personal residence (in other words, vacation home), but you will have to report the rental income.

In this situation, you can deduct the personal portion of mortgage interest, property taxes and casualty losses as itemized deductions. In addition, the rental portion of your expenses is deductible up to the amount of rental income. If your rental expenses are greater than your rental income, you may not deduct the loss against other income.

If you (or your immediate family) use the vacation home for 14 days or less, or under 10% of the days you rent out the property, whichever is greater, the IRS will classify the home as a rental property. In this instance, while the personal portion of mortgage interest isn’t deductible, you may report as an itemized deduction the personal portion of property taxes. You must report the rental income and may deduct all rental expenses, including depreciation, subject to the passive activity loss rules.

Brief examination

This has been just a brief examination of some of the tax issues related to a vacation home. Please contact our firm for a comprehensive assessment of your situation.


THOUGHTS AND MUSINGS ON FAMILY BUDGETING


Simplicity is the key to a successful family budget. But every budget needs to cover all necessary items. To find the right balance, your budget should address two distinct facets of your family members’ lives: the near term and the long term.

In the near term, your budget should encompass the primary, day-to-day items that affect every family. First, housing: This is often the biggest expense in a family budget. And a budget shouldn’t include only mortgage or rent payments, but also expenses such as utilities, furnishings, maintenance and supplies.

Naturally, there are other items related to daily life for which you need to account. These include groceries, vehicle and transportation expenses, clothing, child care, insurance and out-of-pocket medical expenses. And you need to draw clear distinctions between fixed and discretionary spending.

Along with being a practical guide to family spending, a budget needs to address long-term goals. Naturally, some goals are further out than others. One of your longest-term objectives is probably to retire comfortably. So the budget should incorporate retirement plan contributions and other ways to meet this goal.

A relatively less long-term goal might be funding your children’s education. So, again, the budget should reflect this. And, as a long-term but “as soon as possible” objective, the budget needs to be structured to pay off debt and maintain a strong credit rating.

Only through careful planning and discussion can families build a budget that addresses both daily finances and long-term financial goals. We can help you get started.


Important Information: The information contained in this newsletter was not intended or written to be used and cannot be used for the purpose of (1) avoiding tax-related penalties prescribed by the Internal Revenue Code or (2) promoting or marketing any tax-related matter addressed herein.

The Tax and Business Alert is designed to provide accurate information regarding the subject matter covered. However, before completing any significant transactions based on the information contained herein, please contact us for advice on how the information applies in your specific situation. Tax and Business Alert is a trademark used herein under license. © Copyright 2017.
https://scheffelboyle.com/wp-content/uploads/2018/06/accountant-accounting-adviser-advisor-159804.jpeg 426 640 jordan@bonniburns.com https://scheffelboyle.com/wp-content/uploads/2022/06/Transparent-Logo-5.png jordan@bonniburns.com2017-06-05 18:58:262018-07-31 10:36:19Tax News June 2017

Employees Raise Over $5,400 for Big Brothers Big Sisters

May 3, 2017

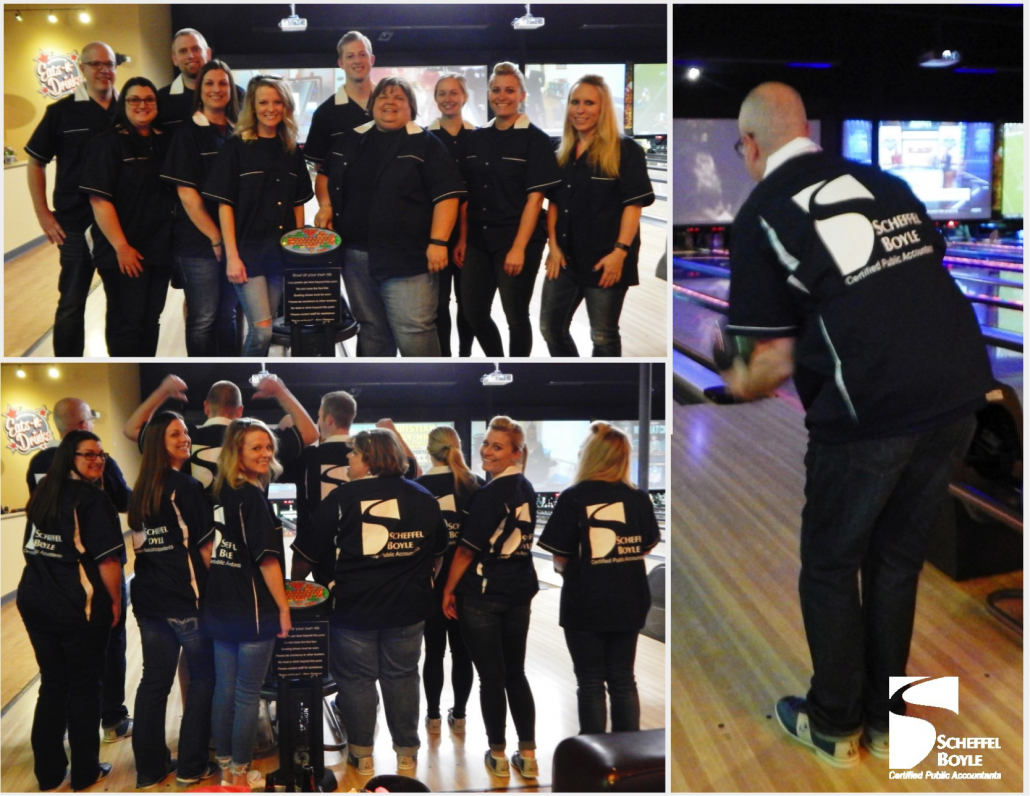
Our employees have once again teamed up to raise funds for Big Brothers Big Sisters (BBBS) of Southwestern Illinois at the annual Bowl for Kids’ Sake fundraiser. This year our teams raised over $5,400 for the agency through their efforts, which will all be donated directly to BBBS of Southwestern Illinois.

Scheffel Boyle’s two bowling teams, the Tax Manian Devils and the Ten-Key Strikers, participated in the event on April 25th at Edison’s Entertainment Complex in Edwardsville. Our ten bowlers are responsible for doing their own fundraising for the event, and it’s a friendly competition among the coworkers as to who can raise the most money for BBBS. This year, one of our teams ranked 1st for the entire Southwestern Illinois region for total funds raised, and Scheffel Boyle placed 2nd overall in fundraising.

Big shout-out to our bowlers Elizabeth Heil, Carrie Evans, Jenna Andres, Josh Andres, Michael Brokering, Sarah Smith, Jennison Ebbert, Crystal Schulte, Chad Frerichs, and Crystal Bock. Thank you for all you do for this amazing organization!

BBBS has been changing lives of youth throughout the U.S. for more than 100 years. Their vision “that all children achieve success in life”, is supported through donations and fundraising events, such as Bowl for Kids’ Sake. For information on how you can donate or participate in a BBBS of Southwestern Illinois event, visit www.bbbsil.org.


https://scheffelboyle.com/wp-content/uploads/2018/06/bb-bs.png 1288 1667 jordan@bonniburns.com https://scheffelboyle.com/wp-content/uploads/2022/06/Transparent-Logo-5.png jordan@bonniburns.com2017-05-03 19:01:492018-07-31 10:36:31Employees Raise Over $5,400 for Big Brothers Big Sisters
Page 27 of 32«‹2526272829›»

Pages

  • 2025 Seminar Registration
  • 2025 Seminar Registration Presentation Slides
  • 2026 Summer Sneak Peek
  • About Us
  • Accounting and Office Manager
  • Accounting Clerk
  • Accounting Services
  • Administrative Assistant
  • Administrative Assistant – Columbia Office
  • Administrative Assistant – Edwardsville Office
  • Administrative Support Specialist
  • Administrative Support Specialist
  • AGCI Webinar Presentation
  • Agribusiness
  • Alton, IL
  • Andrea Suhre
  • Andrea Suhre
  • Audit & Assurance
  • Available Opportunities
  • BDO Alliance USA
  • Belleville, IL
  • Bookkeeper
  • Bookkeeper/Payroll Specialist
  • Brian Otten
  • Business Valuations
  • Careers
  • Carrollton, IL
  • Columbia, IL
  • Construction Accounting
  • Construction Newsletter
  • Construction Tax Seminar Presentation
  • Consulting Services
  • Contact Us
  • Coronavirus Resource Center
  • Cory E. Gallivan
  • Crystal Bock
  • Crystal Bock
  • Dale Holtmann
  • Daniel Phipps
  • Data Entry Assistants
  • Dennis E. Ulrich
  • E-News Sign Up
  • Edwardsville, IL
  • Elements
  • Employee Benefit Plans
  • Experienced Accountants
  • Experienced Public Accountant
  • Financial Calculators
  • Financial Institution
  • FOCUS Internship Program
  • Full-Time Interview Sign-Up
  • George Moore
  • Governmental Entities
  • Heather Clugston
  • Helpful Links
  • Highland, IL
  • Home
  • Howard Held
  • Individual Clients
  • Industries
  • Interview Thank You
  • Interview Timeslots
  • Jerseyville, IL
  • Julie Billeter
  • Julie Graham
  • Kathy Fitzgerald
  • Keith Brinkmann
  • Knowledge Center
  • Lisa Bohnenstiehl
  • Locations
  • Mark Korte
  • Marketing Specialist
  • Michael D. Ulrich
  • Michael E. Fitzgerald
  • Michael T. Brokering
  • Non-Profit Organizations
  • Office Accounting Assistant
  • Our Team
  • Outsourced Accountant
  • Part-Time Bookkeeper
  • Payroll Assistant
  • Payroll Supervisor
  • Peer Review
  • Privacy Policy
  • Privately-Held Businesses
  • Professional Affiliations
  • Recruiting Events
  • Recruiting/Human Resources Coordinator
  • Resources
  • Robyn M. Klingler
  • Russell Gregson
  • Sarah Smith
  • Scheffel Boyle News
  • Scheffel Boyle Shares
  • Scott Weber
  • Seasonal Tax Preparer
  • Services
  • SIBA Webinar Presentation
  • Sneak Peek Survey
  • Spring Tax Internship Program 2026
  • STL Ag Club Webinar Prez
  • Summer Audit Internship Program
  • Summer Audit Internship Program 2026
  • Tax Planning & Preparation
  • Tax Talks Information
  • Tax Talks Presentation
  • Testimonials
  • Webinar Presentation May 14
  • Welcome Email
  • Year-End Tax Planning Seminars
  • Accountant – Carrollton
  • Administrative Assistant – Alton Office
  • Administrative Assistant – Belleville Office
  • Administrative Assistant – Columbia Office
  • Seasonal Administrative Assistants
  • Seasonal Data Input
  • Staff Accountant

Categories

  • Blog
  • Construction
  • Coronavirus Resource Center
  • Frontpage
  • Knowledge Center
  • Scheffel News
  • Uncategorized

Archive

  • August 2026
  • May 2026
  • November 2025
  • October 2025
  • July 2025
  • February 2024
  • July 2023
  • May 2023
  • February 2023
  • January 2023
  • November 2022
  • August 2022
  • July 2022
  • June 2022
  • March 2022
  • February 2022
  • January 2022
  • December 2021
  • June 2021
  • May 2021
  • April 2021
  • March 2021
  • February 2021
  • January 2021
  • December 2020
  • November 2020
  • October 2020
  • September 2020
  • August 2020
  • July 2020
  • June 2020
  • May 2020
  • April 2020
  • March 2020
  • February 2020
  • January 2020
  • December 2019
  • November 2019
  • October 2019
  • September 2019
  • August 2019
  • July 2019
  • June 2019
  • May 2019
  • April 2019
  • March 2019
  • February 2019
  • January 2019
  • December 2018
  • November 2018
  • October 2018
  • September 2018
  • August 2018
  • July 2018
  • June 2018
  • May 2018
  • April 2018
  • March 2018
  • February 2018
  • January 2018
  • December 2017
  • November 2017
  • October 2017
  • September 2017
  • August 2017
  • July 2017
  • June 2017
  • May 2017
  • April 2017
  • March 2017
  • February 2017
  • January 2017
  • December 2016
  • October 2016
  • September 2016
  • August 2016
  • July 2016
  • May 2016
  • April 2016
  • March 2016
  • February 2016
  • January 2016
  • December 2015
  • November 2015
  • August 2015
  • July 2015
  • June 2015
  • February 2015
  • January 2015
  • December 2014
  • November 2014
  • September 2014
  • August 2014
  • March 2014
  • February 2014
  • December 2013
  • November 2013
  • October 2013
  • August 2013
  • July 2013
  • June 2013
  • May 2013
  • February 2013
  • January 2013

About Us


Serving St. Louis, the Metro-East and Southwestern Illinois since 1924.

Knowledge Center

  • New Rules Could Increase Taxable Income for GamblersAugust 24, 2026 - 3:20 pm
  • IRS Notice CP53E and the Rise of Refund-Related ScamsMay 18, 2026 - 9:55 am
  • Potential Refund Deadline Extensions Under the Kwong CaseMay 7, 2026 - 11:40 am

Quick Links

  • Services
  • Clients & Industries
  • Our Team
  • Scheffel Boyle News
  • Careers

 Contact Us

Alton, IL: 618.465.4288
Edwardsville, IL: 618.656.1206
Belleville, IL: 618.277.8100
Highland, IL: 618.654.9895
Jerseyville, IL: 618.498.6841
Columbia, IL: 618.281.7605
Carrollton, IL: 217.942.3821

© Copyright 2021 Scheffel Boyle — All rights reserved
  • Site Map
  • Privacy Policy
Scroll to top Scroll to top Scroll to top