Loading
Scheffel Boyle
  • Home
  • About Us
    • Our Team
    • Our Values
    • Scheffel Boyle News
    • Professional Affiliations
    • Client Testimonials
    • Peer Review
    • Scheffel Boyle Shares
    • BDO Alliance USA
  • Services
    • Tax Planning & Preparation
    • Audit & Assurance
    • Accounting Services
    • Consulting Services
    • Financial Advisory
  • Clients & Industries
    • Construction
    • Financial Institutions
    • Agribusiness
    • Governmental Entities
    • Non-Profit Organizations
    • Privately-Held Businesses
    • Individual Clients
    • Employee Benefit Plans
  • Resources
    • Knowledge Center
    • Coronavirus Resource Center
    • Helpful Links
  • Careers
    • Benefits
    • Available Opportunities
    • College Students
  • Contact Us
    • Locations
      • Alton, IL
      • Belleville, IL
      • Carrollton, IL
      • Columbia, IL
      • Edwardsville, IL
      • Highland, IL
      • Jerseyville, IL
  • Click to open the search input field Click to open the search input field Search
  • Menu Menu
  • Link to Facebook
  • Link to LinkedIn

SBA Will Start Accepting PPP Forgiveness Applications From Lenders on August 10, 2020

July 30, 2020

The Small Business Administration (SBA) has set a date of August 10th for lenders to begin submitting forgiveness applications for Paycheck Protection Program (PPP) loans. On July 23rd, the SBA issued a procedural notice (linked here) to lenders outlining the process of applying for forgiveness for their borrowers. The SBA has created a forgiveness platform for lenders use only for the process.

A borrower may submit a Loan Forgiveness Application before the end of the 8-week or 24-week Covered Period, provided that the borrower has used all of the loan proceeds for which the borrower is requesting forgiveness and the borrower’s loan forgiveness application accounts for any salary reductions in excess of 25% for the full covered period.

In the notice, the SBA once again stressed that “providing an accurate calculation of the loan forgiveness amount is the responsibility of the borrower, and Lenders may rely on borrower representations. Lenders are expected to perform a good-faith review, in a reasonable time, of the borrower’s calculations and supporting documents concerning amounts eligible for forgiveness.” It went on to say that the Lender must review the application and submit its decision on forgiveness, with supporting documents, to the SBA no later than 60 days after its receipt from the borrower. Furthermore, the SBA will have the opportunity to review all PPP loans at any time, if needed.


PPP loan recipients applying for forgiveness should expect the following:

  • Borrower is to submit SBA Form 3508 or 3508EZ (or Lender’s equivalent Loan Forgiveness Application) to the lender servicing their loan
  • Lender is to confirm receipt of the application and required supporting documentation (payroll and nonpayroll costs)
  • Lender is to confirm the borrower’s calculations on Form 3508 or 3508EZ (or Lender’s equivalent Loan Forgiveness Application)
  • Lender is to review eligible expenses and supporting documentation provided by the borrower
  • If the lender finds errors in the borrower’s calculations or does not feel the documentation provided is substantial for forgiveness, the Lender is expected to work with the borrower to resolve the outstanding issues.


The lender must indicate their decision as:

  • Approval in Full
  • Approval in Part
  • Denied
  • Denied without Prejudice


What should borrowers do to prepare? Talk to your lenders!

Regardless of the Covered Period a borrower chooses, it is critical to begin conversations about loan forgiveness procedures with lenders as soon as possible, particularly since lenders will be making the initial review before it goes to the Small Business Administration (SBA) for final approval.

Borrowers should get clarity from their lender on the forgiveness process, including:

  • Will applications be accepted on the SBA’s paper forms or will an online submission be required?
  • Is the lender requiring borrowers to submit documentation via email, an online portal, or in some other way?
  • What formats are acceptable when submitting supporting documentation?


How We Can Help

Our team is able to assist you during the process of applying for PPP loan forgiveness. We anticipate there may be modifications to the terms of the Paycheck Protection Program in the coming weeks and our team is closely monitoring the situation.  We will update you as any such changes or new laws are released.  Please contact your trusted Scheffel Boyle team member with questions. We are always here to help.

https://scheffelboyle.com/wp-content/uploads/2020/07/SBA-Accept-Apps-IMAGE.png 788 940 brett@bonniburns.com https://scheffelboyle.com/wp-content/uploads/2022/06/Transparent-Logo-5.png brett@bonniburns.com2020-07-30 08:58:562020-07-30 09:53:35SBA Will Start Accepting PPP Forgiveness Applications From Lenders on August 10, 2020

Watch Out for Illinois Department of Employment Security Scams

July 28, 2020

A warning has been issued to Illinois residents regarding unemployment fraud and identity theft in response to several complaints to the Illinois Department of Employment Security (IDES). Illinois Attorney General Kwame Raoul recently issued an alert stating that if you received an IDES debit card but did not apply for unemployment, you may be a victim of the scam.

The debit card is usually accompanied by a letter approving you for unemployment benefits. If you receive this but never applied for benefits through IDES, you should contact the IDES at 1-800-814-0513, visit the IDES website to report it online, or reach out to the Attorney General’s Identity Theft Hotline at 1-866-999-5630.

It is important that you do not activate the card.

Please contact our team with questions. We are always here to help.

https://scheffelboyle.com/wp-content/uploads/2020/07/IDES-Scam-IMAGE.png 788 940 brett@bonniburns.com https://scheffelboyle.com/wp-content/uploads/2022/06/Transparent-Logo-5.png brett@bonniburns.com2020-07-28 15:32:402020-07-28 16:00:16Watch Out for Illinois Department of Employment Security Scams

IRS Updates FAQs on CARES Act Employee Retention Credits and Payroll Tax Deferrals

July 17, 2020

The IRS recently updated its frequently asked questions (FAQs) on the Employee Retention Credit (ERC) and payroll tax deferrals under the Coronavirus Aid, Relief, and Economic Security (CARES) Act (P.L. 116-136). These provisions encourage businesses to keep employees on their payroll during the COVID-19 global pandemic. Although the FAQs cannot be relied upon as legal authority, they indicate the IRS’s thinking.


Borrowers With Forgiven PPP Loans Can Defer Payroll Tax Deposits

Section 2302 of the CARES Act provides that, through December 31, 2020, employers may defer the deposit and payment of the employer’s portion of Social Security taxes and certain railroad retirement taxes. Half of the deferred amount is due on December 31, 2021, and the other half is due on December 31, 2022.

On June 26, the IRS updated FAQ #4 on CARES Act payroll tax deferrals, confirming that an employer who has a Paycheck Protection Program (PPP) loan forgiven under the CARES Act is entitled to defer payment and deposit of the employer’s share of Social Security tax. The update to FAQ #4 follows the enactment of the Paycheck Protection Program Flexibility Act (P.L. 116-142), which eliminated the CARES Act provision that had prevented an employer from deferring the deposit and payment of its share of Social Security taxes after its PPP loan was forgiven.


Insights:

An employer that receives a PPP loan can defer payment and deposit of the employer’s share of Social Security tax not only while the PPP loan is outstanding, but also after the loan is forgiven.

The CARES Act payroll tax deferral provision essentially gives employers a two-year, interest-free loan from the federal government of approximately 6.2% of an employer’s payroll (up to $137,700 per employee, which is the 2020 Social Security wage base cap). Employers are not required to apply for or take any other steps to qualify for this “loan.” This payroll tax deposit loan is available regardless of whether the employer applied for a PPP loan or Main Street Lending Program loan.


Employee Retention Credit Updates

On June 26, the IRS updated several ERC FAQs. The ERC is a refundable tax credit equal to 50% of up to $10,000 in wages paid by an eligible employer whose business has been financially impacted by COVID-19. Each payroll period, employers may subtract the ERC from the employer’s portion of payroll tax deposits and retain (rather than remit) that amount. But if the employer does not have sufficient payroll taxes to fund the ERC, the employer can apply for a rapid refund of the ERC using IRS Form 7200.


Insights:

Although the credit is determined quarterly, only $10,000 of wages per employee can be counted for all calendar quarters (i.e., the credit is currently capped at $5,000 per employee).

Several proposals are pending in Congress that would expand the amount, scope and duration of the ERC. Further action on those proposals is expected between July 20 and early August.

We understand that the IRS generally sends employers a paper check within 13 days after processing the Form 7200. But due to the number of refund requests being processed by the IRS, it may take approximately 30 days from the date the Form 7200 was submitted to receive the refund check. The IRS has set up a special unit to solely handle processing these advance refund requests.

Below is a summary of the changes made by the updated ERC FAQs:

  • FAQ #28 – Clarifies that a local health department order mandating a workplace closure for cleaning would qualify as “an order from an appropriate governmental authority” when determining if an employer qualifies for the ERC. FAQ #28 also now acknowledges that whether an employer’s business is “essential” may vary from jurisdiction to jurisdiction.
  • FAQ #30 – Clarifies that the ERC would be available to an employer who operates both an essential and non-essential business and experiences a partial suspension of more than a nominal part of their non-essential operations due to a governmental shut-down order. FAQ #30 also says that an essential business may be eligible for the ERC if it has a partial suspension due to a governmental order that requires the employer to close for a period of time during normal working hours.
  • FAQ #33 – Adds two new examples of ERC eligibility when an employer’s workplace is closed by a governmental order, but the employer can continue partial operations through teleworking. One of the new examples involves a physical therapy practice (which is partially shut down due to inability to access essential equipment), and the other involves scientific researchers (the workplace is shut down for those who do lab work, but not shut down for those who can work from home).
  • FAQ #34 – Provides six examples of ERC eligibility for partial suspensions of operations where an employer’s workplace is closed by a governmental order for certain purposes but may remain open for other purposes or where the employer is able to continue certain operations remotely or with accommodations that do not significantly disrupt the employer’s business. FAQ #34 now includes examples of ERC eligibility for workplaces subject to social distancing guidelines, such as restaurants, retail stores (which are considered partially suspended if their physical location is closed, but they continue to do business on line), grocery stores and hospitals (which are considered to have a partial suspension of operations due to a governmental order that prevents them from performing elective and non-urgent medical procedures). But FAQ #34 states that if the impact of the governmental restriction on the employer’s business is only nominal, then the ERC would not be available. This is a facts-and-circumstances test. For example, FAQ #34 says that a grocery store’s operations would not be partially suspended because a governmental order requires closure of its salad bar and other self-serve offerings, since that change does not have more than a nominal effect on the grocery store’s business operations. Similarly, a large retailer would not have a partial suspension merely because customers must wait a short time to enter the store due to compliance with social distancing guidelines.
  • FAQ #35 – Clarifies that an employer would be eligible for the ERC by reducing its work hours to comply with a governmental order requiring sanitation at certain intervals to reduce the risk of COVID-19. A new example concludes that a food processing plant would be eligible for the ERC if it normally operates 24 hours a day but has to close for five hours a day to conduct mandated deep cleaning.
  • FAQ #46 – Establishes (for the first time) a “gross receipts” test for tax-exempt organizations to qualify for the ERC. The new test includes gross receipts from all operations, including all sales and amounts received for services, investment income, contributions, gifts, grants and membership fees or dues. To determine if a tax-exempt organization has had a significant decline in gross receipts for any quarter in 2020, it must compare the quarterly gross receipts from the 2020 calendar year to the same calendar quarter in 2019.
  • FAQ #58 – Adds three new examples clarifying that employers cannot claim the ERC for amounts that are not “wages” for Federal Insurance Contributions Act (FICA) tax withholding purposes (even though employers can claim the ERC for qualified health plan expenses allocable to such wages). FAQ #58 now includes examples showing that an employer matching contribution to a 401(k) plan and employee pre-tax contributions toward dependent care assistance and qualified transportation fringe benefit cannot be the basis for ERCs.
  • FAQ #79 – Confirms that employers who received PPP loans but repaid them by May 18 (under a special safe harbor rule) are eligible for the ERC.
  • FAQ #88 – Confirms that payroll reporting agents may sign and submit Form 7200 to the IRS on behalf of a client.
  • FAQ #90 – Clarifies that an employer and its third-party payer will each be liable for employment taxes that are due as a result of any improper ERC claim filed by the third-party payer.
  • FAQ #92 – Clarifies that employers (not third-party payers) are responsible for avoiding a “double benefit” with respect to the ERC and the paid family medical leave tax credit under Internal Revenue Code Section 45S.
https://scheffelboyle.com/wp-content/uploads/2020/07/IRS-FAQ-7_17-Blog-IMAGE.png 788 940 brett@bonniburns.com https://scheffelboyle.com/wp-content/uploads/2022/06/Transparent-Logo-5.png brett@bonniburns.com2020-07-17 14:22:072020-07-17 14:22:07IRS Updates FAQs on CARES Act Employee Retention Credits and Payroll Tax Deferrals

PPP Loan Application Deadline Extended 5 Weeks

July 7, 2020

With roughly $129 billion in PPP loans still available, an extension has been passed to allow businesses an additional 5 weeks to apply for the funds. The Senate and House both unanimously approved the extension just before the original deadline of June 30th and President Trump officially signed it into law on the July 4th holiday. Businesses who experienced difficulty due to the COVID-19 pandemic will now have until August 8th to apply for a PPP Loan.

The forgivable loans were first introduced in April by the U.S. Small Business Administration (SBA) in partnership with the U.S. Treasury to provide aid to businesses affected by the Coronavirus. A message on the SBA website states they have “resumed accepting applications July 6, 2020, at 9:00 AM EDT in response to the Paycheck Protection Program Extension Act”.

For more information on PPP loans and how to apply, click here.

Please contact your trusted Scheffel Boyle team member with questions. We are always here to help.

https://scheffelboyle.com/wp-content/uploads/2020/07/PPP-App-Extension-IMAGE.png 788 940 brett@bonniburns.com https://scheffelboyle.com/wp-content/uploads/2022/06/Transparent-Logo-5.png brett@bonniburns.com2020-07-07 07:55:302020-07-07 07:56:18PPP Loan Application Deadline Extended 5 Weeks

Keep Your Stimulus Payment Notice for Your 2020 Taxes

June 24, 2020

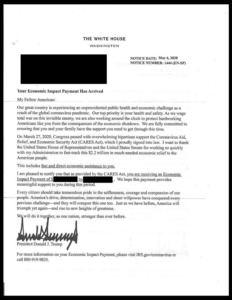
In mid-April, Economic Impact Payments, also known as Stimulus Payments, began hitting bank accounts of taxpayers across the U.S. If you were an eligible recipient of a stimulus check and received your payment, you should have also received Notice 1444 following the disbursement of your payment.

Notice 1444 detailed the amount of the payment, how the payment was made (where it was deposited or mailed), and how to report a payment that was not received by its intended recipient. The Notice was mailed to the last known mailing address of the taxpayer within 15 days of the payment being released. It may be important to keep Notice 1444 with all other records for 2020 tax filings when claiming additional tax credits. We have included an image below of Notice 1444 for your reference.

If you have any questions regarding your stimulus payment, please contact our team.


Notice 1444

https://scheffelboyle.com/wp-content/uploads/2020/06/Notice-1444-IMAGE-3.png 788 940 brett@bonniburns.com https://scheffelboyle.com/wp-content/uploads/2022/06/Transparent-Logo-5.png brett@bonniburns.com2020-06-24 07:30:232020-06-24 07:45:44Keep Your Stimulus Payment Notice for Your 2020 Taxes

Scheffel Boyle Ranks 11th on St. Louis’ Largest Accounting Firms List

June 23, 2020

Scheffel Boyle has ranked #11 for number of professionals on the St. Louis Business Journal’s annual Largest Accounting Firms list. The Journal publishes two lists for ranking CPA firms each year: one based on number of CPAs and the other on number of professionals. With 46 CPAs, we are ranked as the 12th largest by number of CPAs.

Thank you to our clients, employees, and community partners for all they’ve done to help us grow and continue serving the St. Louis and Metro regions.


https://scheffelboyle.com/wp-content/uploads/2020/06/Biz-Journal-List-2020-image.png 788 940 brett@bonniburns.com https://scheffelboyle.com/wp-content/uploads/2022/06/Transparent-Logo-5.png brett@bonniburns.com2020-06-23 09:24:092020-06-23 09:36:14Scheffel Boyle Ranks 11th on St. Louis’ Largest Accounting Firms List

PPP Loan Forgiveness Application Updated for the Flexibility Act

June 18, 2020

On June 16th, the SBA and Treasury released the revised PPP Loan Forgiveness Application. The new application is just five pages long, is said to be “borrower-friendly”, and reflects the changes implemented by the Paycheck Protection Program Flexibility Act of 2020.

The revised PPP Loan Forgiveness Application and instructions contain a number of updates, including:

  • Loan recipients whose funds were disbursed prior to June 5 can now have an option for a new 24-week Covered Period or keep their original 8-week Covered Period. Loans disbursed after June 5 will only have the new 24-week Covered Period.
  • Safe harbors for salary and hourly wage reductions and reductions in Full-Time Equivalents (FTE) are extended to the date the forgiveness application is submitted or December 31, rather than the original deadline of June 30, unless the 8-week Covered Period is selected.
  • Retirement costs for S Corporation owners are eligible for forgiveness, but health insurance costs for S Corporation owners cannot be included in the payroll calculation.

In addition to the revised application, the SBA also introduced the EZ PPP Loan Forgiveness Application, which requires fewer calculations and less documentation for eligible borrowers. The EZ application applies to loan recipients who meet any one of these criteria:

  • are self-employed with no employees,
  • did not reduce the salaries or hourly wages of their employees by more than 25% during the Covered Period compared to 1/1/20 and 3/31/20 and did not reduce the number of employees or the average hours paid between 1/1/20 and the end of the Covered Period,
  • did not reduce the salaries or hourly wages of their employees by more than 25% during the Covered Period compared to 1/1/20 and 3/31/20 and experienced reduced business activity due to COVID-19.

Instructions clarify that employee compensation is limited to 24/52 of $100,000 during the 24-week Covered Period (8/52 of $100,000 if the 8-week Covered Period is used). This means that up to $46,152 can qualify as forgivable employee compensation during the 24-week Covered Period.

For owner-employees, self-employed individuals and general partners using the 24-week Covered Period, compensation is limited to the 2.5-month equivalent of 2019 compensation, capped at $100,000.  In this case, such an individual will have a maximum forgivable compensation of $20,833 ($100,000 divided by 12 times 2.5).  It may be less if the individual had 2019 compensation below $100,000.  If the 8-week Covered Period is selected, the formula is 8/52 of 2019 compensation, capped at $100,000.


Additional Items

A few of the other major changes to forgiveness requirements from the Paycheck Protection Program Flexibility Act of 2020 include:

  • Lowers the portion of PPP loan funds that must be used for payroll from 75% to 60%, allowing 40% to be used toward other non-payroll, eligible costs such as rent and utilities.
  • Extends the loan term of any funds not forgiven to 5 years from 2 years. Please note that for existing loans prior to the passing of this bill, both lender and borrower must agree to the change in loan terms through a refinance of the loan. The interest rate remains 1%.
  • Allows businesses who qualify for loan forgiveness to also defer the employer portion of payroll tax, which would be paid in two installments (50% by 12-31-2021 and 50% by 12/31/2022)
  • Changes the loan repayment deferral period to the date forgiveness is decided rather than 6 months from disbursement

The SBA and the Treasury Department are hopeful that the revised application and new EZ application will make the forgiveness process more efficient for borrowers, while making it easier for businesses to be eligible for full forgiveness of their loans.

Our team is closely monitoring this situation as updates are released. Please reach out to your trusted Scheffel Boyle team member with questions. We are always here to help.

https://scheffelboyle.com/wp-content/uploads/2020/06/PPP-App-Updated-6-16-1-image.png 788 940 brett@bonniburns.com https://scheffelboyle.com/wp-content/uploads/2022/06/Transparent-Logo-5.png brett@bonniburns.com2020-06-18 13:27:252020-06-18 15:28:29PPP Loan Forgiveness Application Updated for the Flexibility Act

Main Street Lending Program Expansion

June 16, 2020

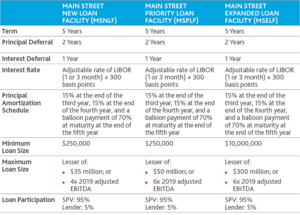
On June 8, the Federal Reserve released revised term sheets for its Main Street Lending Program (MSLP), ahead of the program becoming officially operationalized. The MSLP aims to increase the flow of credit to small and medium-sized businesses that were in good financial standing prior to the COVID-19 crisis.

Over the past few weeks, the Federal Reserve held several teleconference sessions to explain the MSLP and to seek feedback on previously released program details from lenders and borrowers. With input from these sessions and other sources, the Federal Reserve has further adjusted the financial terms and conditions of the various lending facilities to attract and meet the needs of a broader range of borrowers and lenders.

Notable changes to the MSLP include the following:

  • Lowering the minimum loan amount for certain facilities from $500,000 to $250,000;
  • Increasing the maximum loan size for all facilities;
  • Increasing the loan terms from four to five years;
  • Extending the repayment period for all loans by delaying principal payments for two years, rather than one; and
  • Raising the Federal Reserve’s participation to 95% for all loans.


Key Eligibility Criteria and Loan Details

Detailed descriptions of all changes and modifications to each MSLP program are available via term sheets by the Federal Reserve:

  • Main Street New Loan Facility
  • Main Street Priority Loan Facility
  • Main Street Expanded Loan Facility

How to Apply for a Main Street Loan

A Main Street loan application can be requested at a federally insured lending institution, which will apply its own underwriting criteria. In addition, the Federal Reserve also released several application forms and agreements that must be completed in conjunction with the primary loan application. The documents include borrower certifications and covenants.

The Federal Reserve cautions that “eligible borrowers should contact an eligible lender for more information on whether the eligible lender plans to participate in the program and to request more information on the application process.” The Federal Reserve expects the MSLP to open for lender registration soon, after which participating banks will begin offering loans.

Please refer to the Federal Reserve’s Main Street website for the latest program information.

If you have questions over this program, please contact our team. We are always here to help.

https://scheffelboyle.com/wp-content/uploads/2020/06/MSLP-Blog-Image.png 788 940 brett@bonniburns.com https://scheffelboyle.com/wp-content/uploads/2022/06/Transparent-Logo-5.png brett@bonniburns.com2020-06-16 14:53:002020-06-16 14:54:42Main Street Lending Program Expansion

COVID-19 FAQs for Financial Institutions

June 10, 2020

The COVID-19 pandemic has caused widespread disruption to business operations across all industries. In the face of unprecedented uncertainty, financial institutions have a pivotal role in the urgent response to the crisis. There are also specific measures to take that can mitigate the impact of the crisis on financial institutions themselves.

Here are answers to some of the most frequently asked questions for financial institutions and specialty finance organizations, along with relevant resources to help businesses in their response to the pandemic and in planning for the future.


How does this impact CECL adoption?

The effects of COVID-19 could complicate how banks and other financial institutions comply with the current expected credit loss (CECL) accounting standard, given the impact on forecasting credit losses and underlying economic fundamentals, as well as partial relief offered under the CARES Act. For example, unemployment, which has risen significantly, is a driver of credit risk. Management should consider impacting factors just like any other significant estimate, which must be based on reasonable and supportable estimates and not on speculative information.

As a result of the financial reporting uncertainty, the CARES Act allows banks and other financial institutions to suspend applying CECL rules until December 31, 2020, or whenever the deferral is lifted, whichever comes first. The SEC also issued a public statement that applying the provisions of the CARES Act is in accordance with GAAP.


What is the impact to our supply chain?

As an “essential business,” banks and other financial institutions are mandated to stay open, even with a limited worker presence. However, the COVID-19 outbreak has disrupted supply chains due to the forced closure of nonessential businesses and related workforce shortages. For banks and other financial institutions, this has caused a sharp increase in delays for supplies from vendors (including sanitizer, disinfectant and gloves that may be required to continue retail branch operations safely), and it has impacted the array of service providers that support banking operations. Some of these necessary vendors and service providers may also be in danger of financial default themselves due to business interruption and revenue losses.

Banks and other financial institutions should also bear in mind that when business survival is on the line, organizations tend to be less transparent and more focused on finding workarounds, which can result in an uptick of fraudulent activity that impacts the entire supply chain system. In the longer term, it’s prudent to consider diversifying the supply chain where possible, which can help expand options during future periods of scarcity. While product cost is typically a determining factor in choosing a vendor or service provider, availability and stability take on greater importance when the usual supply chain has been disrupted. By optimizing current inventory and developing a more dynamic sourcing footprint, financial institutions can mitigate some key aspects of disruption to supply chains.


Should we be thinking about re-tooling our business strategy to capture new business opportunities?

Financial institutions have seen significant disruption as employees work from home, and even “late-adopter” customers have turned to mobile apps and online channels to conduct routine financial transactions. The COVID-19 pandemic has forced banks and other financial institutions to innovate in a very short period of time, and as a result, the ‘new normal’ may look very different to pre-crisis operations. The development or acquisition of proprietary fintech applications to support customer conversion and servicing will likely accelerate at an even faster rate.

The industry also stands to benefit financially as an administrator of loans under the Paycheck Protection Program (PPP), a forgivable loan program included in the CARES Act, which significantly expands the types of organizations that are eligible for Small Business Administration (SBA) loans. To manage a backlog of applications, banks and other financial institutions are competing with other fintech entities to process these and additional small business loans.

It’s clear that banks and other financial institutions have a lot to consider when it comes to new business opportunities in the long term. They will need to think creatively about value-add to appeal to customers, especially as the fintech industry continues to gain market share at their expense in managing consumers’ financial transactions.


How can I prevent data loss while employees are working from home?

Many banks and other financial institutions have rapidly shifted their employees from an office-based work environment to a remote one. As a result, organizations have been forced to urgently review their security practices. When IT professionals set up a business’ network, they implement numerous controls that are designed to prevent data leakage and loss. However, many popular platforms that enable remote work do not align easily with these controls. For example, while corporate controls might enforce a policy that prohibits the remote sharing of desktop files and USB connections, remote working tools may allow such actions. Moreover, employees who use their own devices for work instead of company-issued devices could unwittingly introduce malware to the network. This endangers the security of all network data, with particular concern regarding proprietary and sensitive information, especially related to revenues, costs, cash flow and new business opportunities.

Increasing the number of entry points to a network raises serious issues for data protection and increases the possibility of data loss. Security teams have also observed an increase in phishing attempts that could expose a network to ransomware. For this reason, employees should receive additional training for cybersecurity while working remotely. Not only could a company lose important data and be unable to retrieve it, but that data could also be shared improperly outside the organization or breached by a malicious third party, thereby exposing the business to potential violations of data privacy laws.

To mitigate data security and privacy risks, financial institutions and specialty finance organizations should use cloud computing for all files and require employees to connect using a cloud VPN. This provides secure access to the organization’s network and shared files, and it encrypts all data. Two-factor authentication further strengthens these controls. Companies should also consider implementing specific data loss prevention (DLP) solutions, which give the network administrator control over the data that employees handle, and they should enforce policies around what data can be transferred and who can receive transfers. Advanced detection tools may also be deployed to prevent improper remote access. These technologies use machine learning to identify and respond to suspicious activities. Overall, network access for remote workers should be protected by numerous robust controls and barriers and actively monitored for any issues in real time.


How do I keep my workplace safe?

Banks and other financial institutions are deemed “essential businesses,” meaning that branches are allowed to remain open during the COVID-19 pandemic. To minimize the risk of the virus’ transmission, they have been encouraging customers to use drive-through facilities to conduct routine business transactions, and to make appointments to avoid crowds gathering in common branch areas such as lobbies.

Banks and other financial institutions should also refer to federal, state and local government requirements to inform social distancing and remote working protocols at branches. For example, San Francisco mandates that workers must work from home if they can do so, and only be ‘on-site’ if they are unable to perform their job functions from home.

Furthermore, social distancing best practices include maintaining at least six feet between people, regularly disinfecting high-touch areas and having a stock of hand sanitizer available to promote personal hygiene. Various shelter-in-place orders throughout some states also help to reduce foot traffic as citizens are required to stay indoors unless they have a justifiable reason or extenuating circumstances. For reference, a list of banks’ COVID-19 response plans can be found on the American Bankers Association website.


What does IT need to do to prepare for remote working? What remote working issues should I anticipate?

Even as an “essential business” at the branch level, banks and other financial institutions have been forced to rapidly shift operations so that all non-essential employees work remotely, from HQ office workers to branch employees that can perform job functions independent of the facility. As a result, their IT departments are crucial to maintaining business continuity in the wake of these unexpected disruptions. IT should ensure that employees have the training to use collaboration, communication and conferencing technology—whether this is Microsoft Teams, Slack, Skype, Cisco Webex or another option.

For security, staff also need training on how to identify suspicious activity, such as phishing emails, and promptly report such activity to the IT department. This is especially critical for banks and other financial institutions that conduct transactions of a highly sensitive nature on a regular basis.

Cloud computing is another vital tool that facilitates remote working by providing secure access to the organization’s network and shared files. Decision support systems in the cloud can also help employees be more productive. Using a cloud VPN can ensure that data is encrypted when employees access the cloud, and two-factor authentication strengthens that security. Employees should also be required to use company-issued devices for work purposes whenever possible, because personal devices may have unknown vulnerabilities or more lax privacy settings.

However, the widespread deployment of collaboration tools and cloud computing also increases demands on core network infrastructure. So, it’s important to ensure the network architecture can support these demands and that IT has the necessary resources. The expansion of virtual teams also introduces more potential points of failure between end users and the network, and it creates more user support needs as well. Management can assist the IT department with employee training resources and change management initiatives to encourage the ongoing success of remote teams.


What tax strategies should I consider changing in light of the current environment?

In the short term, banks and other financial institutions should consider leveraging any tax strategies that can help offset costs and increase cash flow. These include provisions in the various stimulus bills like payroll tax credits and delays in payment due dates for both income and payroll taxes, AMT credits, net operating loss carrybacks and tax-deductible charitable contributions.

Outside of the existing stimulus bills and other response measures, financial institutions and specialty finance organizations should also consider measures to reduce their total tax liability that were already available prior to the start of the pandemic, such as state and federal Research and Development (R&D) tax credits that can offset the costs associated with, for example, developing fintech applications to service customers. Companies that operate internationally should also assess the tax relief options being offered in the countries in which they operate.

While there are many tax savings opportunities available, eligibility for some provisions is dependent on company size and other factors, and many benefits are mutually exclusive or have other tax implications that could affect an organization’s total tax liability. Given the level of complexity in tax planning during this time, it is critical that banks and other financial institutions consult with tax professionals in order to maximize their savings and understand the long-term impacts of their tax strategies.


How is COVID-19 impacting deal flow?

Most management teams and investors are hitting the pause button on deal activity. The economic realities are changing fast, and so too are deal threats and opportunities. For banks and other financial institutions, COVID-19 has introduced significant risk and led to fewer lenders willing to facilitate deals. Furthermore, some borrowers are struggling to repay loans due to their own deteriorating financial situation, impacting the bottom line for potential deal targets. Valuations have also dipped as the market downturn has affected EBITDA and financial projections for sellers.

Parties in M&A deals—buyers, sellers and lenders—are currently assessing the situation and will be making decisions to proceed, adjust or discontinue deal processes based on critical factors including crisis management, performance outlook, valuation changes and COVID-19’s lasting impact on the economy. Deal activity in certain in-demand sectors—such as technology, healthcare, and those facilitating essential services like distribution logistics—are likely to rebound sooner than other industries. Ultimately, and hopefully sooner rather than later, the path forward will become clearer and many sellers will resume sale processes. However, some will have to modify their approach or even take longer pauses as the uncertain outlook persists.


How can we help?

Our team is closely monitoring updates regarding the programs and relief efforts surround the COVID-19 pandemic. Please contact our Financial Institutions Group with questions. We are always here to help.
https://scheffelboyle.com/wp-content/uploads/2020/06/FAQ-FIG-BLOG-IMAGE.png 788 940 brett@bonniburns.com https://scheffelboyle.com/wp-content/uploads/2022/06/Transparent-Logo-5.png brett@bonniburns.com2020-06-10 08:13:502020-06-10 11:10:39COVID-19 FAQs for Financial Institutions

President Trump Signs Bill Offering Flexibility on PPP Loan Forgiveness Into Law

June 5, 2020

Today, June 5th, President Trump signed the Paycheck Protection Program Flexibility Act of 2020 into law. The bill eases the strict guidelines currently in place to qualify for forgiveness of PPP loan funds and allows for an additional 16 weeks to use the funds for eligible expenses. It also provides more flexibility for use of the funds on “non-payroll” expenses. For more details on the changes the bill provides, please see our earlier blog regarding the bill by clicking here.

The SBA Forgiveness Application will have to be updated to incorporate the new forgiveness guidelines. We will continue to monitor the updates to the application and send out information as it becomes available.

Please contact your trusted Scheffel Boyle team member with questions. We are always here to help.
https://scheffelboyle.com/wp-content/uploads/2020/06/TRUMP-SIGNS-BILL-IMAGE.png 788 940 brett@bonniburns.com https://scheffelboyle.com/wp-content/uploads/2022/06/Transparent-Logo-5.png brett@bonniburns.com2020-06-05 14:51:282020-06-05 14:53:29President Trump Signs Bill Offering Flexibility on PPP Loan Forgiveness Into Law
Page 7 of 31«‹56789›»

Pages

  • 2025 Seminar Registration
  • 2025 Seminar Registration Presentation Slides
  • 2026 Summer Sneak Peek
  • About Us
  • Accounting and Office Manager
  • Accounting Clerk
  • Accounting Services
  • Administrative Assistant
  • Administrative Assistant – Columbia Office
  • Administrative Assistant – Edwardsville Office
  • Administrative Support Specialist
  • Administrative Support Specialist
  • AGCI Webinar Presentation
  • Agribusiness
  • Alton, IL
  • Andrea Suhre
  • Andrea Suhre
  • Audit & Assurance
  • Available Opportunities
  • BDO Alliance USA
  • Belleville, IL
  • Bookkeeper
  • Bookkeeper/Payroll Specialist
  • Brian Otten
  • Business Valuations
  • Careers
  • Carrollton, IL
  • Columbia, IL
  • Construction Accounting
  • Construction Newsletter
  • Construction Tax Seminar Presentation
  • Consulting Services
  • Contact Us
  • Coronavirus Resource Center
  • Cory E. Gallivan
  • Crystal Bock
  • Crystal Bock
  • Dale Holtmann
  • Daniel Phipps
  • Data Entry Assistants
  • Dennis E. Ulrich
  • E-News Sign Up
  • Edwardsville, IL
  • Elements
  • Employee Benefit Plans
  • Experienced Accountants
  • Experienced Public Accountant
  • Financial Calculators
  • Financial Institution
  • FOCUS Internship Program
  • Full-Time Interview Sign-Up
  • George Moore
  • Governmental Entities
  • Heather Clugston
  • Helpful Links
  • Highland, IL
  • Home
  • Howard Held
  • Individual Clients
  • Industries
  • Interview Thank You
  • Interview Timeslots
  • Jerseyville, IL
  • Julie Billeter
  • Julie Graham
  • Kathy Fitzgerald
  • Keith Brinkmann
  • Knowledge Center
  • Lisa Bohnenstiehl
  • Locations
  • Mark Korte
  • Marketing Specialist
  • Michael D. Ulrich
  • Michael E. Fitzgerald
  • Michael T. Brokering
  • Non-Profit Organizations
  • Office Accounting Assistant
  • Our Team
  • Outsourced Accountant
  • Part-Time Bookkeeper
  • Payroll Assistant
  • Payroll Supervisor
  • Peer Review
  • Privacy Policy
  • Privately-Held Businesses
  • Professional Affiliations
  • Recruiting Events
  • Recruiting/Human Resources Coordinator
  • Resources
  • Robyn M. Klingler
  • Russell Gregson
  • Sarah Smith
  • Scheffel Boyle News
  • Scheffel Boyle Shares
  • Scott Weber
  • Seasonal Tax Preparer
  • Services
  • SIBA Webinar Presentation
  • Sneak Peek Survey
  • Spring Tax Internship Program 2026
  • STL Ag Club Webinar Prez
  • Summer Audit Internship Program
  • Summer Audit Internship Program 2026
  • Tax Planning & Preparation
  • Tax Talks Information
  • Tax Talks Presentation
  • Testimonials
  • Webinar Presentation May 14
  • Welcome Email
  • Year-End Tax Planning Seminars
  • Accountant – Carrollton
  • Administrative Assistant – Alton Office
  • Administrative Assistant – Belleville Office
  • Administrative Assistant – Columbia Office
  • Seasonal Administrative Assistants
  • Seasonal Data Input
  • Staff Accountant

Categories

  • Blog
  • Construction
  • Coronavirus Resource Center
  • Frontpage
  • Knowledge Center
  • Scheffel News
  • Uncategorized

Archive

  • August 2026
  • May 2026
  • November 2025
  • October 2025
  • July 2025
  • February 2024
  • July 2023
  • May 2023
  • February 2023
  • January 2023
  • November 2022
  • August 2022
  • July 2022
  • June 2022
  • March 2022
  • February 2022
  • January 2022
  • December 2021
  • June 2021
  • May 2021
  • April 2021
  • March 2021
  • February 2021
  • January 2021
  • December 2020
  • November 2020
  • October 2020
  • September 2020
  • August 2020
  • July 2020
  • June 2020
  • May 2020
  • April 2020
  • March 2020
  • February 2020
  • January 2020
  • December 2019
  • November 2019
  • October 2019
  • September 2019
  • August 2019
  • July 2019
  • June 2019
  • May 2019
  • April 2019
  • March 2019
  • February 2019
  • January 2019
  • December 2018
  • November 2018
  • October 2018
  • September 2018
  • August 2018
  • July 2018
  • June 2018
  • May 2018
  • April 2018
  • March 2018
  • February 2018
  • January 2018
  • December 2017
  • November 2017
  • October 2017
  • September 2017
  • August 2017
  • July 2017
  • June 2017
  • May 2017
  • April 2017
  • March 2017
  • February 2017
  • January 2017
  • December 2016
  • October 2016
  • September 2016
  • August 2016
  • July 2016
  • May 2016
  • April 2016
  • March 2016
  • February 2016
  • January 2016
  • December 2015
  • November 2015
  • August 2015
  • July 2015
  • June 2015
  • February 2015
  • January 2015
  • December 2014
  • November 2014
  • September 2014
  • August 2014
  • March 2014
  • February 2014
  • December 2013
  • November 2013
  • October 2013
  • August 2013
  • July 2013
  • June 2013
  • May 2013
  • February 2013
  • January 2013

About Us


Serving St. Louis, the Metro-East and Southwestern Illinois since 1924.

Knowledge Center

  • New Rules Could Increase Taxable Income for GamblersAugust 24, 2026 - 3:20 pm
  • IRS Notice CP53E and the Rise of Refund-Related ScamsMay 18, 2026 - 9:55 am
  • Potential Refund Deadline Extensions Under the Kwong CaseMay 7, 2026 - 11:40 am

Quick Links

  • Services
  • Clients & Industries
  • Our Team
  • Scheffel Boyle News
  • Careers

 Contact Us

Alton, IL: 618.465.4288
Edwardsville, IL: 618.656.1206
Belleville, IL: 618.277.8100
Highland, IL: 618.654.9895
Jerseyville, IL: 618.498.6841
Columbia, IL: 618.281.7605
Carrollton, IL: 217.942.3821

© Copyright 2021 Scheffel Boyle — All rights reserved
  • Site Map
  • Privacy Policy
Scroll to top Scroll to top Scroll to top