Loading
Scheffel Boyle
  • Home
  • About Us
    • Our Team
    • Our Values
    • Scheffel Boyle News
    • Professional Affiliations
    • Client Testimonials
    • Peer Review
    • Scheffel Boyle Shares
    • BDO Alliance USA
  • Services
    • Tax Planning & Preparation
    • Audit & Assurance
    • Accounting Services
    • Consulting Services
    • Financial Advisory
  • Clients & Industries
    • Construction
    • Financial Institutions
    • Agribusiness
    • Governmental Entities
    • Non-Profit Organizations
    • Privately-Held Businesses
    • Individual Clients
    • Employee Benefit Plans
  • Resources
    • Knowledge Center
    • Coronavirus Resource Center
    • Helpful Links
  • Careers
    • Benefits
    • Available Opportunities
    • College Students
  • Contact Us
    • Locations
      • Alton, IL
      • Belleville, IL
      • Carrollton, IL
      • Columbia, IL
      • Edwardsville, IL
      • Highland, IL
      • Jerseyville, IL
  • Click to open the search input field Click to open the search input field Search
  • Menu Menu
  • Link to Facebook
  • Link to LinkedIn
Digital graphic that illustrates financial fraud

Fraudulent Unemployment Claims on the Rise in Illinois

December 10, 2020

Government officials throughout Illinois are urging residents to be on the lookout for identity theft activity related to unemployment insurance.

In an alert published by Illinois Attorney General’s office, people who have not filed for unemployment insurance are receiving letters and debit cards, loaded with funds, in the mail despite not having applied for benefits. Unfortunately, Illinoisans receiving these unsolicited letters and debit cards had their personal and financial information compromised.

The Attorney General urges those who believe their personal or financial information has been compromised to take the following steps:

  • If you received a debit card in the mail that you did not request, do not activate it.
  • Notify state and local authorities.
    • Contact the Illinois Department of Employment Security (IDES) at 800.814.0513 to immediately to report a false claim.
    • Contact the Illinois Attorney General’s office to obtain information to take steps to guard against identity theft. You may also call the Identity Theft Hotline at 1.866.999.5630.
    • Contact your local police department or Sheriff to file a police report.
  • Obtain and monitor your credit report.
    • You can check your credit report free once per week through April 2021 by visiting annualcreditreport.com.
    • You may request a request a fraud alert by contacting one of the three major credit bureaus. Also, consider placing a freeze on your credit report to prevent further fraudulent activity.
  • Review all your financial accounts closely for accuracy and dispute any unauthorized charges or debits immediately with your financial institution.

Victims of this fraud are not responsible for repaying stolen unemployment benefits and will be eligible to file for unemployment benefits if they do become unemployed.

https://scheffelboyle.com/wp-content/uploads/2020/12/Fraud-graphic.jpg 743 1280 brett@bonniburns.com https://scheffelboyle.com/wp-content/uploads/2022/06/Transparent-Logo-5.png brett@bonniburns.com2020-12-10 11:10:012020-12-10 11:41:04Fraudulent Unemployment Claims on the Rise in Illinois

IRS Clarifies Timing on No Deductibility of Expenses Paid with PPP Funds

November 20, 2020

The IRS yesterday released Revenue Ruling 2020-27 to clarify the timing on the deductibility of expenses paid with PPP loan funds.

The ruling asks the question, “may a taxpayer that received a loan guaranteed under the Paycheck Protection Program (PPP), and paid or incurred certain otherwise deductible expenses listed in section 1106(b) of the Coronavirus Aid, Relief, and Economic Security Act deduct those expenses in the taxable year in which the expenses were paid or incurred if, at the end of such taxable year, the taxpayer reasonably expects to receive forgiveness of the covered loan based on the otherwise deductible expenses?”


BACKGROUND:

Back in May 2020, the IRS issued Notice 2020-32 that informed taxpayers that “no deduction is allowed for an eligible expense that is otherwise deductible if the payment of the eligible expense results in forgiveness of the covered loan.”  That meant that even though the forgiveness of the covered loan was exempt from income, the nondeductibility of the expenses has indirectly caused the loan to be taxable.  Over the last few months, Congress has proposed legislation that would make the expenses deductible, but nothing has been passed through congress to date.  In addition, as we are approaching the end of the year, taxpayers who haven’t applied for forgiveness have been left wondering the timing of the deduction of the expenses depending on if forgiveness is obtained in a subsequent year.  This brings us to Revenue Ruling 2020-27.


THE NEW REVENUE RULING OFFERS TWO SITUATIONS:

  • Situation 1: During the period beginning on February 15, 2020, and ending on December 31, 2020 (covered period), Taxpayer paid expenses that are described in section 161 of the Internal Revenue Code and section 1106(a) of the CARES Act (eligible expenses).  These expenses include payroll costs that qualify under section 1106(a)(8) of the CARES Act, interest on a mortgage that qualifies as interest on a covered mortgage obligation under section 1106(a)(2) of the CARES Act, utility payments that qualify as covered utility payment under section 1106(a)(5) of the Cares Act, and rent that qualifies as payment on a covered rent obligation under section 1106(a)(4) of the CARES Act.  In November 2020, taxpayer applied to the lender for forgiveness of the covered loan on the basis of the eligible expenses it paid during the covered period.  At that time, and based on taxpayer’s payment of the eligible expenses, taxpayer satisfied all requirements under section 1106 of the CARES Act for forgiveness of the covered loan.  The lender does no inform taxpayer whether the loan will be forgiven before the end of 2020.
  • Situation 2: During the covered period, Taxpayer paid the same types of eligible expenses that were paid in Situation 1.  Taxpayer did not apply for forgiveness of the covered loan before the end of 2020, although, taking into account the Taxpayer’s payment of the eligible expenses during the covered period, satisfied all other requirements under section 1106 of the CARES Act for forgiveness of the covered loan.  Taxpayer expects to apply to the lender for forgiveness of the covered loan in 2021.


ANALYSIS PROVIDED BY THE REVENUE RULING:

In both situations, the Taxpayer had a reasonable expectation of the reimbursement.  At the end of 2020, the reimbursement of the Taxpayers eligible expenses, in the form of covered loan forgiveness, is reasonably expected to occur rather than being unforeseeable, such that the deduction is inappropriate.  Taxpayer’s eligible expenses are not deducible because there is a reasonable expectation of reimbursement.

A Taxpayer that received a covered loan guaranteed under the PPP and paid or incurred certain otherwise deductible expenses may not deduct those eligible expenses in the taxable year in which the expenses were paid or incurred if, at the end of such taxable year, the taxpayer reasonably expects to receive forgiveness of the covered loan on the basis of the expenses it paid or accrued during the covered period, even if the taxpayer has not submitted an application for forgiveness of the covered loan by the end of such taxable year.

In summary, no matter when the application is filed or when it is approved for forgiveness, if reasonably expected to obtain forgiveness, the expenses will be nondeductible in 2020.

What was not provided in the Revenue Ruling was how to handle business owners with no employee payroll (for example, Schedule C filers with no employees).  These business owners don’t have the qualified expenses that qualifies them for forgiveness.


HOW CAN WE HELP

Our team is available to assist you during the process of applying for PPP loan forgiveness. We anticipate there may still be some modifications to the Paycheck Protection Program in the coming weeks and our team is closely monitoring the situation.  We will update you as any such changes or new laws are released.  Please contact your trusted Scheffel Boyle team member with questions. We are always here to help.
https://scheffelboyle.com/wp-content/uploads/2020/11/IRS.jpg 400 400 brett@bonniburns.com https://scheffelboyle.com/wp-content/uploads/2022/06/Transparent-Logo-5.png brett@bonniburns.com2020-11-20 15:38:482020-12-08 14:14:56IRS Clarifies Timing on No Deductibility of Expenses Paid with PPP Funds

SBA Simplifies PPP Forgiveness for Loans Under $50,000

October 9, 2020

On October 8th, the Treasury and U.S. Small Business Administration (SBA) released a new, scaled-down forgiveness application for borrowers with a PPP loan of $50,000 or less, other than any borrower that together with its affiliates received loans totaling $2 million or greater. The new interim final rule (linked here) pertaining to this streamlined process also provides new guidance for both forgiveness and loan review processes for PPP loans.

This new, simplified application (Form 3508S) has been much anticipated by both borrowers and lenders. Although the PPP loans which will qualify for this application account for only 9% of PPP dollars loaned, those loans total about two-thirds of all PPP loans issued.

With the new rules in place, PPP borrowers of $50,000 or less are now exempt from any decrease in forgiveness of the loan based on a reduction in full-time equivalent (FTE) employees and/or reductions in employee salary or wages. This eliminates the need for borrowers of $50,000 or less to calculate potentially complex FTE or salary reduction totals. While borrowers will still be required to make certifications and provide some documentation for their lender for payroll and nonpayroll costs, the process for both borrowers and lenders is now much simpler.

If you have questions regarding your PPP loan forgiveness application, please contact our team. We are always here to help.

Click here to download Form 3508S instructions.

https://scheffelboyle.com/wp-content/uploads/2020/10/SBA-50k-Forgiveness-Blog-IMAGE.png 788 940 brett@bonniburns.com https://scheffelboyle.com/wp-content/uploads/2022/06/Transparent-Logo-5.png brett@bonniburns.com2020-10-09 14:01:232020-10-09 14:31:37SBA Simplifies PPP Forgiveness for Loans Under $50,000

Announcing 2020 Promotions!

October 8, 2020

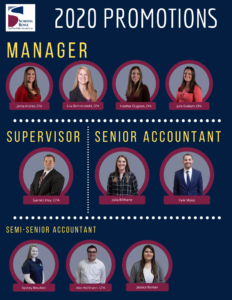
We are pleased to announce the recent promotion of 10 professionals throughout our seven offices. On behalf of our firm, we would like to wish all those who were promoted the best of luck in their new roles.

Manager: Jenna Andres, CPA; Lisa Bohnenstiehl, CPA; Heather Clugston, CPA; and Julie Graham, CPA

Supervisor: Garrett Hay, CPA

Senior Accountant: Julia Billhartz and Kyle Moist

Semi-Senior Accountant: Sydney Boschert; Alex Hoffmann, CPA; and Jessica Roman

https://scheffelboyle.com/wp-content/uploads/2020/10/PROMOTIONS-2020.png 2000 1545 brett@bonniburns.com https://scheffelboyle.com/wp-content/uploads/2022/06/Transparent-Logo-5.png brett@bonniburns.com2020-10-08 08:40:202020-10-09 07:37:56Announcing 2020 Promotions!

Lenders Are Not Required to Report PPP Loan Forgiveness to IRS

September 28, 2020

On Tuesday, September 22nd, the IRS released Announcement 2020-12, stating that lenders who make Paycheck Protection Program (PPP) loans are not required to file an information return or furnish a payee statement if all or a portion of the loan is later forgiven based on the borrower satisfying requirements of section 1106.

Under section 1106 of the CARES Act, a PPP loan may be forgiven if certain requirements are met by the borrower. The new announcement states that an institution is not required to “for federal income tax purposes only,” file Form 1099-C for funds that are forgiven. In addition, they are not to give the recipient a payee statement for forgiven amounts.

If you have questions regarding this update, please contact our Financial Institutions Group. We are always here to help.

https://scheffelboyle.com/wp-content/uploads/2020/09/FIG-Blog-9-28-IMAGE.png 788 940 brett@bonniburns.com https://scheffelboyle.com/wp-content/uploads/2022/06/Transparent-Logo-5.png brett@bonniburns.com2020-09-28 09:10:322020-09-28 09:10:32Lenders Are Not Required to Report PPP Loan Forgiveness to IRS

Proudly Introducing…

September 21, 2020

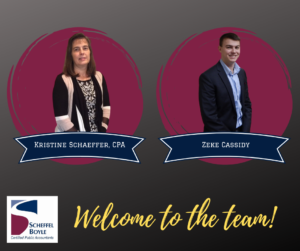
We are pleased to introduce our two newest employees to our amazing team, Kristine Schaeffer, CPA and Zeke Cassidy. Kristine has stepped into a Manager role in our Highland office after spending more than 30 years in public accounting, and Zeke completed our FOCUS Internship Program this past Spring and joins us as our newest Staff Accountant in Edwardsville. We are excited to have you both!

https://scheffelboyle.com/wp-content/uploads/2020/09/New-Hires-9-2020.png 788 940 brett@bonniburns.com https://scheffelboyle.com/wp-content/uploads/2022/06/Transparent-Logo-5.png brett@bonniburns.com2020-09-21 10:28:072020-09-21 10:29:11Proudly Introducing…

IRS to Stop Sending Past Due Notices Due to Backlog of Unopened Mail

August 24, 2020

The Internal Revenue Service is one of many agencies still feeling the effects of office closures due to COVID-19. Like many businesses, the IRS shut its doors this Spring due to the pandemic. As a result of the closure, a large backlog of unopened mail for the agency has accumulated. Even though many IRS employees have now returned to the office, more mail continues to arrive each day, making the backlog of correspondence difficult to dwindle down. At one time during the summer, it was estimated that approximately 12 million pieces of unopened mail sat in trailers outside IRS facilities.

Although the agency was struggling to process its incoming correspondence, balance due and late payment notices were still being sent to taxpayers, resulting in complaints and confusion from those who received notices but had already sent in payment. The IRS is urging taxpayers not to cancel their checks and allow them more time to process the payments, stating that any payment would be posted as the date received and not the date the agency began to process the payment. In short, as long as the check does not bounce and is not cancelled, interest and penalties will still be avoided if the payment was paid on time.

The IRS is dealing with higher than normal call volumes and longer wait times. All of these issues culminated in Representative Richard Neal (D-Massachusetts), chair of the House Ways and Means Committee, asking the IRS to stop mailing balance due notices to taxpayers. He also urged the agency to ensure penalties and interest would not be charged to those affected by the mail backlog.

On Friday, August 21st, the IRS responded by releasing this statement, announcing it would temporarily stop sending three balance due notices (CP-501, CP-503, and CP-504) while it sorts through the backlog of mail, which is estimated to still be in the millions. These are follow-up notices that are automatically mailed to taxpayers that did not respond to the first notice, CP-14. Although this policy change was announced late last week, the IRS warned that some previously scheduled notices may still hit mailboxes over the next few weeks.

The IRS has advised taxpayers to avoid calling their support lines at this time, as they are still experiencing high call volumes and long wait times. They suggested taxpayers visit the IRS website linked here for options to make payments other than by mail in the future. Payments may still be made by mail as well.

If you have questions regarding this information, please contact our team. We are always here to help.

https://scheffelboyle.com/wp-content/uploads/2020/08/IRS-Mailing-Notice-IMAGE.png 788 940 brett@bonniburns.com https://scheffelboyle.com/wp-content/uploads/2022/06/Transparent-Logo-5.png brett@bonniburns.com2020-08-24 10:09:572020-08-24 12:16:03IRS to Stop Sending Past Due Notices Due to Backlog of Unopened Mail

Madison County CARES Act Relief Provides Funds for Local Businesses

August 14, 2020

Madison County will open an application process on Monday, August 17,  2020 to grant $1.75 million in CARES Act relief funds to businesses and public service agencies located in the County that were impacted by COVID-19. Funds will be distributed through the Community Development Block Grant (CDBG) as a result of the CARES Act, with an allocation of $1.5 million for businesses and $250,000 for public service agencies. Grants will be awarded on a first come, first served basis for all submissions with complete and qualifying applications. Funds for accepted applicants are expected to be available in late October 2020.

This program provides a maximum $15,000, 0% deferred payment loan to help offset/recover from the significant, temporary loss of revenue to these qualified businesses during this pandemic, and to assist businesses in retaining and paying employees. The amounts disbursed will be broken down by the following Full-Time Equivalent (FTE) Employee counts:


FTE Employees Loan Amount
1-5 Maximum $5,000
6-10 Maximum $10,000
11-25 Maximum $15,000


Program Overview

  • $15,000 maximum (see above) for qualifying small businesses with a physical location in Madison County (1-25 full-time employees, or equivalent part-time employees, including the owner).
  • Food Service Establishments, short-term lodging, and other non-essential businesses impacted by the local or state safer-at-home orders are eligible.
  • Larger businesses over 25 FTE employees, non-profits, and home-based businesses are not eligible.
  • Funds can only be used to reimburse the cost of business interruption due to orders to close or limit operations, provided those costs are not paid by insurance or by another federal program. Such costs may include employee wages, vendors, rent, or other business expenses.


Eligible Businesses & Applications

Qualifying businesses include small businesses hardest hit by the COVID-19 pandemic, such as food service establishments, short-term lodging establishments, and non-essential businesses.

More detailed information on the funding, eligibility and application requirements of the program can be found on the Madison County website by clicking here. Applications can be submitted beginning August 17, 2020 and will be accepted through August 24, 2020 at 4:30 PM.

Alton and Granite City manage their own CDBG funding and will be responsible for taking applications within those communities. Please follow the link above for more details. We have included links below for the Application and Guidelines for applying.

Madison County CARES Act Economic Development Application Guidelines

Madison County Small Business Loan Application


How We Can Help

Our team is closely monitoring the relief programs available to local businesses and we are ready to provide assistance in applying for these funds. Please contact our team with questions on your eligibility or help with your application.

https://scheffelboyle.com/wp-content/uploads/2020/08/MADCO-RELIEF-IMAGE.png 788 940 brett@bonniburns.com https://scheffelboyle.com/wp-content/uploads/2022/06/Transparent-Logo-5.png brett@bonniburns.com2020-08-14 10:08:382020-08-14 10:37:58Madison County CARES Act Relief Provides Funds for Local Businesses

Trump Signs Executive Order Deferring Payroll Taxes

August 13, 2020

On August 8th, President Trump signed a total of four Executive Orders to provide further Coronavirus relief. The orders provided enhanced unemployment payments, student loan payment relief, eviction suspensions, and, most notably, a deferral of payroll taxes.

Payroll tax, or more frequently known as employment tax, is comprised of 6.2% Social Security tax and 1.45% Medicare tax. The order’s deferral will be applied toward the employee’s portion of Social Security tax withheld and for an employee’s pretax wages or compensation covering any biweekly pay period of less than $4,000. This deferral will be held without penalties, interest, or any additional tax imposed on the employer or employee.

While this does provide some assistance to taxpayers since Congress has come to a standstill on relief bill negotiations, a deferral is just a postponement of taxes owed. In short, the deferred taxes will still have to be paid if no further action is taken to eliminate them altogether. The deferral is for the withholding, deposit, and payment of these taxes from September 1, 2020 through December 31, 2020.

The Treasury is expected to issue guidance on implementation of the order as there are many outstanding questions surrounding it. The U.S. Chamber of Commerce and the AICPA are just two major organizations calling for further clarification on the order and its provisions for payroll tax deferral. Some of these issues include:

  • Eligibility to elect this deferral
  • Who is responsible for repayment of the deferred taxes
  • Payment deadlines for the taxes due
  • How payment will be collected
  • How fluctuating salaries and bonuses are accounted for with the order
  • Short-term and seasonal worker payroll
  • How to handle the deferred taxes when employees change jobs during the defined period

We are closely monitoring this situation as more guidance is released. Please contact your Scheffel Boyle team member with questions. We are always here to help.
https://scheffelboyle.com/wp-content/uploads/2020/08/Trump-Order-Payroll-Tax-IMAGE.png 788 940 brett@bonniburns.com https://scheffelboyle.com/wp-content/uploads/2022/06/Transparent-Logo-5.png brett@bonniburns.com2020-08-13 10:00:502020-08-14 10:15:44Trump Signs Executive Order Deferring Payroll Taxes

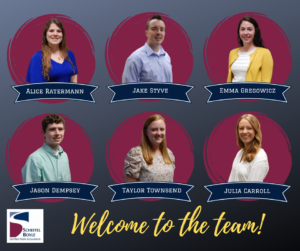
Welcome to the Team!

August 11, 2020

We are excited to announce that we have added six new staff accountants to our team. Our new employees include graduates of Saint Louis University, McKendree University, Lindenwood University, and Southern Illinois University Edwardsville. We are excited to have you all!


https://scheffelboyle.com/wp-content/uploads/2020/08/Welcome-to-the-team-2020.png 788 940 brett@bonniburns.com https://scheffelboyle.com/wp-content/uploads/2022/06/Transparent-Logo-5.png brett@bonniburns.com2020-08-11 15:17:562020-08-11 15:18:41Welcome to the Team!
Page 6 of 31«‹45678›»

Pages

  • 2025 Seminar Registration
  • 2025 Seminar Registration Presentation Slides
  • 2026 Summer Sneak Peek
  • About Us
  • Accounting and Office Manager
  • Accounting Clerk
  • Accounting Services
  • Administrative Assistant
  • Administrative Assistant – Columbia Office
  • Administrative Assistant – Edwardsville Office
  • Administrative Support Specialist
  • Administrative Support Specialist
  • AGCI Webinar Presentation
  • Agribusiness
  • Alton, IL
  • Andrea Suhre
  • Andrea Suhre
  • Audit & Assurance
  • Available Opportunities
  • BDO Alliance USA
  • Belleville, IL
  • Bookkeeper
  • Bookkeeper/Payroll Specialist
  • Brian Otten
  • Business Valuations
  • Careers
  • Carrollton, IL
  • Columbia, IL
  • Construction Accounting
  • Construction Newsletter
  • Construction Tax Seminar Presentation
  • Consulting Services
  • Contact Us
  • Coronavirus Resource Center
  • Cory E. Gallivan
  • Crystal Bock
  • Crystal Bock
  • Dale Holtmann
  • Daniel Phipps
  • Data Entry Assistants
  • Dennis E. Ulrich
  • E-News Sign Up
  • Edwardsville, IL
  • Elements
  • Employee Benefit Plans
  • Experienced Accountants
  • Experienced Public Accountant
  • Financial Calculators
  • Financial Institution
  • FOCUS Internship Program
  • Full-Time Interview Sign-Up
  • George Moore
  • Governmental Entities
  • Heather Clugston
  • Helpful Links
  • Highland, IL
  • Home
  • Howard Held
  • Individual Clients
  • Industries
  • Interview Thank You
  • Interview Timeslots
  • Jerseyville, IL
  • Julie Billeter
  • Julie Graham
  • Kathy Fitzgerald
  • Keith Brinkmann
  • Knowledge Center
  • Lisa Bohnenstiehl
  • Locations
  • Mark Korte
  • Marketing Specialist
  • Michael D. Ulrich
  • Michael E. Fitzgerald
  • Michael T. Brokering
  • Non-Profit Organizations
  • Office Accounting Assistant
  • Our Team
  • Outsourced Accountant
  • Part-Time Bookkeeper
  • Payroll Assistant
  • Payroll Supervisor
  • Peer Review
  • Privacy Policy
  • Privately-Held Businesses
  • Professional Affiliations
  • Recruiting Events
  • Recruiting/Human Resources Coordinator
  • Resources
  • Robyn M. Klingler
  • Russell Gregson
  • Sarah Smith
  • Scheffel Boyle News
  • Scheffel Boyle Shares
  • Scott Weber
  • Seasonal Tax Preparer
  • Services
  • SIBA Webinar Presentation
  • Sneak Peek Survey
  • Spring Tax Internship Program 2026
  • STL Ag Club Webinar Prez
  • Summer Audit Internship Program
  • Summer Audit Internship Program 2026
  • Tax Planning & Preparation
  • Tax Talks Information
  • Tax Talks Presentation
  • Testimonials
  • Webinar Presentation May 14
  • Welcome Email
  • Year-End Tax Planning Seminars
  • Accountant – Carrollton
  • Administrative Assistant – Alton Office
  • Administrative Assistant – Belleville Office
  • Administrative Assistant – Columbia Office
  • Seasonal Administrative Assistants
  • Seasonal Data Input
  • Staff Accountant

Categories

  • Blog
  • Construction
  • Coronavirus Resource Center
  • Frontpage
  • Knowledge Center
  • Scheffel News
  • Uncategorized

Archive

  • August 2026
  • May 2026
  • November 2025
  • October 2025
  • July 2025
  • February 2024
  • July 2023
  • May 2023
  • February 2023
  • January 2023
  • November 2022
  • August 2022
  • July 2022
  • June 2022
  • March 2022
  • February 2022
  • January 2022
  • December 2021
  • June 2021
  • May 2021
  • April 2021
  • March 2021
  • February 2021
  • January 2021
  • December 2020
  • November 2020
  • October 2020
  • September 2020
  • August 2020
  • July 2020
  • June 2020
  • May 2020
  • April 2020
  • March 2020
  • February 2020
  • January 2020
  • December 2019
  • November 2019
  • October 2019
  • September 2019
  • August 2019
  • July 2019
  • June 2019
  • May 2019
  • April 2019
  • March 2019
  • February 2019
  • January 2019
  • December 2018
  • November 2018
  • October 2018
  • September 2018
  • August 2018
  • July 2018
  • June 2018
  • May 2018
  • April 2018
  • March 2018
  • February 2018
  • January 2018
  • December 2017
  • November 2017
  • October 2017
  • September 2017
  • August 2017
  • July 2017
  • June 2017
  • May 2017
  • April 2017
  • March 2017
  • February 2017
  • January 2017
  • December 2016
  • October 2016
  • September 2016
  • August 2016
  • July 2016
  • May 2016
  • April 2016
  • March 2016
  • February 2016
  • January 2016
  • December 2015
  • November 2015
  • August 2015
  • July 2015
  • June 2015
  • February 2015
  • January 2015
  • December 2014
  • November 2014
  • September 2014
  • August 2014
  • March 2014
  • February 2014
  • December 2013
  • November 2013
  • October 2013
  • August 2013
  • July 2013
  • June 2013
  • May 2013
  • February 2013
  • January 2013

About Us


Serving St. Louis, the Metro-East and Southwestern Illinois since 1924.

Knowledge Center

  • New Rules Could Increase Taxable Income for GamblersAugust 24, 2026 - 3:20 pm
  • IRS Notice CP53E and the Rise of Refund-Related ScamsMay 18, 2026 - 9:55 am
  • Potential Refund Deadline Extensions Under the Kwong CaseMay 7, 2026 - 11:40 am

Quick Links

  • Services
  • Clients & Industries
  • Our Team
  • Scheffel Boyle News
  • Careers

 Contact Us

Alton, IL: 618.465.4288
Edwardsville, IL: 618.656.1206
Belleville, IL: 618.277.8100
Highland, IL: 618.654.9895
Jerseyville, IL: 618.498.6841
Columbia, IL: 618.281.7605
Carrollton, IL: 217.942.3821

© Copyright 2021 Scheffel Boyle — All rights reserved
  • Site Map
  • Privacy Policy
Scroll to top Scroll to top Scroll to top